
Amid reports of slowing e-commerce growth and rising competition, Amazon.com Inc. stocks have been trading down by -6.65 percent.
Key Takeaways
- Truist projects that Microsoft’s major AI and cloud peers will run negative free cash flow under heavy AI infrastructure spending, implicitly positioning them as financially weaker than Microsoft in the current AI investment cycle.
- Walmart and Amazon are cited as key competitors in online grocery and delivery, while the DoorDash–Instacart combination is framed as a stronger rival to their ongoing push into this market.
- Oppenheimer notes that Walmart’s new combined membership improves its membership value proposition versus Amazon Prime, potentially aiding Walmart’s share gains in delivery and e-commerce and marginally pressuring Amazon’s competitive position at the value end of the market.
- AliExpress’s new Elite VIP program for high-spending customers in Europe and other markets is described as a small but targeted competitive move against entrenched e-commerce players like Amazon.
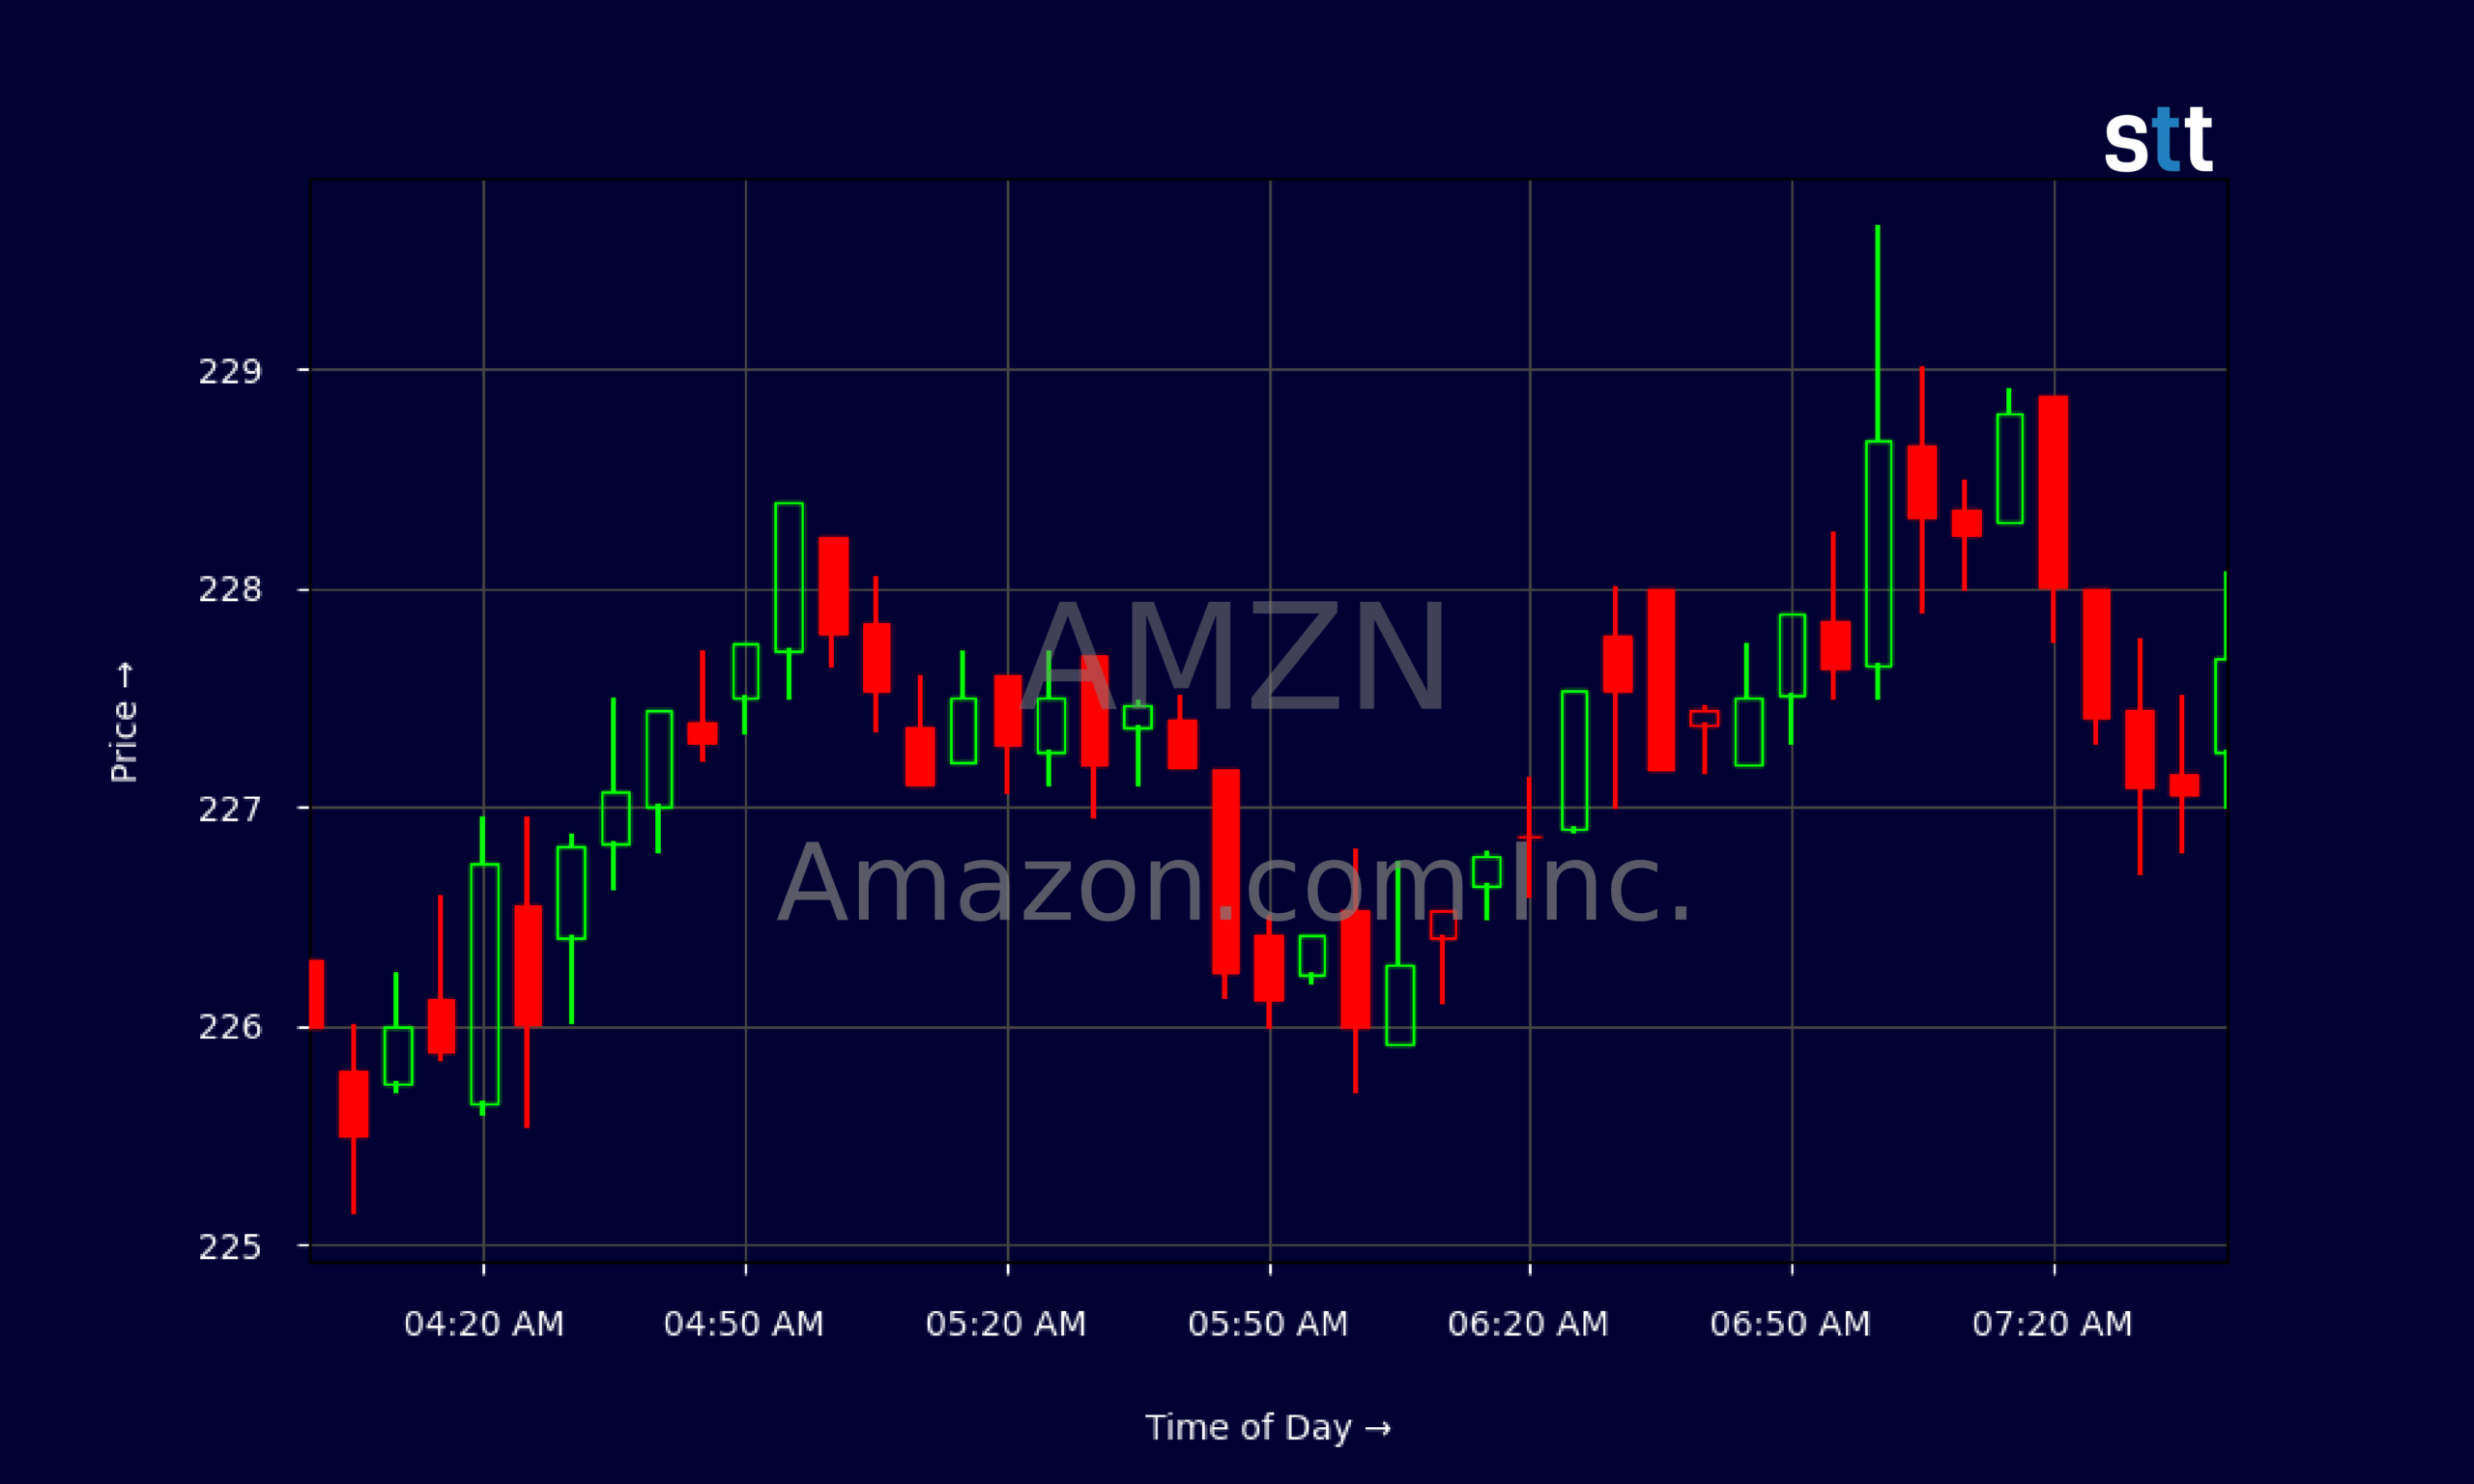
Live Update At 07:46:56 EDT: On Friday, October 30, 2026 Amazon.com Inc. stock [NASDAQ: AMZN] is trending down by -6.65%! Discover the key drivers behind this movement as well as our expert analysis in the detailed breakdown below.
Quick Financial Overview
AMZN has been chopping in a tight range, and that alone tells traders a lot. Over the past few weeks, AMZN has slipped from the mid‑$260s to about $243.79 on 2026/10/29. That’s a controlled pullback, not a crash, but it shows supply is building above $255–$260. Every bounce toward that area has been sold.
Short-term, AMZN’s intraday tape looks like classic low‑volatility consolidation. Most five‑minute candles cluster around the high‑$220s with very small ranges. That kind of action often precedes a bigger move, up or down, once a new catalyst hits. For active trading, that means tight risk levels matter more than big predictions.
Under the hood, AMZN’s fundamentals remain strong. Revenue over the last year is roughly $716.9B with a gross margin near 50.8%. An EBIT margin around 23% and profit margin of 17.4% show that AMZN is not just selling a ton of stuff; it’s doing it with solid profitability. A P/E near 21.1 and price-to-sales of 3.65 put AMZN in “premium but not crazy” territory for a mega‑cap tech and e‑commerce leader.
More Breaking News
- NCPL Stock Slides As Weak Financials Meet Fading Momentum
- CMCSA Stock Grinds Higher As Restructuring Meets Earnings Beat
- Micron Stock Slides As China’s CXMT DRAM Threat Rattles Traders
- BBAI Stock Pops As BigBear.ai Lands $225M In Federal AI Deals
Debt is manageable. Total debt-to-equity sits around 0.23, with interest coverage at 76.1, which means AMZN can service its obligations comfortably. For traders, that financial strength is a buffer, but the chart still rules the short-term trade.
Why Traders Are Watching AMZN’s Competitive Pressures
AMZN is not trading in a vacuum. The latest headlines show a clear theme: everybody wants a piece of Amazon.com Inc.’s core businesses. For momentum and swing traders, that competitive backdrop shapes how aggressive they want to be when AMZN nears resistance.
Start with AI and cloud. Truist projects that Microsoft’s big AI and cloud peers will run negative free cash flow thanks to heavy AI infrastructure spending. AMZN is one of those peers. The signal here is not that AMZN is weak today; it’s that the AI arms race demands huge upfront cash. If Microsoft is seen as the “safer” balance sheet, traders may discount AMZN’s multiple if AWS spending hits free cash flow too hard in the next cycle.
On the e‑commerce and delivery side, AMZN faces an evolving battlefield. Walmart and Amazon are flagged as key rivals in online grocery and delivery, but now the combined DoorDash–Instacart machine is being framed as a stronger third competitor. That cuts directly into Amazon.com Inc.’s long‑term push in fresh food and last‑mile convenience. More players chasing the same cart means tighter margins and slower share gains.
Then there’s Prime, one of AMZN’s biggest moats. Oppenheimer is calling out Walmart’s new combined membership as a better value pitch on the low‑end shopper. If value‑focused households drift to Walmart, AMZN’s Prime growth and pricing power can take a hit. Add AliExpress’s Elite VIP program in Europe going after high‑spending customers, and you see a pattern: from budget to VIP, Amazon.com Inc. is getting flanked globally.
For traders, this doesn’t mean AMZN is “finished.” It means rallies into overhead supply may face heavier selling as the market prices in these competitive overhangs.
Conclusion
Right now AMZN sits at an interesting crossroads. The financials show a powerhouse: over $200.6B in quarterly revenue as of 2026/06/30, EBITDA north of $102.1B, and strong return metrics — return on equity above 30% and solid returns on capital. Amazon.com Inc. is generating serious operating cash flow, about $45.4B for the recent quarter, even with heavy capital expenditure near $54.2B.
But Truist’s view on Microsoft and its AI peers warns that this cash engine is under pressure. To keep AWS and AI competitive, AMZN may need to push spending hard, which is already dragging free cash flow to roughly negative $8.8B in the latest period. That doesn’t break the story, yet it reminds traders that massive capex cycles often compress multiples and raise volatility.
Layer on Walmart’s membership push, the strengthened DoorDash–Instacart combo, and AliExpress’s VIP program, and AMZN’s once‑clean growth narrative now has real competitive noise on multiple fronts. For short‑term trading, that usually translates into range‑bound action punctuated by sharp moves on every headline or earnings print. In choppy, headline‑driven markets like this, discipline and patience become critical for day traders and swing traders alike. As Tim Bohen, lead trainer with StocksToTrade says, “Time and experience have taught me that missed opportunities are part of the game. There’s always another setup around the corner.” That mindset helps traders avoid forcing trades in AMZN when the risk/reward isn’t there.
The key, as Tim Sykes often says, is simple: “Trade the price action, not the hype.” AMZN still offers huge liquidity and clear levels, but Amazon.com Inc. is no longer the only predator in the jungle. Traders who respect the trend, cut losses fast, and stay alert to these competitive shifts will be in a better spot to react when AMZN finally breaks out of its current range — in either direction.
This is stock news, not investment advice. StocksToTrade News delivers real-time stock market updates tailored to highlight the key catalysts driving short-term price movements. Our coverage is designed for active traders and investors who thrive in fast-moving markets, with a focus on volatile sectors like penny stocks, AI stocks, Robinhood stocks and other momentum plays. From earnings reports and FDA approvals to mergers, new contracts, and unusual trading volume, we break down the events that can spark significant price action.
Looking to level up your trading game? Explore StocksToTrade, the ultimate platform for traders. With powerful tools designed for swing and day trading, integrated news scanning, and even social media monitoring, StocksToTrade keeps you one step ahead.
Check out our quick startup guide for new traders!
- How to Read Stock Charts: A Guide for Beginners
- Trading Plan: 6 Steps to Create One
- How To Create a Stock Watchlist
Ready to build your watchlists? Check out these curated lists:
Once your watchlist is set, take the next step and trade with confidence using StocksToTrade’s robust platform. Don’t miss out — grab your 14-day trial for just $7 and experience the edge you need to thrive in today’s fast-paced markets.