
AECOM stocks have been trading up by 4.7 percent after winning a major infrastructure contract, signaling strong growth expectations.
What Traders Need To Know
- Shares fell about 8.5% after Q3 2026 results were hit by a $337M pre-tax loss on a delayed legacy Construction Management project.
- Q3 adjusted EPS was $1.49 versus $1.46 expected on $3.59B revenue, below the $4.36B forecast, with management pointing to record wins and a backlog high.
- FY26 adjusted EPS guidance of $5.90–$6.10 and targets for 20%+ margins by FY28 and 15%+ adjusted EPS CAGR from FY26–FY29 were reaffirmed, excluding the charge.
- Major banks cut price targets but mostly kept Buy/Overweight/Outperform ratings, suggesting a near-term “penalty box” while legacy project risks clear.
- Legacy P3 and construction projects are expected to drive roughly $500M free cash flow drag and around $1.2B of cash outflows into H1 2027, likely pausing buybacks despite growth in the Design business.
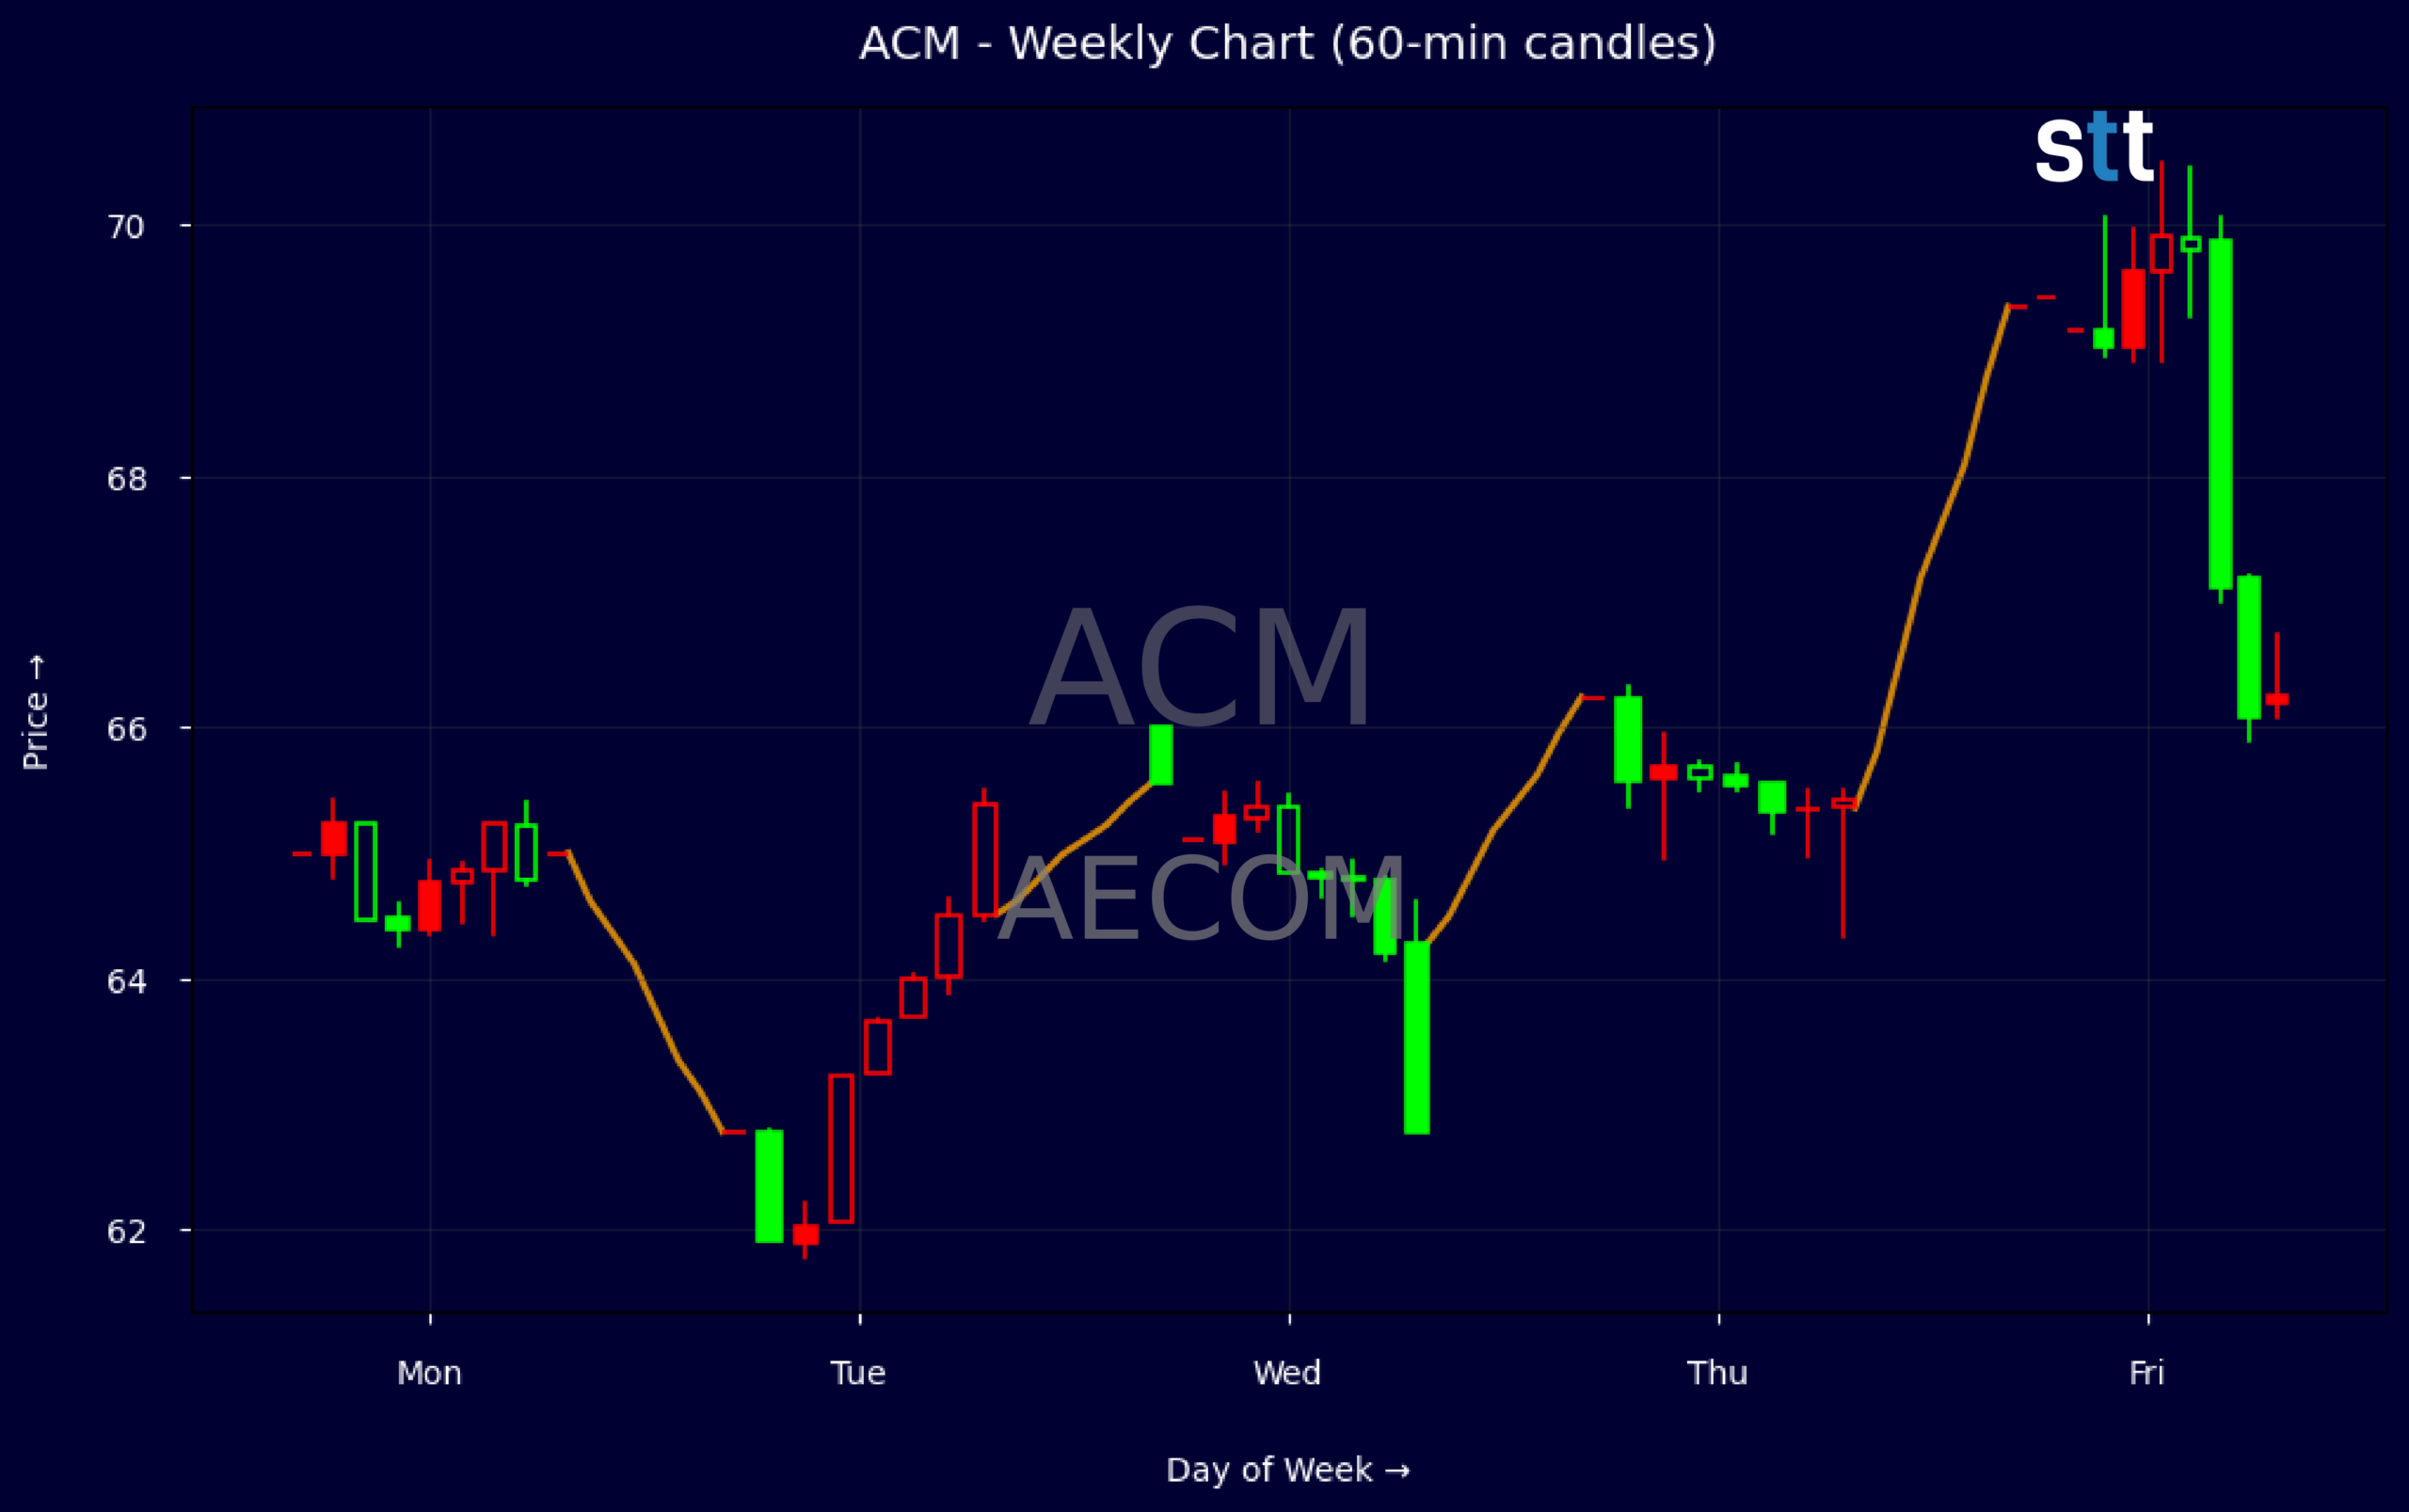
Weekly Update Aug 24 – Aug 28, 2026: On Saturday, August 29, 2026 AECOM stock [NYSE: ACM] is trending up by 4.7%! Discover the key drivers behind this movement as well as our expert analysis in the detailed breakdown below.
Industrials industry expert:
Analyst sentiment – positive
AECOM sits as a top‑tier design‑led infrastructure consultant with structurally attractive characteristics, but current fundamentals are mixed. Margins are thin for a fee business (EBIT 6.8%, EBITDA 7.6%, gross 5.1%) and net profitability is modest, reflected in a stretched 40x P/E and 0.74x sales. Revenue has declined low‑single digits over three and five years, yet ROIC at 12% and ROE at 13% remain solid. Leverage is elevated (D/E 1.46, interest coverage 5.6x), but liquidity is adequate and free cash flow conversion is strong.
Technically, the weekly tape shows a sharp rebound from a 62.78 low to a 69.35 close, reclaiming prior breakdown levels and signaling a short‑term momentum inflection after the post‑earnings gap‑down. Intraday five‑minute candles show buyers consistently supporting dips near 66, establishing that zone as immediate demand. With volume concentrated around 64–66 during the selloff, 64 is now the key line in the sand. A high‑conviction tactical long entry is 66–67 with a stop below 64 and first target at 75.
More Breaking News
- TNMG Stock Pulls Back As Traders Eye Debt And Support
- BTG Stock Pulls Back As Charts Flash Key Support
- CIFR Stock Slides As Volatility Grips Cipher Mining
- FDXF Stock Climbs As Momentum Traders Target Freight Play
The legacy construction management charge and 2027 cash drag put AECOM temporarily in the “penalty box,” but the design‑led core (90%+ of portfolio) is growing mid‑single digits with rising margins, and management reaffirmed strong FY26–29 EPS and margin targets. While Industrials peers trade on cleaner stories, AECOM’s risk/reward is superior at this reset level. I expect normalization of FCF from 2028, a rerating toward 18–19x mid‑cycle EPS, and a 12‑month target range of $80–85, with support at 62 and resistance near 75 and 85.
Quick Financial Overview
AECOM (ACM) is trading through a classic news shock: a large one-off project loss against a backdrop of a still-profitable core business. The weekly data show price dipping to $62.78 early in the week, then snapping back toward $69.35 by the latest print, a tight V-shape that often signals aggressive dip-buying after an overreaction. Intraday, the stock washed from the mid-$66s down below $66, then ripped to $70.50 and settled near $69.17, confirming strong intraday demand on bad headlines.
On the fundamental side, AECOM reported Q3 2026 revenue of $3.59B, well above one data-provider estimate of $2.01B but below the more widely cited $4.36B expectation, and booked a $337M pre-tax loss on a legacy Construction Management project. Adjusted EPS of $1.49 still beat the $1.46 consensus, and management highlighted record wins plus an all-time-high backlog. Key ratios show thin margins today (EBIT margin 6.8%, profit margin under 2.5%), but also a price-to-sales of 0.74, which is not demanding if margin expansion plays out.
Leverage is notable: total debt to equity of 1.46 and a current ratio near 1.1 tell traders this is not a fortress balance sheet, though interest coverage around 5.6 is adequate. The PE ratio near 41 looks rich against current earnings, but management is reaffirming FY26 EPS of $5.90–$6.10 and long-term 20%+ margin and 15%+ EPS CAGR targets, which, if achieved, would backfill that valuation. Cash flow data show positive free cash flow of roughly $54.9M in the recent period, but the Street is flagging about $500M in free cash flow drag and roughly $1.2B in cash outflows tied to legacy projects into 2027, plus a likely pause in buybacks.
Conclusion
From a trading lens, ACM now sits at the intersection of headline risk and fundamental resilience. The stock just absorbed an 8.5% hit on the Q3 2026 report, driven by the $337M legacy project loss and guidance around heavy cash outflows into 2027. Yet price quickly rebounded off the low-$60s back toward the high-$60s, while analysts at Goldman Sachs, Citi, Truist, KeyBanc, RBC, BofA, and Argus mostly kept Buy-type ratings even as they trimmed targets.
The core story is simple: over 90% of AECOM’s portfolio is in the Design business, growing around 5% organically, while a handful of old P3 and construction jobs will likely weigh on free cash flow and restrain capital returns for roughly the next year and a half. Management is still reaffirming FY26 EPS of $5.90–$6.10 and long-term goals for 20%+ margins and mid-teens EPS growth, but traders need to decide whether that confidence offsets the balance-sheet and execution risk implied by the cash drag. Volatility around headlines on these projects is likely to stay elevated.
For active traders, ACM can be treated as a catalyst-driven, range-trading name: buy panic toward the low end of the range when legacy fears spike, and sell strength as the market relaxes, always with tight risk controls. This is where disciplined trade selection really matters. As Tim Bohen, lead trainer with StocksToTrade says, “A good trade setup checks all the boxes—volume, trend, catalyst. Don’t trade if you’re missing pieces of the puzzle.” As I tell my students, “The edge isn’t in predicting the company’s future; it’s in reading how the crowd misprices today’s risk and structuring your trades around that mispricing.” This stock is a live case study of that principle for educational and research-focused traders.
This is stock news, not investment advice. StocksToTrade News delivers real-time stock market updates tailored to highlight the key catalysts driving short-term price movements. Our coverage is designed for active traders and investors who thrive in fast-moving markets, with a focus on volatile sectors like penny stocks, AI stocks, Robinhood stocks and other momentum plays. From earnings reports and FDA approvals to mergers, new contracts, and unusual trading volume, we break down the events that can spark significant price action.
Looking to level up your trading game? Explore StocksToTrade, the ultimate platform for traders. With powerful tools designed for swing and day trading, integrated news scanning, and even social media monitoring, StocksToTrade keeps you one step ahead.
Check out our quick startup guide for new traders!
- How to Read Stock Charts: A Guide for Beginners
- Trading Plan: 6 Steps to Create One
- How To Create a Stock Watchlist
Ready to build your watchlists? Check out these curated lists:
Once your watchlist is set, take the next step and trade with confidence using StocksToTrade’s robust platform. Don’t miss out — grab your 14-day trial for just $7 and experience the edge you need to thrive in today’s fast-paced markets.