
Vail Resorts Inc. stocks have been trading up by 12.37 percent amid strong travel demand and elevated leisure spending.
What Traders Need To Know
- Shares of Vail Resorts Inc. spiked about 10–11% after reports it hired takeover-defense bankers to assess risks from labor pressures, a billionaire shareholder, and potential activist traders.
- Fiscal Q3 EPS of $8.81 came in slightly below consensus around $8.95–$8.97, while roughly $1.21B in revenue landed in line to slightly above expectations.
- Management blamed historically poor Western U.S. snowfall for weak visitation and double-digit season pass declines, pressuring both recent results and 2026/2027 visibility.
- Multiple brokers cut MTN price targets after Q3, yet Truist, Stifel, and Mizuho still maintain Buy or Outperform ratings, and the broader Street stance remains overweight.
- Despite the recent event-driven spike, Vail Resorts Inc. shares are still down roughly 14% over the past year, keeping valuation and downside risk firmly in play.
Weekly Update Jun 15 – Jun 19, 2026: On Saturday, June 20, 2026 Vail Resorts Inc. stock [NYSE: MTN] is trending up by 12.37%! Discover the key drivers behind this movement as well as our expert analysis in the detailed breakdown below.
Consumer Discretionary industry expert:
Analyst sentiment – positive
Vail Resorts occupies a dominant North American mountain resort position with structurally strong unit economics, reflected in an exceptional 79% gross margin, 26% EBITDA margin, and high-teens ROIC. However, modest 5-year revenue CAGR (~10%) has stalled (3-year revenue CAGR negative), and leverage is elevated (total debt/equity 5.8x, LT debt/cap 85%, interest cover 3.7x). Cash generation is currently weak (Q3 FCF -$28M, working capital drag), yet management continues an aggressive ~6% dividend yield, implying confidence but constraining balance-sheet flexibility.
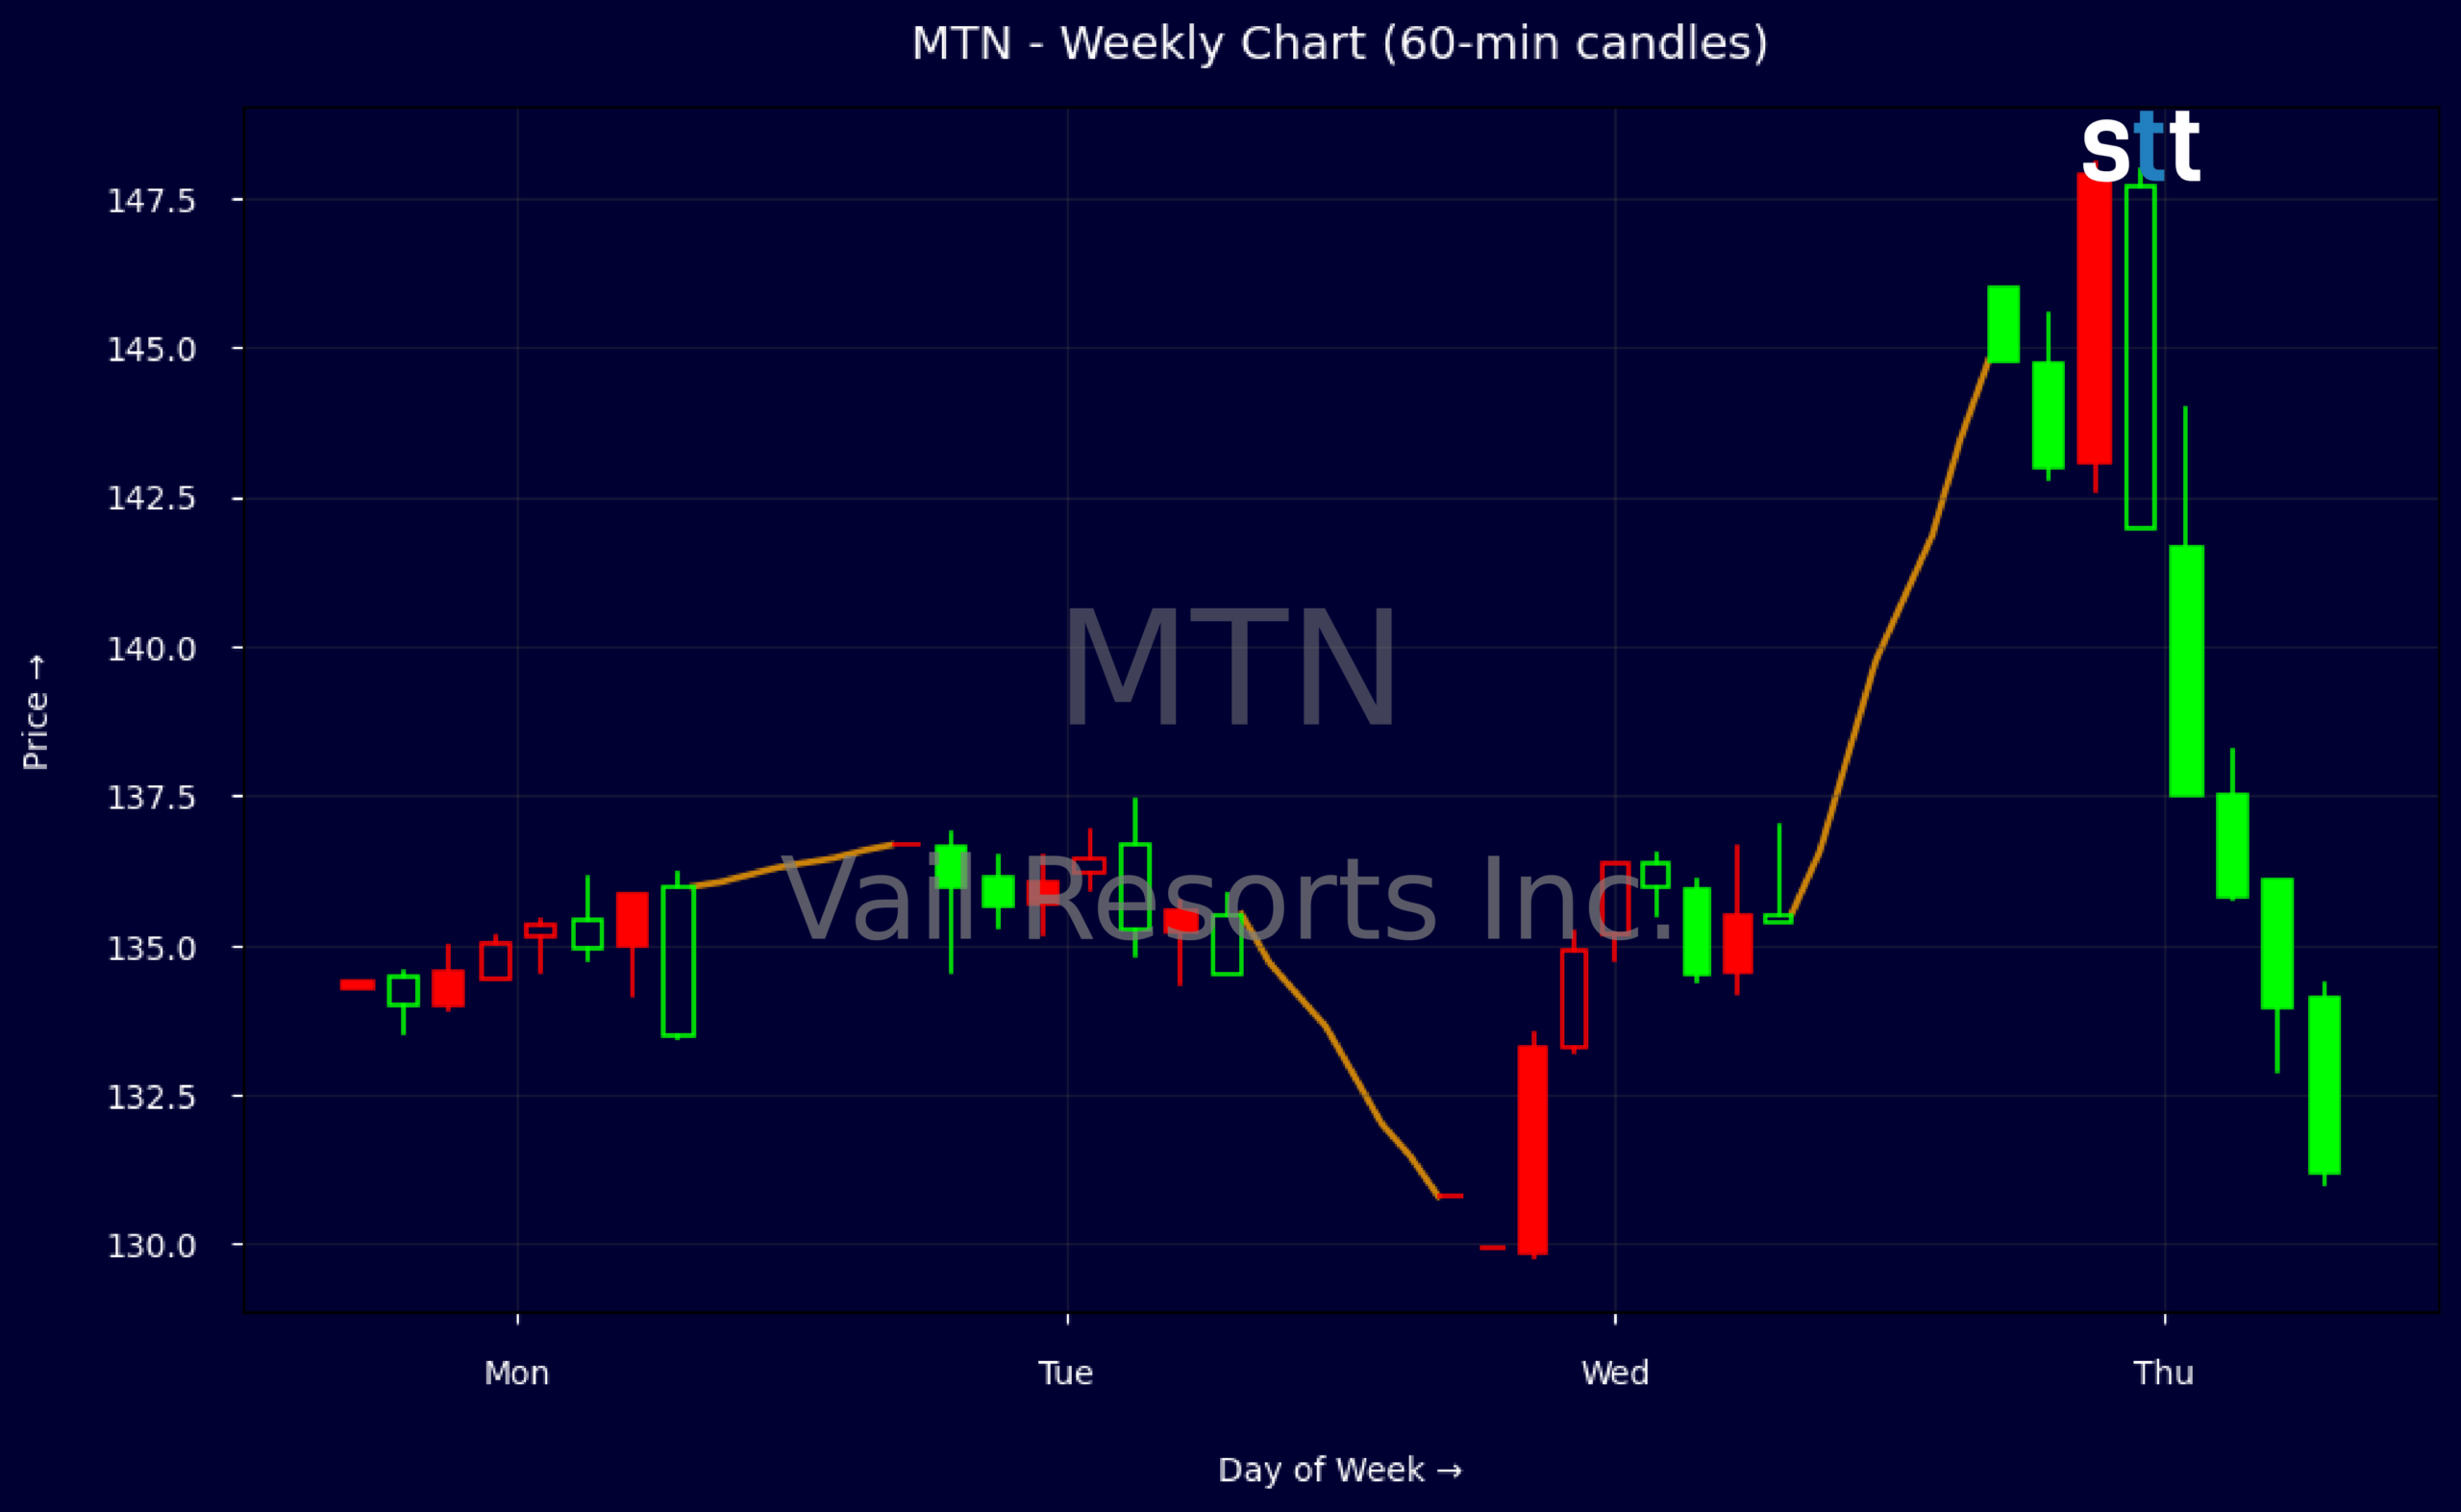
Technically, MTN has staged a sharp rebound from sub-$130 levels, printing a series of higher closes from 129.93 to 146 this week, confirming a short-term bullish reversal after prolonged underperformance. Intraday 5-minute action shows strong upside candles on elevated volume following the takeover-defense headlines, with shallow pullbacks being bought. The key actionable level is support at $136–138 (prior reaction area and volume node); above that, upside targets $150–152. A decisive weekly close below $136 invalidates the momentum long setup.
More Breaking News
- GPN Rises As Global Payments Scores Wave Of Upgrades
- SOFI Stock Slips As Analyst Cuts Price Target To $15
- NCPL Plunges As SEC Fraud Charges Ignite Legal Firestorm
- WKHS Stock Draws Traders As EV Orders Grow And AI Pivot Emerges
Near term, weather-driven visitation headwinds and double-digit pass unit declines keep fundamentals below Consumer Discretionary and Hotels, Lodging & Leisure growth benchmarks, but margins and ROE remain superior. Broker downgrades are primarily about trajectory, not model viability, and activist/strategic-interest chatter plus a defended 6% dividend create an attractive risk/reward. I view MTN as a buy on pullbacks toward $136–138 with 12–18 month upside to $170 and downside support near $125.
Quick Financial Overview
Vail Resorts Inc. just printed a classic “good business, tough quarter” setup. Fiscal Q3 revenue of about $1.21B was slightly ahead of expectations, but EPS of $8.81 missed consensus by a few cents and fell year over year. Management pinned the softness on historically poor snow in the Western U.S., which hurt destination Rockies resorts and pushed season pass units into double-digit declines. For traders, that means near-term fundamentals are weather-hit, not structurally broken, but visibility into the 2026/2027 season is softer.
The balance sheet and ratios show a leveraged but still functioning machine. MTN runs with total debt to equity near 5.8 and a leverage ratio above 10, while interest coverage around 3.7 suggests debt is serviceable but not light. Profitability metrics remain solid for a resort operator, with EBITDA margin above 26% and gross margin around 79%. Return on equity above 20% reflects strong earnings power on the existing asset base, even as asset turnover sits near 0.5. Traders should also note the rich valuation: a P/E near 29.8 and price-to-sales around 1.6 mean the market still pays up for the franchise.
Cash flow is more mixed. Operating cash flow this quarter was modest, around $6.8M, with free cash flow negative by roughly $28M after capex, while MTN still paid about $79M in dividends. Yet the company maintained its sizable $2.22 quarterly payout, implying confidence in longer-term cash generation and supporting a dividend yield above 6%. On the chart, weekly data show MTN ripping from the low $130s to about $146 into 2026/06/18, with an intraday spike from roughly $131 to $148 on the takeover-defense news. That sort of event-driven gap tells traders volatility is back in this name.
Conclusion
This is stock news, not investment advice. StocksToTrade News delivers real-time stock market updates tailored to highlight the key catalysts driving short-term price movements. Our coverage is designed for active traders and investors who thrive in fast-moving markets, with a focus on volatile sectors like penny stocks, AI stocks, Robinhood stocks and other momentum plays. From earnings reports and FDA approvals to mergers, new contracts, and unusual trading volume, we break down the events that can spark significant price action.
Looking to level up your trading game? Explore StocksToTrade, the ultimate platform for traders. With powerful tools designed for swing and day trading, integrated news scanning, and even social media monitoring, StocksToTrade keeps you one step ahead.
Check out our quick startup guide for new traders!
- How to Read Stock Charts: A Guide for Beginners
- Trading Plan: 6 Steps to Create One
- How To Create a Stock Watchlist
Ready to build your watchlists? Check out these curated lists:
Once your watchlist is set, take the next step and trade with confidence using StocksToTrade’s robust platform. Don’t miss out — grab your 14-day trial for just $7 and experience the edge you need to thrive in today’s fast-paced markets.