

Snap Inc. stocks have been trading up by 2.9 percent amid optimism over stronger advertising demand and user engagement.
Key Takeaways For SNAP Traders
- Q2 EPS loss of $0.10 beat expectations and revenue hit $1.599B, up 19% year over year, with positive free cash flow and support from 971M monthly active users.
- Daily active users reached 493M, topping the 487.9M consensus and reinforcing the ad story.
- Management guided Q3 revenue to $1.7B–$1.74B and sees adjusted EBITDA of $300M–$350M, signaling stronger profitability ahead.
- Shares ripped roughly 14%–15% after SNAP’s Q2 beat, powered by a 9% jump in ad revenue and strong adoption of AI-driven ad tools.
- SNAP raised its FY26 infrastructure cost outlook to $1.65B–$1.7B for AI and ML build‑out and targets sustained positive net income from 2027, while warning about youth-focused regulatory risks.
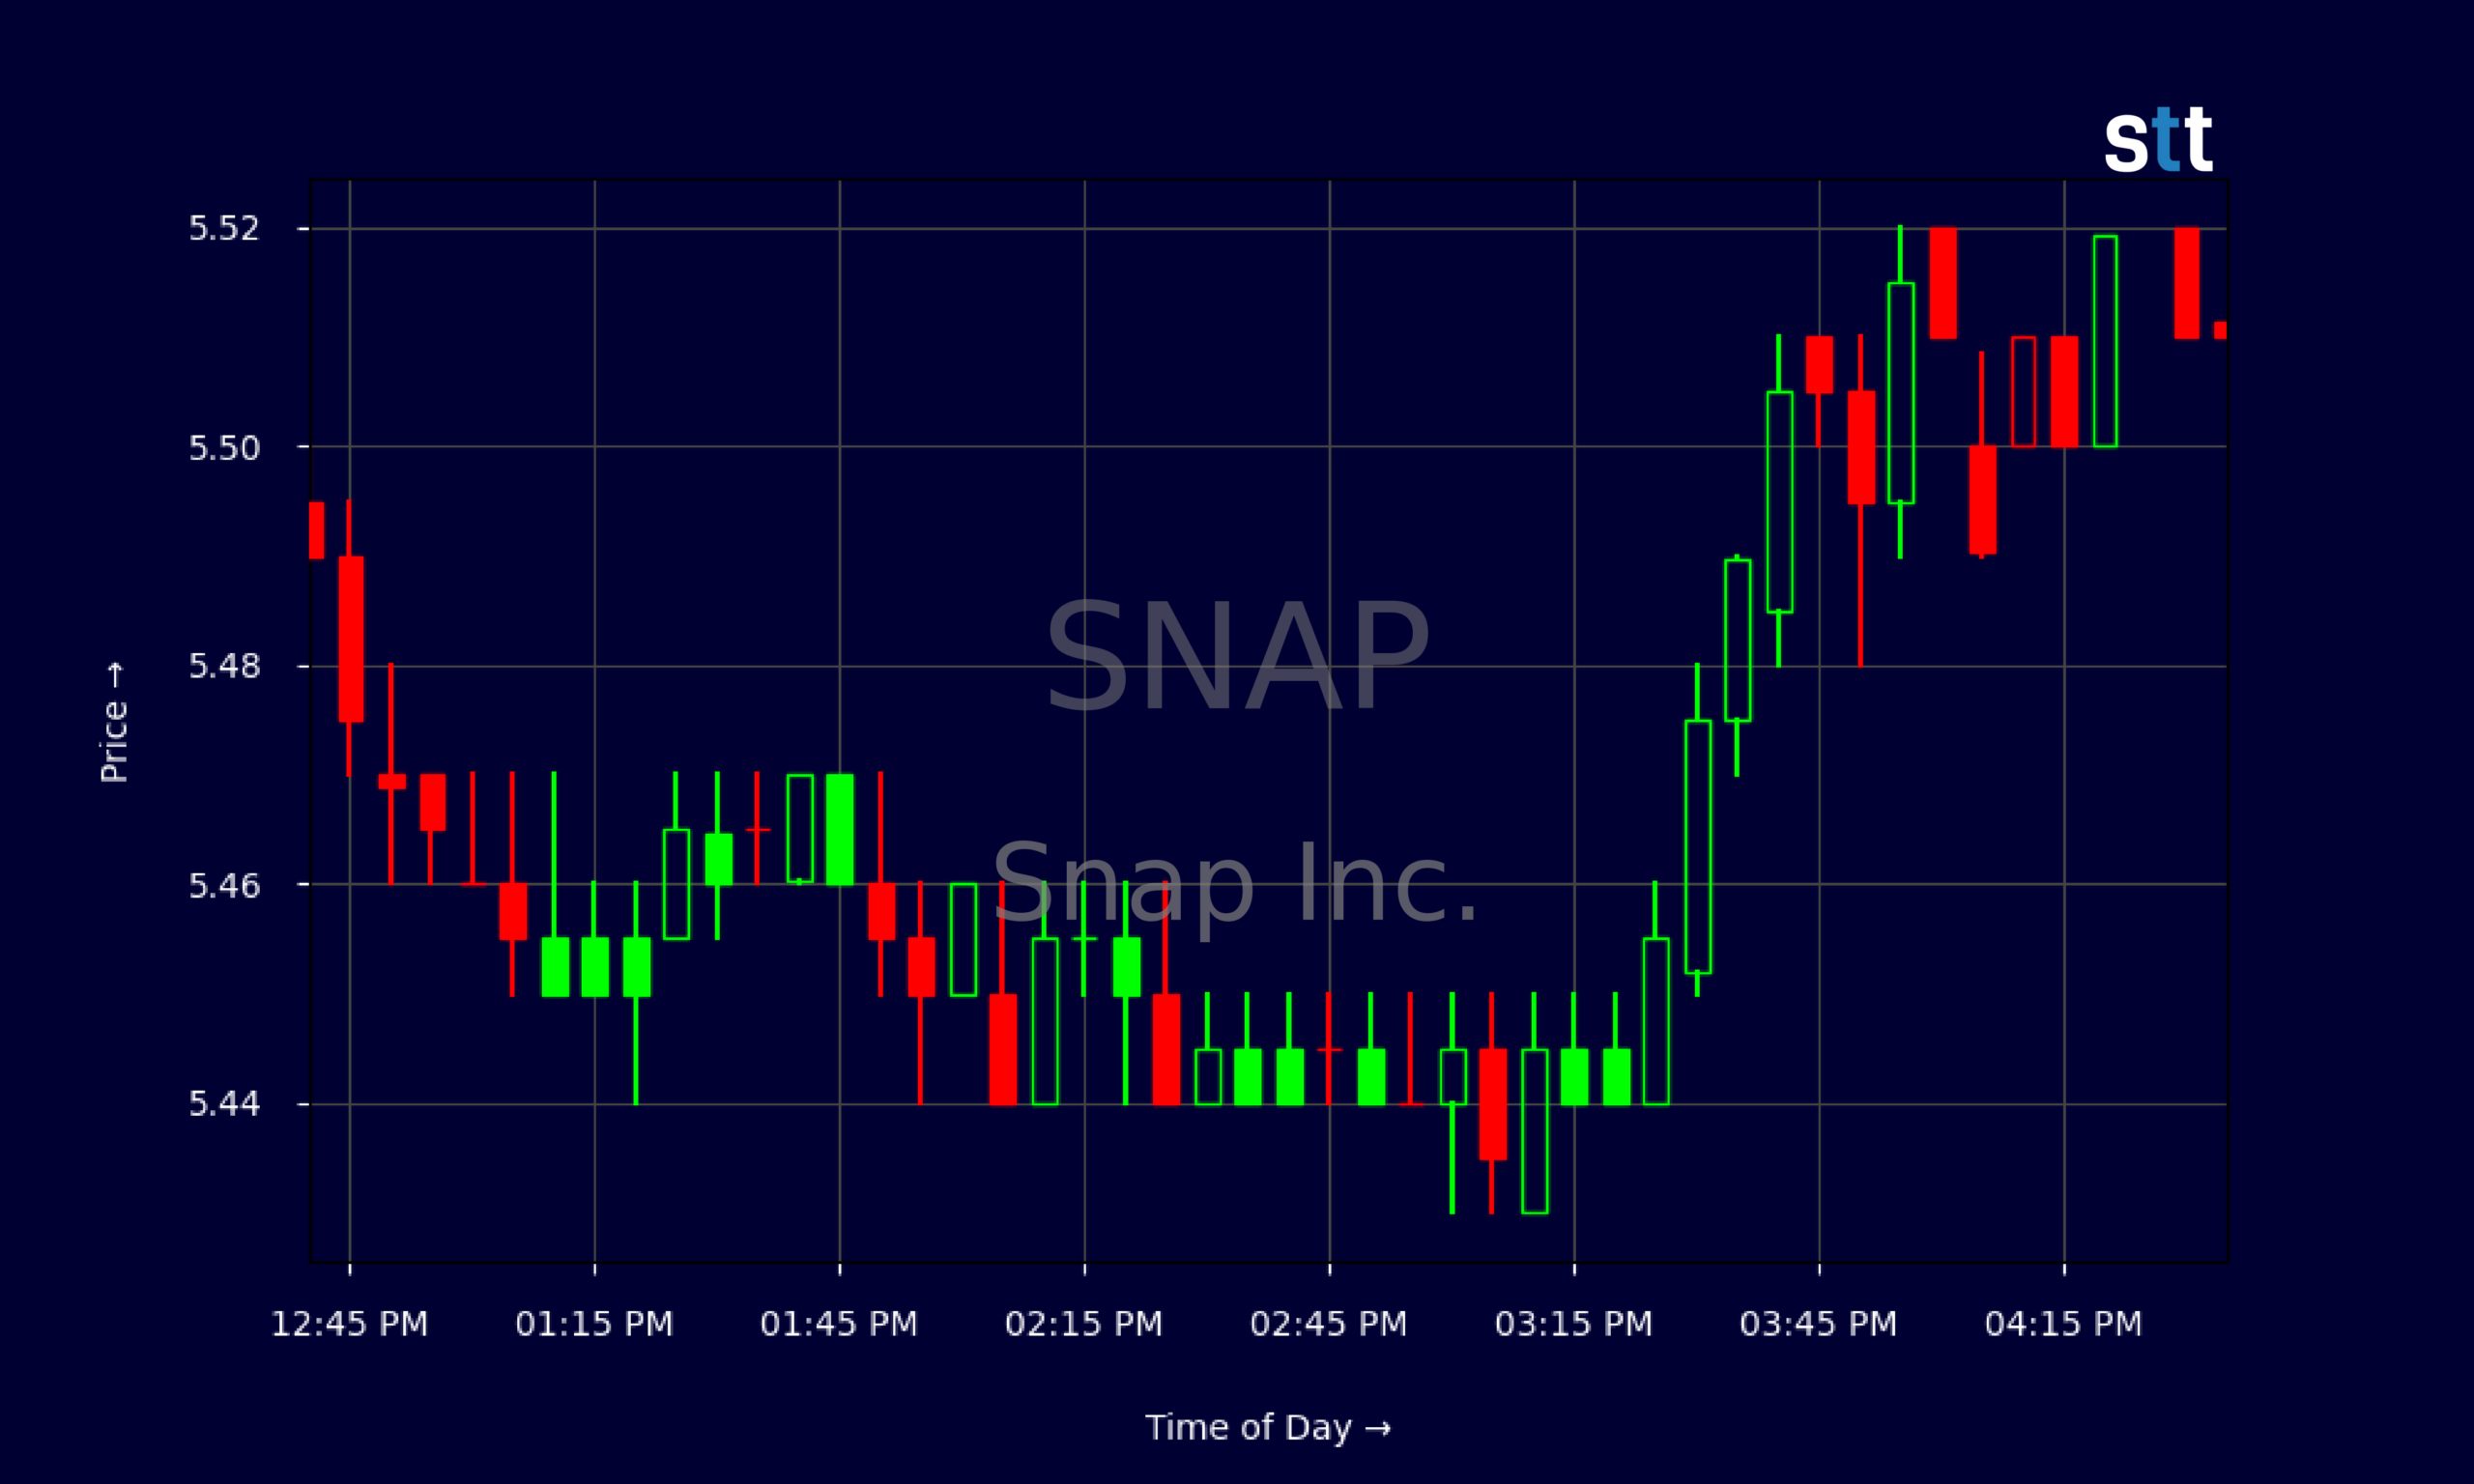
Live Update At 16:51:46 EDT: On Tuesday, August 11, 2026 Snap Inc. stock [NYSE: SNAP] is trending up by 2.9%! Discover the key drivers behind this movement as well as our expert analysis in the detailed breakdown below.
Quick Financial Overview
SNAP just printed the kind of quarter that wakes up sleepy charts. Revenue for Q2 2026 climbed to about $1.60B, up 19% from a year ago and ahead of roughly $1.53B expectations. The loss narrowed to $0.10 per share versus $0.16 last year, and while SNAP is still not GAAP-profitable, the direction finally lines up with the bullish narrative.
Free cash flow flipped positive at about $120.5M, which matters for any trader worried about future capital raises. Gross margin sits near 78%, showing the core ad and services engine is high-margin once scale kicks in. The flip side: profitability ratios are still negative and stock-based compensation remains heavy, with dilution risk hanging over the story.
More Breaking News
- FDXF Stock Climbs As Traders Focus On Debt, Momentum
- INSM Extends Brinsupri Global Reach As Traders Eye Guidance
- Micron Stock Slides As China’s CXMT DRAM Threat Rattles Traders
- CETX Stock Pops On Volume As Traders Eye Turnaround Hopes
On the chart, SNAP has broken out from the mid-$4s to the mid-$5s over the past few weeks. Q2 earnings triggered a gap from about $4.78 on 2026/08/03 to closes around $5.79 the next day, a classic momentum ignition. Recent daily action around $5.35–$5.51 shows consolidation, not a collapse, which tells traders dip-buyers are still supporting this move. Intraday, SNAP is trading in a tight $5.45–$5.55 band, signaling a possible coil before the next news‑driven leg.
Why Traders Are Watching SNAP’s Momentum
SNAP has turned itself back into a true momentum ticker after this Q2 2026 print. The company beat on both the top and bottom line, with revenue at $1.599B versus $1.53B expected and a smaller‑than‑feared $0.10 loss. That 19% revenue growth is not just a macro rebound story. Management pointed to a 56% jump in ad conversions, fueled by upgrades to its ad platform, more automation, and better go‑to‑market execution.
For traders, that detail matters. It says SNAP’s ad tech is actually working better, especially for app, e‑commerce, and other lower‑funnel advertisers. When conversions rise, ad budgets follow, and that’s exactly what SNAP is reporting: rising spend from existing advertisers and a 9% lift in ad revenue overall. Add in 493M daily active users and 971M monthly active users, and the platform’s scale now has real monetization teeth.
The Street is taking notice. Freedom Broker upgraded SNAP from Hold to Buy, with a $7.50 target tied to North American ad recovery and leaner operations. Barclays bumped its price target from $15 to $16 and kept an Overweight stance after seeing nearly 20% growth and clearer footing. Even Cantor Fitzgerald, still Neutral, raised its target from $5 to $6 on better ad trends, subscriptions, and healthier demand. Those mixed but improving calls show a classic sentiment shift: bears are backing off, bulls are pressing.
Guidance backs the momentum. SNAP is steering Q3 revenue to $1.7B–$1.74B, above the $1.69B consensus midpoint, and expects $300M–$350M in adjusted EBITDA. Management is also leaning into AI and machine learning, hiking FY26 infrastructure spend to $1.65B–$1.7B to keep SNAP’s ad tools competitive. That spending is not cheap, but the market just rewarded it with a 14%–15% post‑earnings surge.
Conclusion
For active traders, SNAP is now a battleground between near‑term momentum and longer‑term execution risk. On one side, you have a chart that has broken out from roughly $4.50 to the mid‑$5s on heavy volume after an earnings beat, tighter losses, and positive free cash flow. Daily and intraday action show consolidation instead of a full fade, which usually signals that strong hands are in control, at least for now.
On the other side, SNAP is still GAAP-unprofitable, with negative return on equity and a leveraged balance sheet. Management is promising continued gross margin gains, adjusted EBITDA expansion, and sustained positive net income starting in 2027. To get there, the company will spend heavily on AI infrastructure and must navigate serious legal and regulatory risks tied to its youth‑heavy audience. SNAP also knows traders are watching dilution, so it laid out a plan to keep the fully diluted share count stable by 2027 via a buyback‑style program.
For day traders and swing traders, the playbook is straightforward: respect the volatility, map the levels, and do not fall in love with the story. As Tim Sykes likes to remind his students, “The market rewards discipline, not hope — cut losses quickly and only stick with plays that prove themselves.” And as Tim Bohen, lead trainer with StocksToTrade says, “Time and experience have taught me that missed opportunities are part of the game. There’s always another setup around the corner.”, a mindset that helps traders avoid chasing and stay focused on high‑quality setups. SNAP’s Q2 numbers have earned it a fresh look, but the only thing that matters now is how the stock trades from here. This is educational and research content only, not a recommendation to buy or sell any security.
This is stock news, not investment advice. StocksToTrade News delivers real-time stock market updates tailored to highlight the key catalysts driving short-term price movements. Our coverage is designed for active traders and investors who thrive in fast-moving markets, with a focus on volatile sectors like penny stocks, AI stocks, Robinhood stocks and other momentum plays. From earnings reports and FDA approvals to mergers, new contracts, and unusual trading volume, we break down the events that can spark significant price action.
Looking to level up your trading game? Explore StocksToTrade, the ultimate platform for traders. With powerful tools designed for swing and day trading, integrated news scanning, and even social media monitoring, StocksToTrade keeps you one step ahead.
Check out our quick startup guide for new traders!
- How to Read Stock Charts: A Guide for Beginners
- Trading Plan: 6 Steps to Create One
- How To Create a Stock Watchlist
Ready to build your watchlists? Check out these curated lists:
Once your watchlist is set, take the next step and trade with confidence using StocksToTrade’s robust platform. Don’t miss out — grab your 14-day trial for just $7 and experience the edge you need to thrive in today’s fast-paced markets.