
Pinterest Inc. stocks have been trading down by -5.05 percent after disappointing user-growth metrics sparked renewed investor concern.
Key Takeaways
- Q3 revenue came in at $1.17B for Pinterest, below the $1.21B FactSet consensus, signaling demand is lagging expectations.
- The company missed Q4 2025 revenue forecasts and guided Q1 2026 revenue lower, blaming tariff-related headwinds.
- Management guided Q4 2026 revenue to $1.425B–$1.475B, under the $1.52B Street view, even as adjusted EBITDA is projected at $538M–$588M.
- Ad agency and Evercore channel checks on PINS were “incrementally cautious,” flagging softer ad demand versus stronger peers.
- A law firm has opened an investigation into possible fiduciary breaches tied to an existing securities class action against Pinterest.
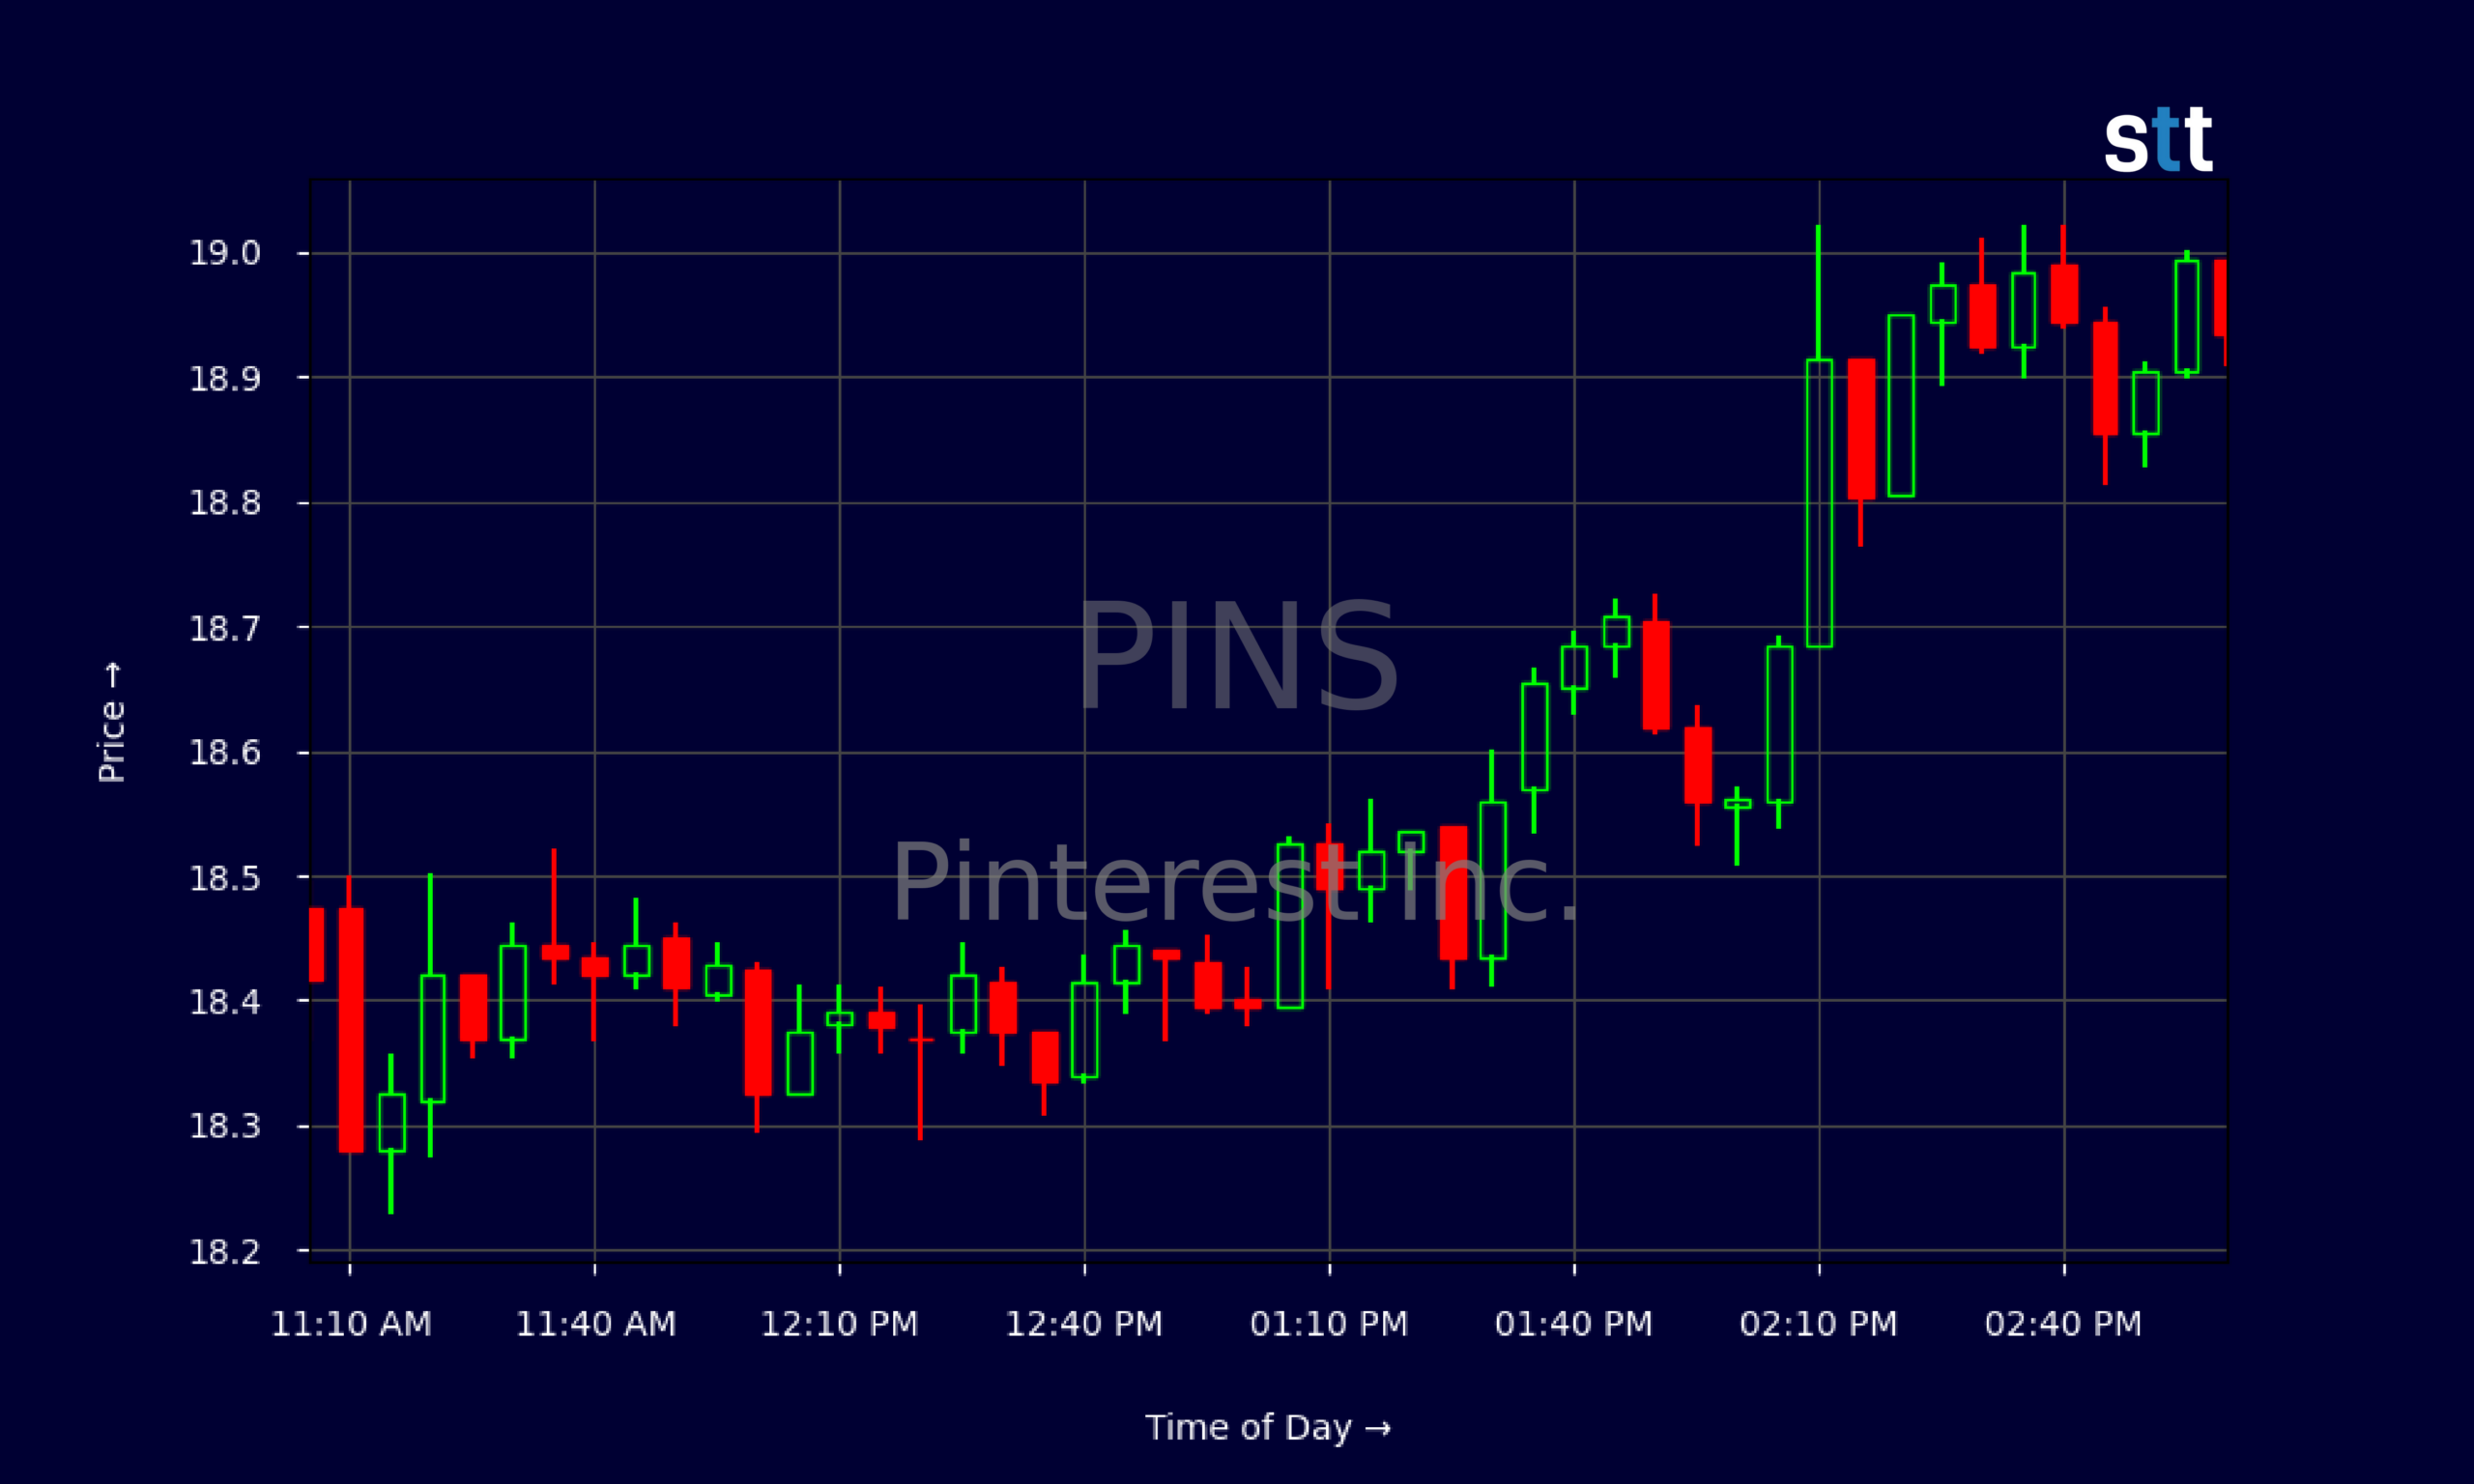
Live Update At 15:03:02 EDT: On Friday, October 30, 2026 Pinterest Inc. stock [NYSE: PINS] is trending down by -5.05%! Discover the key drivers behind this movement as well as our expert analysis in the detailed breakdown below.
Quick Financial Overview
PINS has slipped into a clear downtrend on the daily chart. The stock traded above $22 earlier in October 2026 but slid to around $18.94 by 2026/10/30. That is a sharp reset in a couple of weeks, and the tape shows steady selling pressure rather than one quick flush. For short-term traders, that often means any bounce can be a fade until the trend changes.
Intraday, Pinterest spent the latest session grinding between roughly $18.30 and $19.00, with tight 5‑minute candles and no real trend reversal. This looks like classic post-earnings digestion where funds are repositioning after bad news.
Fundamentally, Pinterest still throws off solid cash. Quarterly operating cash flow was about $316M, with free cash flow around $300M. Margins are thin at the EBIT level, roughly 4%, but the gross margin is a huge 90.8%, which tells traders the core ad product remains high-margin once traffic is monetized. The balance sheet is clean, with a current ratio near 3.8 and modest leverage.
More Breaking News
- CareDx CDNA Rips Higher After Big Earnings Beat And Guidance Hike
- CareDx Stock Jumps As Earnings Beat And Guidance Surge Draw Trader Focus
- FCN Stock Jumps As Global Expansion Outruns Cautious Analyst Target
- SNDG ETF Slides As Volatility Pressures Bullish Traders
Valuation, however, is not cheap. A P/E near 63 and price‑to‑sales around 2.7 leave little room for error. When PINS misses revenue and guides below consensus, that rich multiple becomes a problem fast.
Why Traders Are Watching PINS Right Now
Pinterest has stacked several negative headlines in a short window, and traders are treating it as a momentum short rather than a growth story. First came the Q3 print: $1.17B in revenue versus $1.21B expected. On its own, that is a small miss. But for a high‑multiple name like PINS, it is a big credibility hit. Repeated misses tell the market management is having trouble reading ad demand.
Then PINS followed up by missing Q4 2025 revenue expectations and cutting Q1 2026 guidance. Management pointed to tariff‑related headwinds, which adds a macro excuse on top of execution risk. For active traders, excuses do not matter. Price reacts to numbers, not narratives. Weak guidance usually means more cuts can come if the ad market stays choppy.
The law firm investigation into possible fiduciary breaches linked to an existing securities class action throws another cloud over Pinterest. Legal overhangs do not always change the business, but they can cap upside because big funds hate uncertainty. While that plays out, traders often lean short or stay on the sidelines.
Forward‑looking commentary has not helped. Pinterest guided Q4 2026 revenue to $1.425B–$1.475B, up 8%–12% year over year but still below the $1.52B consensus. At the same time, management is targeting adjusted EBITDA of $538M–$588M, which shows improving profitability but not enough to offset slowing top‑line momentum. Channel checks from ad agencies and Evercore described PINS as “incrementally cautious,” hinting that big brands may be parking more budget with stronger peers. For traders, that is a clear relative‑strength tell: PINS is the weak link in the ad basket for now.
Conclusion
Right now, Pinterest is a textbook example of what happens when high expectations collide with soft execution. Revenue of $1.17B versus $1.21B expected, repeated guidance cuts, and tariff‑related pressure have shifted the story from “growth winner” to “show‑me” name. Layer on an ongoing securities class action and a fresh law firm investigation into possible fiduciary breaches, and traders have plenty of reasons to demand a discount on PINS.
Yet the core economics remain attractive. Gross margins around 90%, strong free cash flow near $300M in the latest quarter, and a healthy balance sheet give Pinterest room to fix its growth problem. The real question for traders is timing. Do you wait for the next flush, or stalk a short squeeze if sentiment swings?
For now, the chart says respect the downtrend. PINS has broken from the low‑$20s into the high‑$18s with no real buyer aggression on intraday tape. Until Pinterest can beat revenue, lift guidance, or surprise with stronger ad demand, rallies are suspect. As Tim Bohen, lead trainer with StocksToTrade says, “A good trade setup checks all the boxes—volume, trend, catalyst. Don’t trade if you’re missing pieces of the puzzle.” In the case of PINS, the volume and trend are signaling caution, and without a clear catalyst, many disciplined traders will stay sidelined or size down.
As Tim Sykes loves to say, “Patterns repeat because human nature doesn’t change.” Pinterest is trading through that lens right now. The pattern is weak numbers, cautious commentary, and a heavy chart. Smart traders study that setup, define risk tightly, and remember that this is education and research only — never a signal to buy or sell.
This is stock news, not investment advice. StocksToTrade News delivers real-time stock market updates tailored to highlight the key catalysts driving short-term price movements. Our coverage is designed for active traders and investors who thrive in fast-moving markets, with a focus on volatile sectors like penny stocks, AI stocks, Robinhood stocks and other momentum plays. From earnings reports and FDA approvals to mergers, new contracts, and unusual trading volume, we break down the events that can spark significant price action.
Looking to level up your trading game? Explore StocksToTrade, the ultimate platform for traders. With powerful tools designed for swing and day trading, integrated news scanning, and even social media monitoring, StocksToTrade keeps you one step ahead.
Check out our quick startup guide for new traders!
- How to Read Stock Charts: A Guide for Beginners
- Trading Plan: 6 Steps to Create One
- How To Create a Stock Watchlist
Ready to build your watchlists? Check out these curated lists:
Once your watchlist is set, take the next step and trade with confidence using StocksToTrade’s robust platform. Don’t miss out — grab your 14-day trial for just $7 and experience the edge you need to thrive in today’s fast-paced markets.