
Boosted by strong medical device demand, Integer Holdings Corporation stocks have been trading up by 20.4 percent today.
What Traders Need To Know
- Reports say KKR is close to acquiring Integer Holdings at about $127 per share, a strong premium that effectively anchors near-term upside.
- Shares jumped more than 20% on the headlines, with traders quickly repricing the stock from around $101 toward the rumored buyout level.
- Freedom Capital started coverage with a Buy and $112 target, calling Integer Holdings a scaled, well-positioned medtech CDMO despite an expected 2026 earnings dip.
- Truist lifted its target to $110 and kept a Buy rating, flagging Integer Holdings Corporation as a relative winner in a soft medtech tape.
- Citi nudged its target to $96 with a Neutral view, still seeing room for a catch-up move if sector sentiment stabilizes.
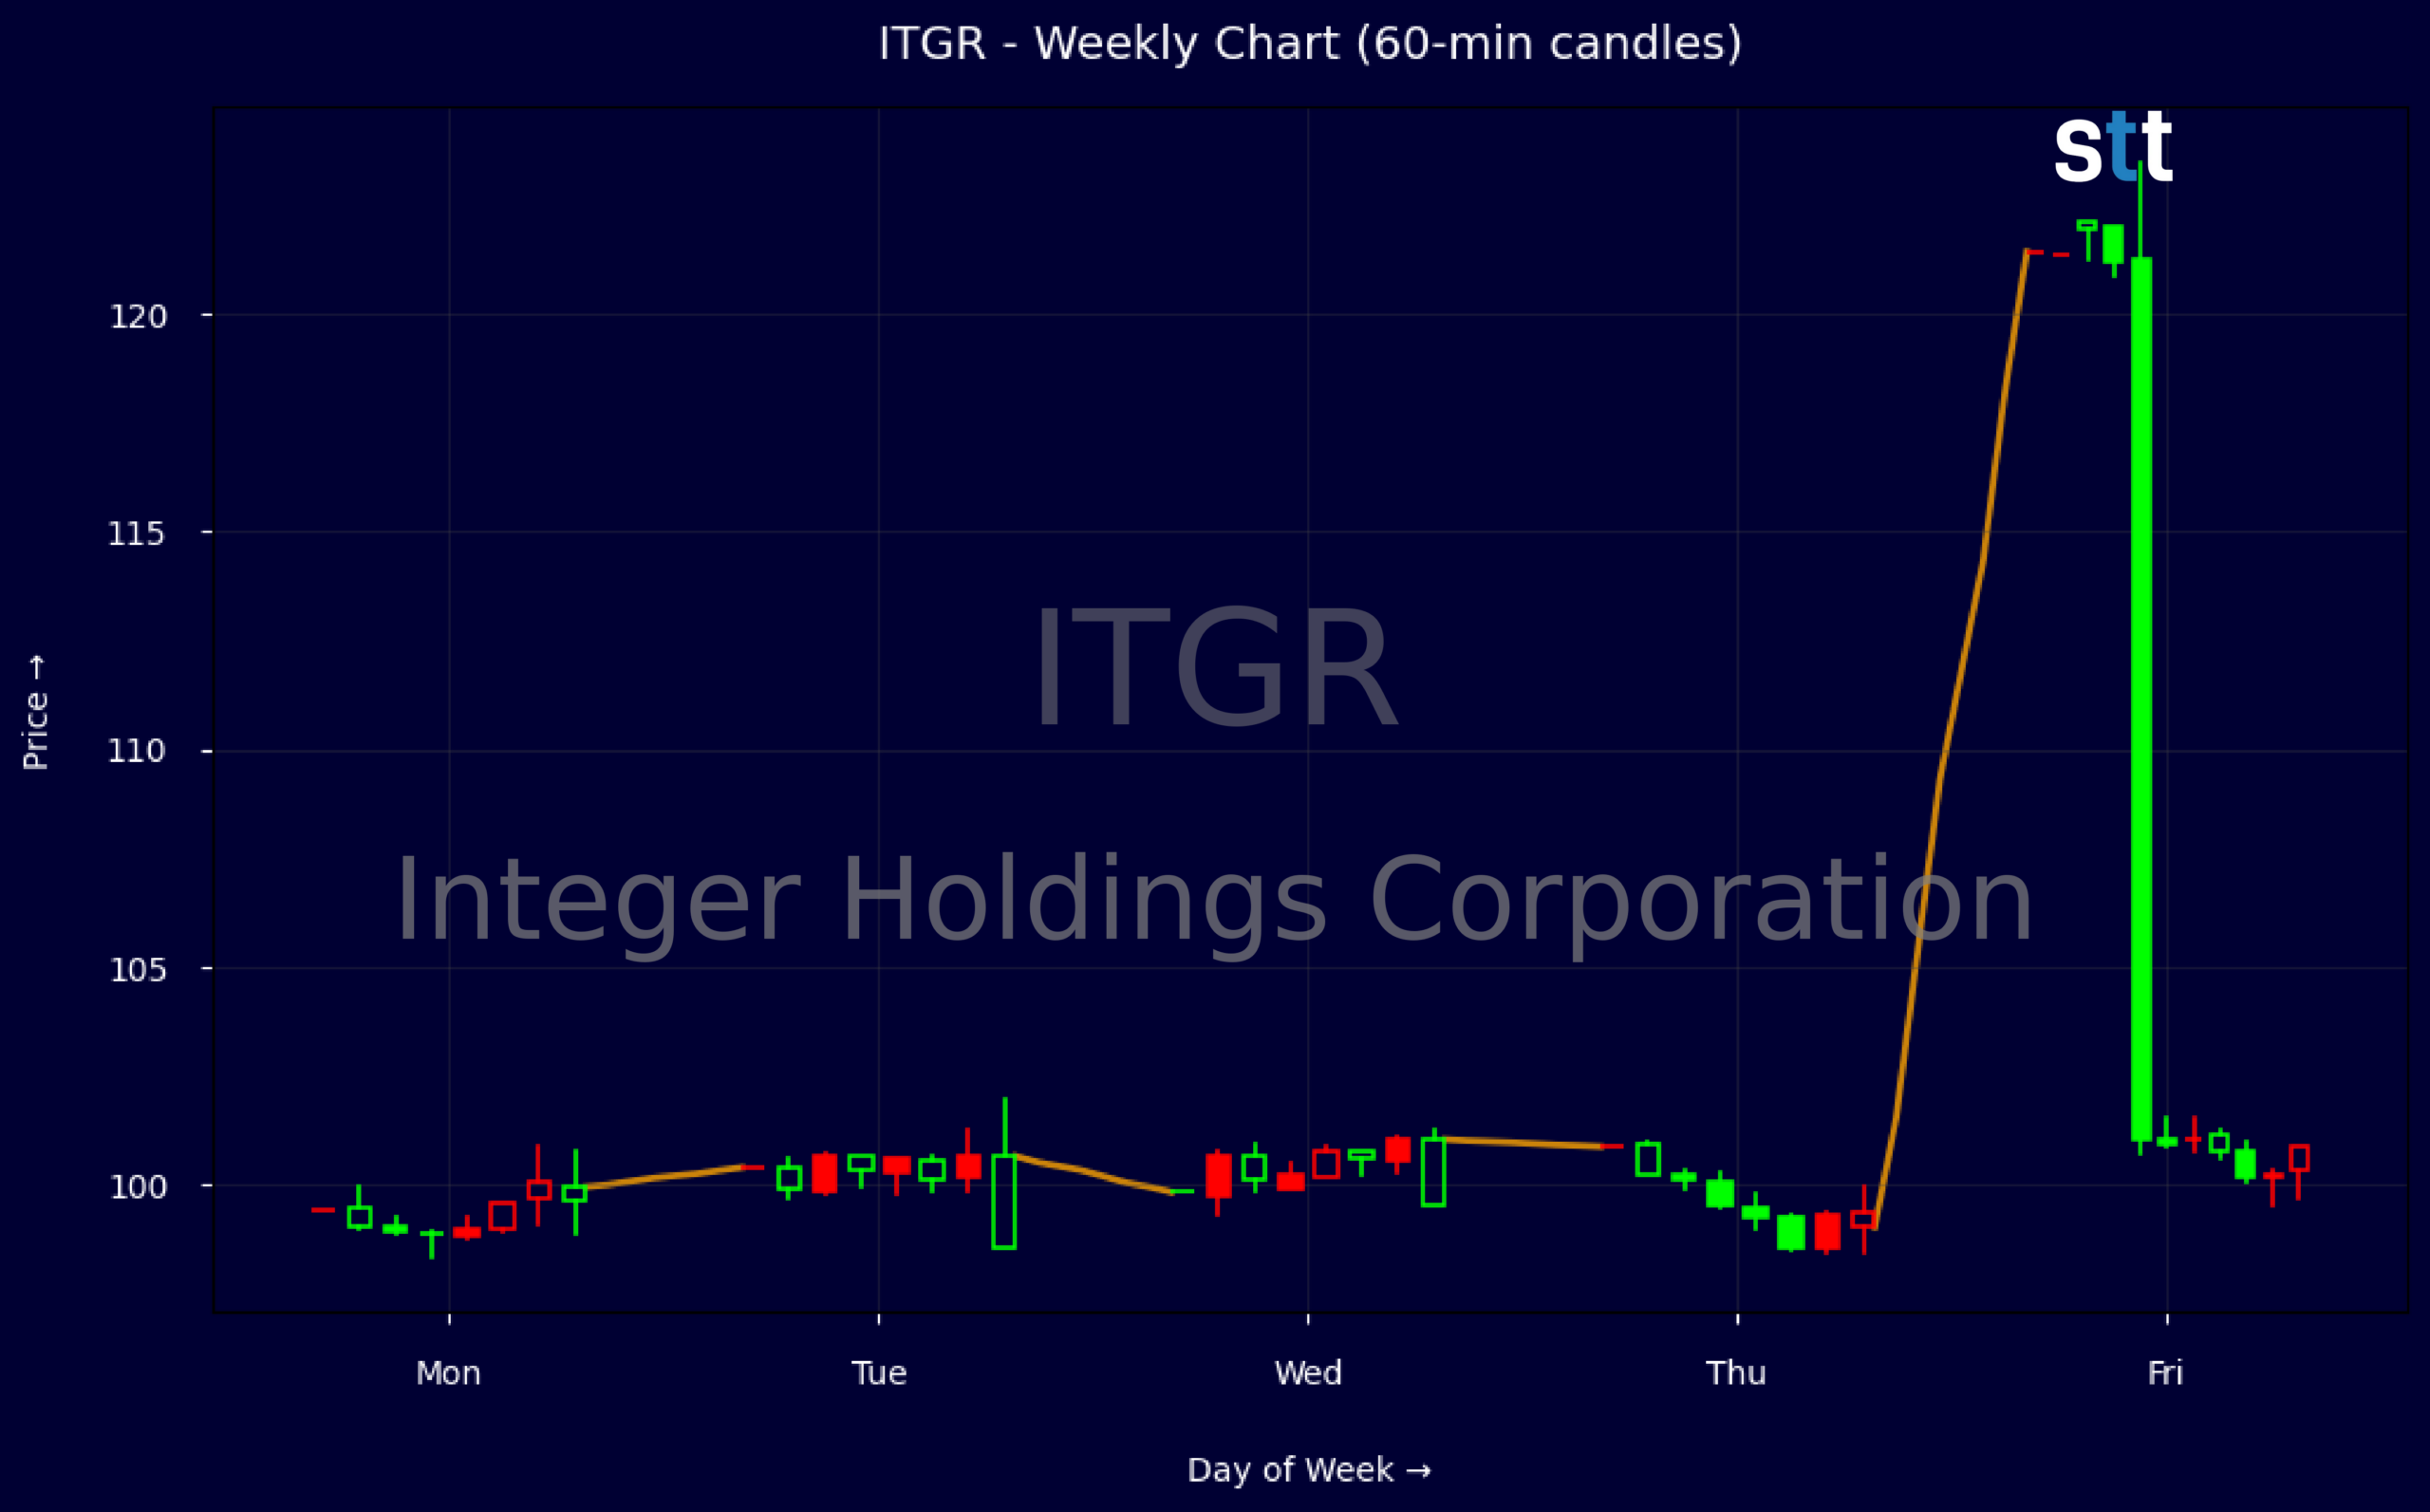
Weekly Update Jul 27 – Jul 31, 2026: On Saturday, August 01, 2026 Integer Holdings Corporation stock [NYSE: ITGR] is trending up by 20.4%! Discover the key drivers behind this movement as well as our expert analysis in the detailed breakdown below.
Healthcare industry expert:
Analyst sentiment – positive
Integer Holdings (ITGR) occupies a strong niche as a scaled medtech contract manufacturer with diversified OEM exposure and solid fundamentals. Revenue growth of 8.7%/12.4% over 3/5 years and gross margin of 26.4% underpin a durable franchise, though ROIC (≈4.8%) and ROE (≈8.6%) remain only mid‑tier for healthcare suppliers. Leverage is manageable (total debt/equity 0.81, interest coverage 8.4x, current ratio 3.8). Valuation is rich at ~35x earnings and ~1.9x book, implicitly pricing in sustained double‑digit growth and execution on capacity investments.
Technically, the tape has shifted from a tight consolidation around $99–101 to a sharp breakout, with the weekly bar spiking to ~$121.4 on buyout headlines. That gap and range expansion confirm a strong bullish trend, but the stock is now trading as a deal proxy, not on fundamentals. Liquidity ballooned on the news, and $120 now marks near‑term pivot resistance. Tactically, $100–102 is the key actionable support: above it, long with tight stops; a decisive break below signals waning confidence in the KKR transaction.
More Breaking News
- MEOH Stock Jumps As Earnings Beat Fuels Buyback Momentum
- MPT Stock Slides As Traders Focus On Debt And Cash Flow
- Regeneron Stock Jumps As Libtayo Data Fuels Bullish Targets
- AAL Stock Slides As Fuel Shock Slams 2026 Outlook
The KKR take‑private chatter at $127–172 per share now dominates the outlook and compresses traditional upside/downside. Versus healthcare and med‑equipment peers, ITGR offers superior top‑line growth and CDMO positioning but only average margins and returns, which the proposed deal effectively monetizes at a premium multiple. With Street targets clustered around $96–112, the reported $127 bid is the operative ceiling; expect the stock to trade in a $110–127 merger‑spread band, with $110 as firm downside support absent deal failure.
Quick Financial Overview
Integer Holdings Corporation is now trading as a deal story first, fundamentals second. The weekly tape shows a quiet grind around $99–$101 before an explosive gap, with the stock opening near $121 on 2026/07/31 after KKR buyout headlines. Intraday, price ripped from just under $101 to as high as $123.50 in a single session, then settled near $121, which is classic “gap, spike, and pin” behavior around a rumored take-private level.
For traders, that means ITGR is likely to trade in a tighter band between current levels and the indicated ~$127 deal price. The rumored takeout effectively caps upside while leaving a spread that merger-arb and event-driven traders will try to capture. Volume is not provided here, but the magnitude of the gap and +20% move confirms aggressive repricing, suggesting most fundamental re-rating from the news is already baked in.
Under the hood, Integer Holdings shows solid but not explosive fundamentals. Revenue runs near $1.85B with mid-20s gross margin and roughly 10.8% EBIT margin, producing a profit margin just above 7%. A P/E around 34.9 and price-to-sales near 1.85 tell you the stock was already valued as a quality medtech name before the bid. Balance sheet strength looks reasonable for a leveraged buyout: total debt-to-equity of 0.81, interest coverage of 8.4, and ample liquidity with a current ratio of 3.8. Returns on equity in the mid-to-high single digits leave room for private equity to push efficiency and margins higher.
Conclusion
This is stock news, not investment advice. StocksToTrade News delivers real-time stock market updates tailored to highlight the key catalysts driving short-term price movements. Our coverage is designed for active traders and investors who thrive in fast-moving markets, with a focus on volatile sectors like penny stocks, AI stocks, Robinhood stocks and other momentum plays. From earnings reports and FDA approvals to mergers, new contracts, and unusual trading volume, we break down the events that can spark significant price action.
Looking to level up your trading game? Explore StocksToTrade, the ultimate platform for traders. With powerful tools designed for swing and day trading, integrated news scanning, and even social media monitoring, StocksToTrade keeps you one step ahead.
Check out our quick startup guide for new traders!
- How to Read Stock Charts: A Guide for Beginners
- Trading Plan: 6 Steps to Create One
- How To Create a Stock Watchlist
Ready to build your watchlists? Check out these curated lists:
Once your watchlist is set, take the next step and trade with confidence using StocksToTrade’s robust platform. Don’t miss out — grab your 14-day trial for just $7 and experience the edge you need to thrive in today’s fast-paced markets.