
ICON plc stocks have been trading up by 16.39 percent amid optimism over strengthened clinical research demand and contract wins.
Key Takeaways
- Q3 2026 results showed softer year-on-year revenue and profit, but ICON plc delivered very strong bookings, record backlog, robust free cash flow, and aggressive share repurchases.
- For Q3, ICON posted revenue of $2.02B and adjusted EPS of $2.66, both slightly above FactSet consensus estimates of $2.01B and $2.62.
- Management raised 2026 revenue guidance to $8.10–$8.20B and tightened adjusted EPS guidance to $10.35–$10.65, modestly above Street consensus at the high end.
- ICON highlighted strong customer uptake of its AI-enabled digital platform and returned about $400M via buybacks in the quarter.
- Bank of America upgraded ICON to Neutral from Underperform and raised its price target to $185, while RBC reiterated an Outperform rating citing a strong order backlog and industry-leading book-to-bill, even as UBS shifted to a more cautious Neutral stance.
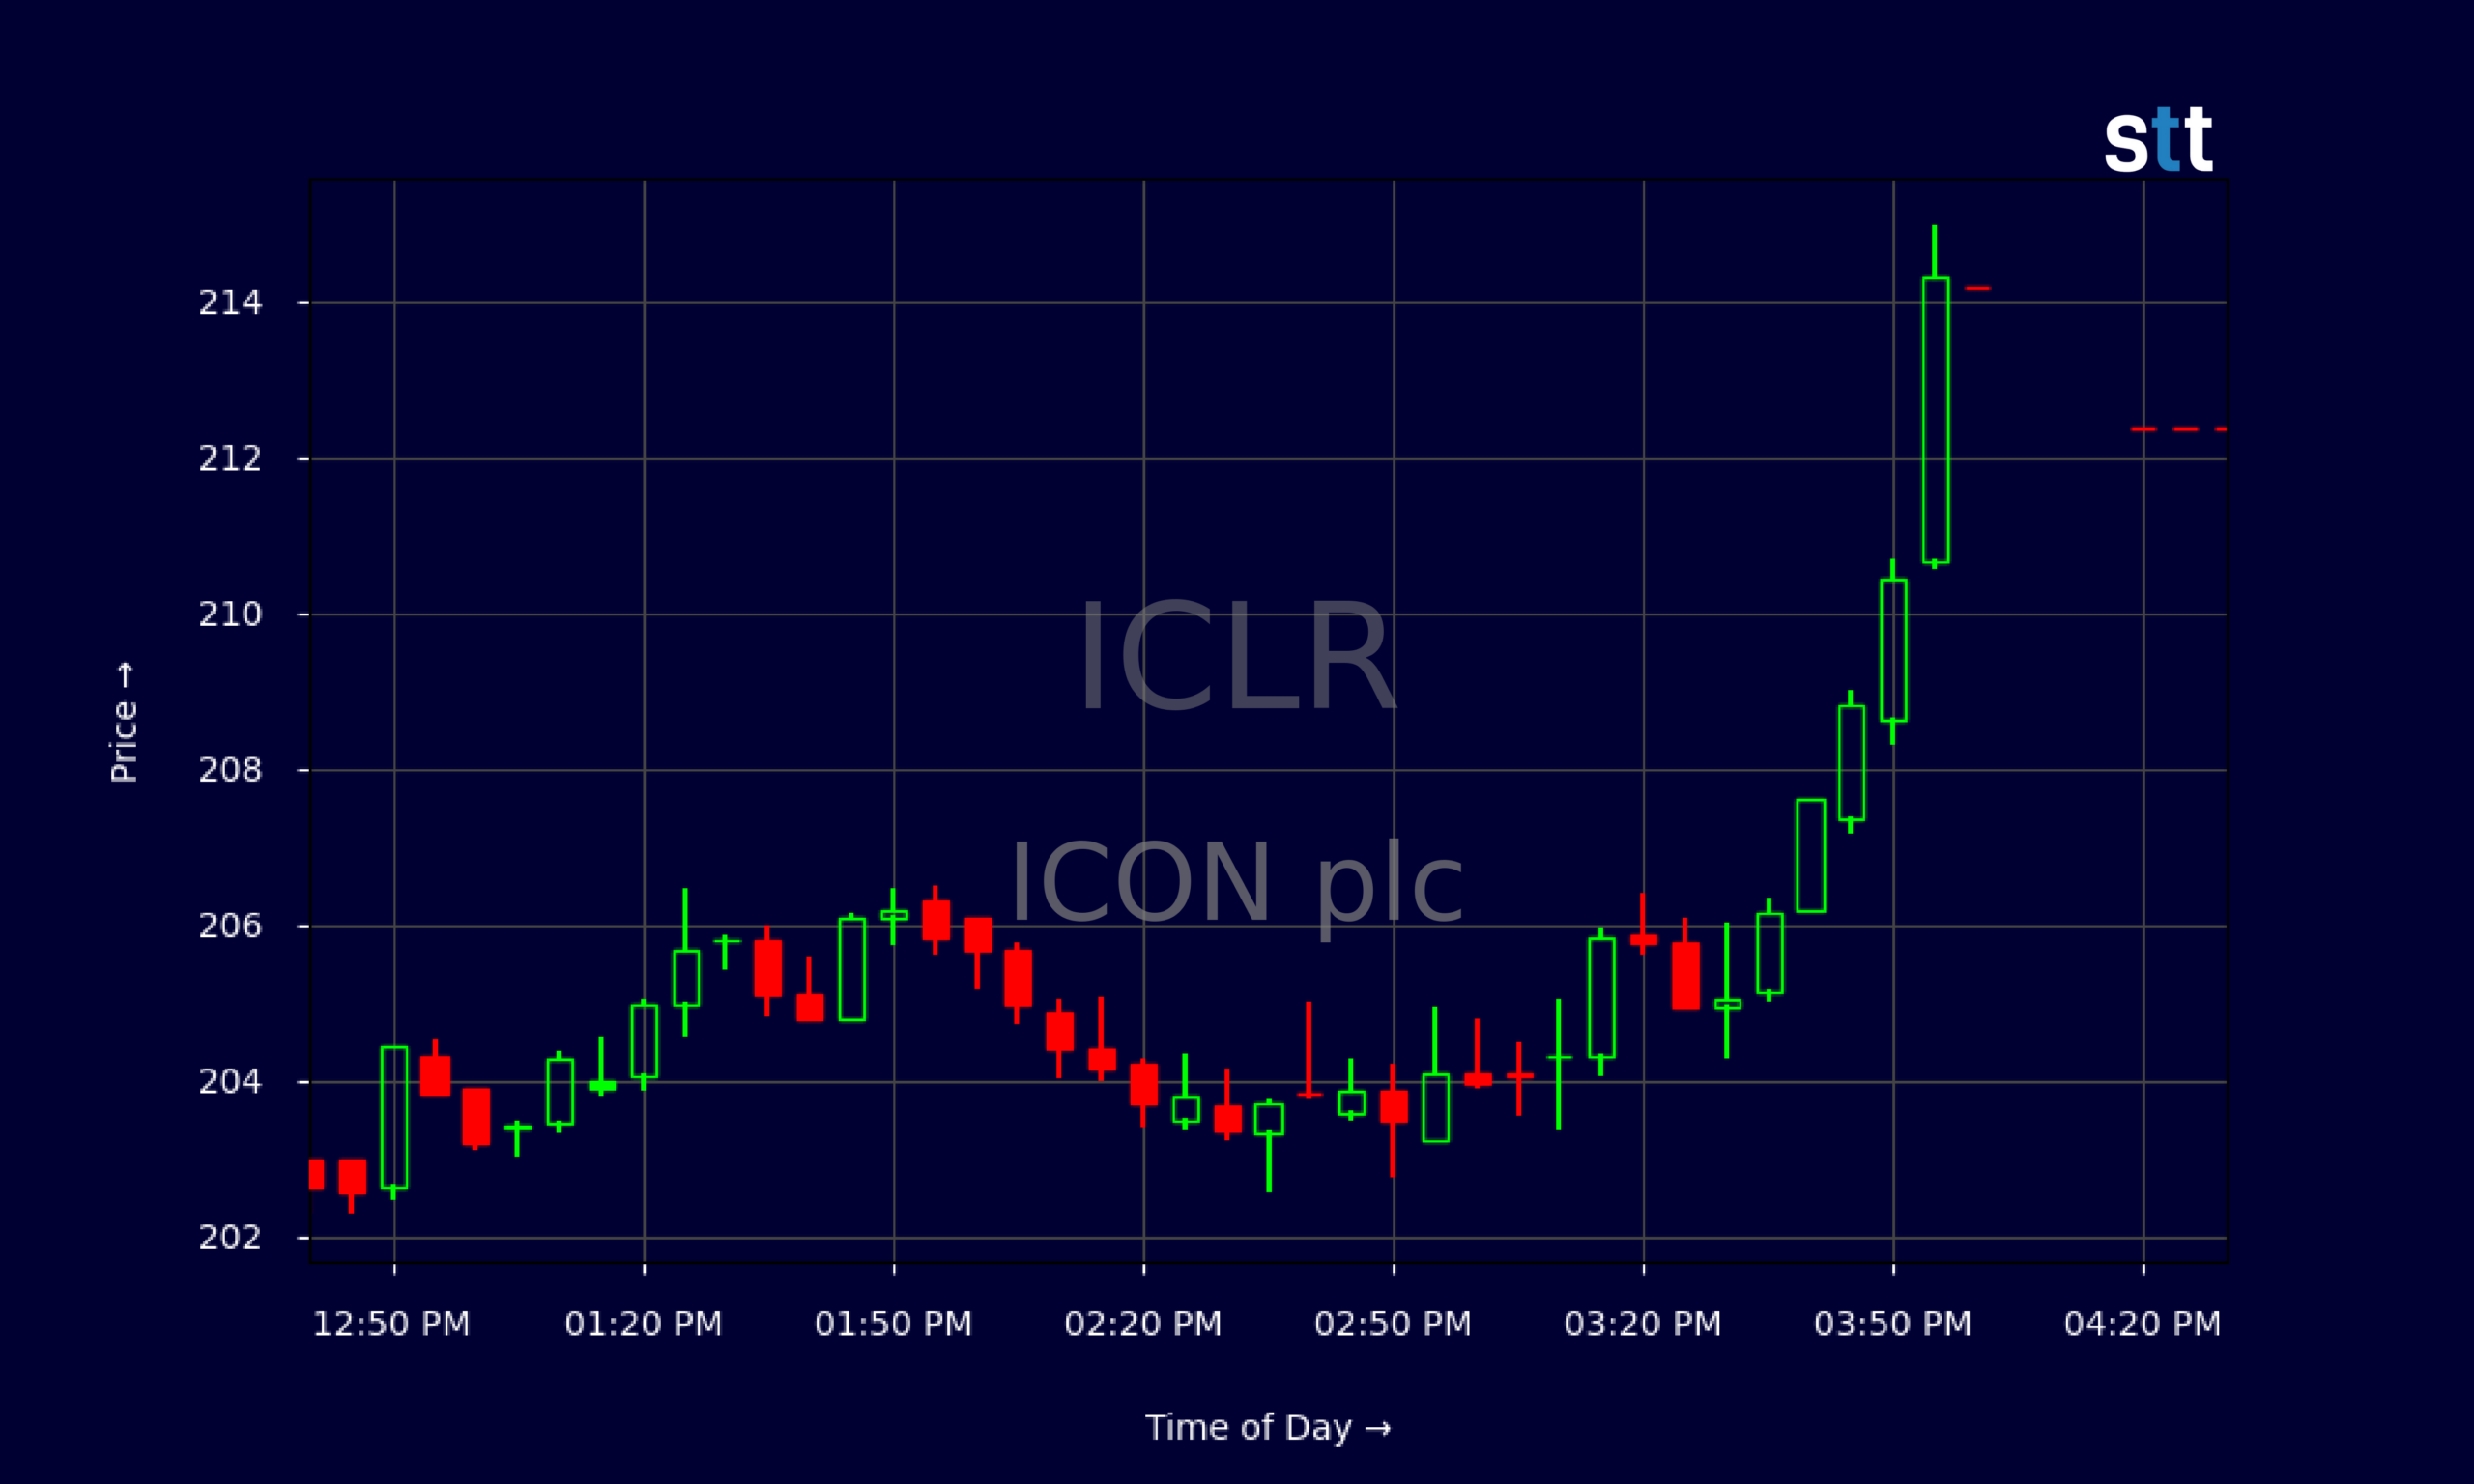
Live Update At 16:46:45 EDT: On Wednesday, October 28, 2026 ICON plc stock [NASDAQ: ICLR] is trending up by 16.39%! Discover the key drivers behind this movement as well as our expert analysis in the detailed breakdown below.
Quick Financial Overview
ICLR has flipped the switch over the last two weeks. The stock climbed from roughly $161 in early October 2026 to about $214 on 2026/10/28, a powerful trend move that active traders watch closely. The most explosive day came on 2026/10/28, when ICLR gapped from around $199 and ripped to an intraday high near $215, holding most of the gains into the close. That follow‑through after earnings is key.
Under the hood, ICON plc is not a cheap stock. A price‑to‑earnings ratio near 56.6 and price‑to‑sales around 1.5 signal that traders are already paying up for growth. With revenue of about $8.25B and pretax margins under 5%, ICLR is still a scaling story, not a fat‑margin cash cow. The balance sheet carries roughly $2.87B of long‑term debt but sits on more than $647M in cash, with leverage about 1.8 times equity, manageable for a global CRO.
More Breaking News
- INTR Stock Plunges As Brazil Fintech Selloff Deepens
- DMC Global Jumps 37% After Earnings Beat
- Quad Graphics Inc Falls 12% After Third-Quarter Results
- OceanFirst Financial Jumps 6% After Earnings Beat
For short‑term traders, that combination — rich valuation, strong uptrend, better‑than‑feared earnings — often creates sharp, sentiment‑driven moves. ICLR is acting like a momentum name again, so risk management and discipline matter more than ever.
Why Traders Are Watching ICLR Momentum
The latest ICLR earnings report is the classic “bad headline, good details” setup that experienced traders love. ICON plc showed year‑on‑year declines in non‑GAAP EPS and revenue, yet still beat FactSet consensus by a hair: Q3 revenue came in at $2.02B versus $2.01B expected, adjusted EPS at $2.66 versus $2.62. Expectations were low. Execution was slightly better. That was enough to push ICLR up roughly 4.4% after hours.
What is really lighting up trader screens is the forward view. ICON plc raised 2026 revenue guidance to $8.10–$8.20B and tightened adjusted EPS guidance to $10.35–$10.65, bracketing and edging past Street numbers at the high end. That tells traders management sees the current softness as temporary, with demand returning through a record backlog and an industry‑leading book‑to‑bill.
ICLR is also leaning into its AI‑enabled digital platform, which management says is seeing strong customer uptake. In a CRO space where speed and data quality win contracts, that narrative matters. On top of that, ICON plc returned about $400M via buybacks, on track with the large‑scale repurchase story and signaling confidence in its own stock.
Analysts are shifting too. Bank of America moved ICON plc up to Neutral from Underperform, raising its target to $185 as CRO demand stabilizes. RBC kept an Outperform rating, pointing to backlog strength and at least mid‑single‑digit growth by 2027. UBS is more cautious, cutting from Buy to Neutral, and warning that client‑specific issues may weigh on bookings and margins. For traders, that mix — improving but not euphoric sentiment — often leaves room for further re‑rating if ICLR keeps delivering.
Conclusion
For active traders, ICLR now sits at the crossroads of momentum and fundamentals. ICON plc still faces year‑on‑year earnings pressure and margins below some peers, but the company is offsetting that with strong bookings, a record backlog, and raised guidance that leans above consensus. The 2026 EPS range of $10.35–$10.65 and revenue guide of $8.10–$8.20B say management believes the pipeline will convert.
The chart confirms that message. ICLR has broken out from the mid‑$160s to above $210 in a straight, high‑volume move, with intraday dips getting bought quickly. That kind of behaviour often reflects funds and shorter‑term traders alike re‑positioning after a “better than feared” earnings print. Still, a P/E above 50 means ICON plc has no room for execution errors; any stumble in bookings, AI platform adoption, or margin progress can trigger sharp pullbacks.
This is where the Tim Sykes playbook kicks in — study the catalysts, respect the trend, but never marry a stock. As Tim Bohen, lead trainer with StocksToTrade says, “Success in trading is more about cutting losses quickly than finding winners.” That dovetails with Tim’s core message: as Tim likes to say, “I don’t trade stories, I trade the price action — and I always cut losses quickly, no matter how good the story sounds.” For ICLR, the story and the tape are finally moving in the same direction. Traders just need to stay nimble and let the price action, not the hype, lead their decisions.
This is stock news, not investment advice. StocksToTrade News delivers real-time stock market updates tailored to highlight the key catalysts driving short-term price movements. Our coverage is designed for active traders and investors who thrive in fast-moving markets, with a focus on volatile sectors like penny stocks, AI stocks, Robinhood stocks and other momentum plays. From earnings reports and FDA approvals to mergers, new contracts, and unusual trading volume, we break down the events that can spark significant price action.
Looking to level up your trading game? Explore StocksToTrade, the ultimate platform for traders. With powerful tools designed for swing and day trading, integrated news scanning, and even social media monitoring, StocksToTrade keeps you one step ahead.
Check out our quick startup guide for new traders!
- How to Read Stock Charts: A Guide for Beginners
- Trading Plan: 6 Steps to Create One
- How To Create a Stock Watchlist
Ready to build your watchlists? Check out these curated lists:
Once your watchlist is set, take the next step and trade with confidence using StocksToTrade’s robust platform. Don’t miss out — grab your 14-day trial for just $7 and experience the edge you need to thrive in today’s fast-paced markets.