
Grab Holdings Limited stocks have been trading up by 10.45 percent after strong regional growth and profitability-focused expansion news.
Key Takeaways
- Q3 revenue for Grab Holdings hit $1.11B, topping estimates around $1.05B–$1.10B and confirming solid demand across its platform.
- Adjusted EBITDA jumped to $237M from $136M year over year, showing GRAB is tightening costs even with high fuel prices and macro pressure.
- The company reported breakeven adjusted EPS versus a $0.05 profit forecast but still nudged 2026 revenue guidance higher, and the stock gained about 1.8% after hours.
- Barclays and JPMorgan trimmed GRAB price targets to $4 and $4.80, yet both kept Overweight ratings, while the Street’s average target near $6.04 signals room above current prices.
- GRAB is pushing expansion via a planned $1.49B purchase of 60% of Advance Intelligence’s digital financial services platform, while its $600M Foodpanda Taiwan deal was blocked by regulators.
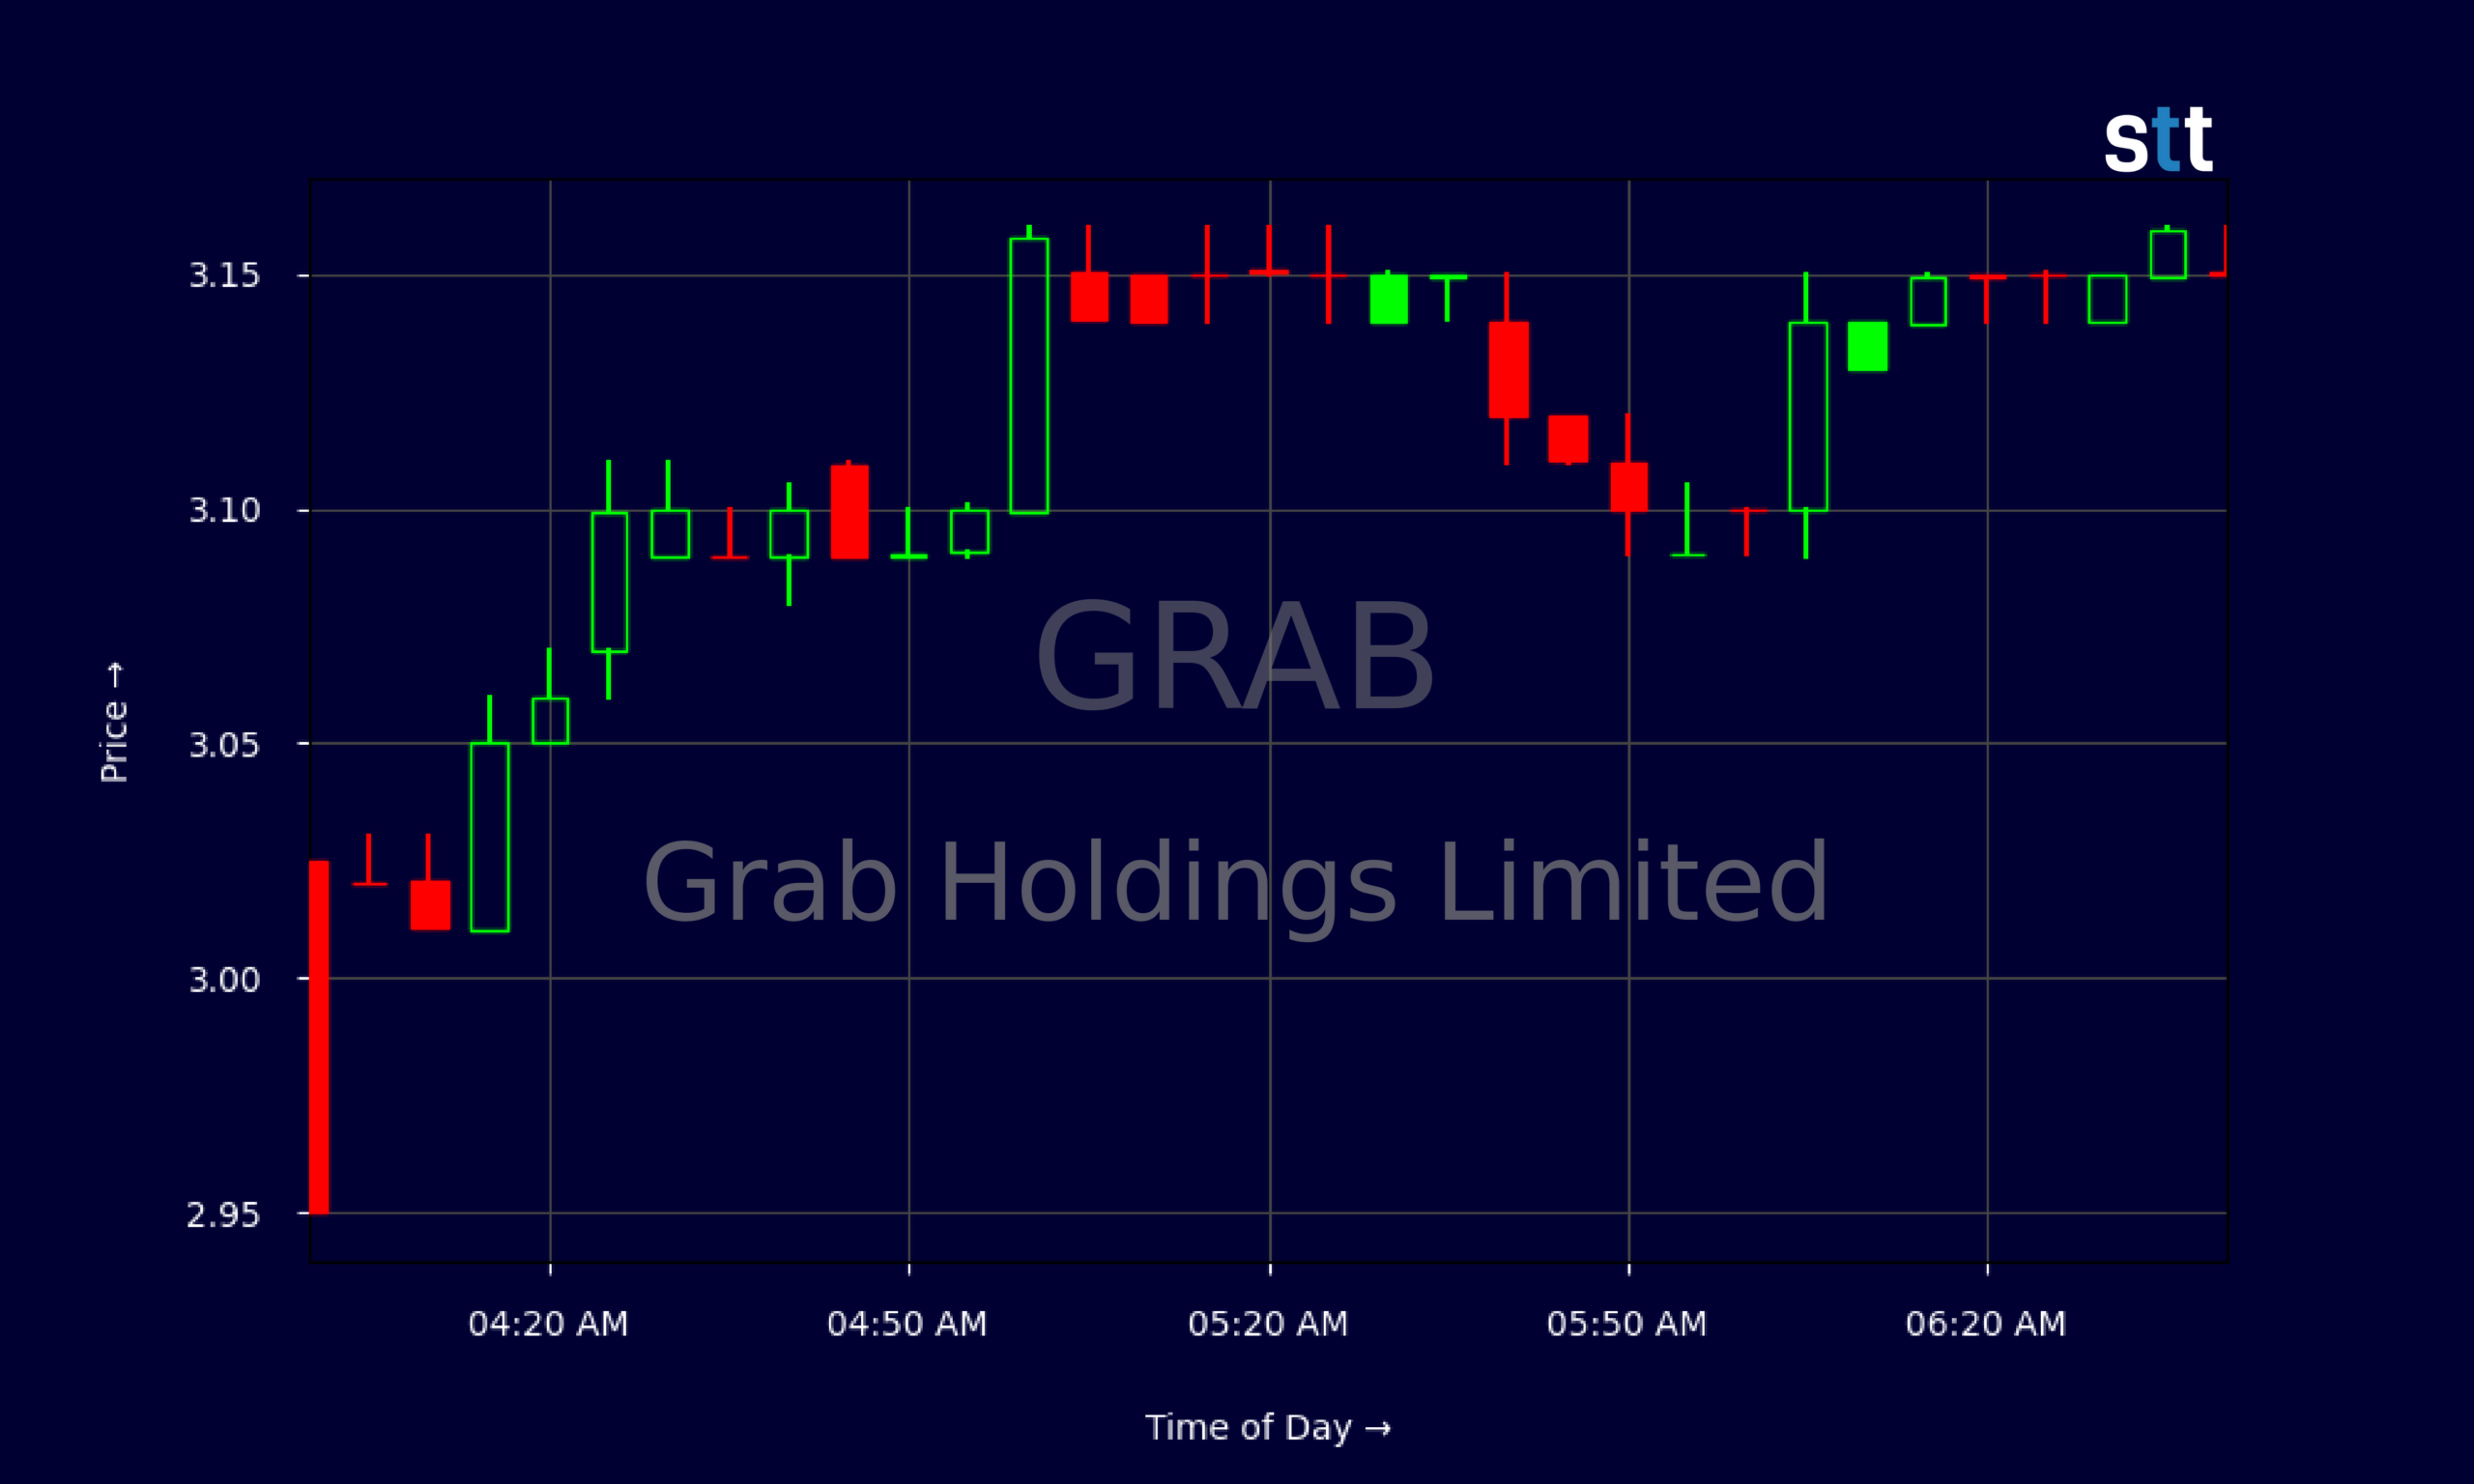
Live Update At 06:47:03 EST: On Tuesday, November 03, 2026 Grab Holdings Limited stock [NASDAQ: GRAB] is trending up by 10.45%! Discover the key drivers behind this movement as well as our expert analysis in the detailed breakdown below.
Quick Financial Overview
GRAB just printed the kind of quarter active traders like to see. The company reported Q3 revenue of $1.11B, ahead of FactSet’s $1.05B consensus and slightly above prior expectations near $1.10B. That tells you demand across Grab Holdings’ ride‑hailing, delivery, and financial services ecosystem is still strong despite choppy macro conditions.
The more eye‑catching number is profitability. Adjusted EBITDA surged to $237M from $136M a year earlier. For traders, that jump signals GRAB is scaling its platform and managing incentives, discounts, and overhead far more efficiently than before.
On the flip side, adjusted EPS came in around breakeven instead of the $0.05 profit analysts modeled. The market shrugged that off, sending GRAB up roughly 1.8% in after‑hours trading as the company slightly raised its 2026 revenue guidance to a range that brackets consensus. That reaction shows traders are zeroed in on long‑term revenue and margin trajectory, not a one‑quarter EPS miss.
More Breaking News
- FTCI Stock Pops As Credit Relief Meets Solar Tech Tailwind
- Duolingo Stock Jumps As Q3 Growth Tops Expectations
- AAL Stock Steadies As Loyalty Engine And Revenue Beat Draw Trader Focus
- BBD Stock Jumps As Analyst Upgrades And Buyback Fuel Momentum
Technically, GRAB has pulled back from the low $3s to the high $2s over recent weeks, but Q3 numbers now give the bulls fresh ammunition.
Why Traders Are Watching GRAB After Q3 Earnings
GRAB has been grinding in a tight band on the daily chart. From 2026/10/09 to 2026/11/02, the stock slipped from about $3.19 to a close of $2.86, with a series of lower highs around $3.20, $3.15, and then the $2.90s. That slow fade set up a classic “show me” moment into earnings. Q3 results did just that.
Fundamentally, Grab Holdings posted a clean revenue beat and a powerful adjusted EBITDA ramp, even while dealing with high fuel costs and macro headwinds across Southeast Asia. When a platform business like GRAB grows the top line and expands profitability at the same time, traders lean in. The slight 1.8% after‑hours move understates the real story: earnings reinforced the longer‑term bull case.
Analyst action tells a similar tale. Barclays cut its GRAB price target from $5 to $4, and JPMorgan trimmed from $5.90 to $4.80. In a vacuum, target cuts sound bearish. But both banks kept Overweight ratings and explicitly tied the lower numbers to cooler sector valuations, not a collapse in Grab Holdings’ fundamentals. Meanwhile, the broader analyst crowd still pegs GRAB with a Buy‑level stance and an average target around $6.04, well above the $2–$3 zone where the stock is trading.
On the strategic side, GRAB is not standing still. Management is broadening the ecosystem with a planned $1.49B purchase of 60% of Advance Intelligence’s digital financial services platform, aiming to deepen its fintech cross‑sell across the super‑app. At the same time, the $600M Foodpanda Taiwan acquisition was blocked by Taiwan’s Fair Trade Commission. That setback limits expansion in Taiwan but also frees capital to refocus on GRAB’s core Southeast Asian roadmap, where user growth and on‑demand gross merchandise value remain robust.
For short‑term traders, this mix of improving numbers, supportive Street sentiment, and a clear growth strategy keeps GRAB firmly on the watchlist.
Conclusion
GRAB now sits at an interesting crossroads. The stock has retreated from above $3 to the mid‑$2s, even as Grab Holdings delivers revenue upside, stronger adjusted EBITDA, and a slightly higher long‑term revenue guide. Valuation ratios show a still‑rich growth profile, but the balance sheet carries sizable cash of roughly $6.8B against total liabilities near $5.23B, giving GRAB room to keep funding expansion and absorbing shocks.
The intraday tape around $3 shows steady liquidity and relatively tight five‑minute ranges, which active traders can use for scalps around news and key levels. With price targets from Barclays and JPMorgan reset but still bullish, and a Street average near $6.04, there is a clear disconnect between where GRAB trades today and where many professionals model it over the medium term. That gap is where volatility — and trading opportunity — often lives.
Traders still need to respect the risks. Regulatory pushback, like the Foodpanda Taiwan rejection, reminds everyone that cross‑border deals can break late. EPS was also a touch soft versus expectations, which can cap near‑term enthusiasm if growth wobbles. In this context, risk management has to stay front and center; as Tim Bohen, lead trainer with StocksToTrade says, “For me, trading is more about managing risk than finding the next big mover.”
But as Tim Sykes likes to say, “Patterns repeat, but traders who prepare are the ones who profit.” For GRAB, the current pattern is clear: improving fundamentals, cautious but positive Street views, and a stock that has lagged the narrative. For educational and research‑focused traders, GRAB remains a name to study closely, plan around, and trade with strict risk rules — not to blindly hold and hope.
This is stock news, not investment advice. StocksToTrade News delivers real-time stock market updates tailored to highlight the key catalysts driving short-term price movements. Our coverage is designed for active traders and investors who thrive in fast-moving markets, with a focus on volatile sectors like penny stocks, AI stocks, Robinhood stocks and other momentum plays. From earnings reports and FDA approvals to mergers, new contracts, and unusual trading volume, we break down the events that can spark significant price action.
Looking to level up your trading game? Explore StocksToTrade, the ultimate platform for traders. With powerful tools designed for swing and day trading, integrated news scanning, and even social media monitoring, StocksToTrade keeps you one step ahead.
Check out our quick startup guide for new traders!
- How to Read Stock Charts: A Guide for Beginners
- Trading Plan: 6 Steps to Create One
- How To Create a Stock Watchlist
Ready to build your watchlists? Check out these curated lists:
Once your watchlist is set, take the next step and trade with confidence using StocksToTrade’s robust platform. Don’t miss out — grab your 14-day trial for just $7 and experience the edge you need to thrive in today’s fast-paced markets.