
Global Payments Inc. stocks have been trading up by 10.75 percent after strong earnings and optimistic digital-payments guidance.
Key Takeaways For GPN Traders
- Oppenheimer upgraded Global Payments to Outperform with a $115 target, leaning on derisked 2026 earnings, 2027 free cash flow acceleration, and Worldpay synergies.
- Bank of America reinstated coverage at Buy with a $114 target, seeing roughly $600M in Worldpay-related synergies and an attractive deal valuation.
- KeyBanc shifted to Overweight with a $105 target, highlighting attractive risk/reward, improving organic growth into FY27, and capital return potential.
- Truist trimmed its target to $86 but kept a Hold rating, flagging European softness and higher rates as key near-term risks.
- Global Payments will post Q3 2026 results on 2026/11/05, with a webcast that could be the next major catalyst.
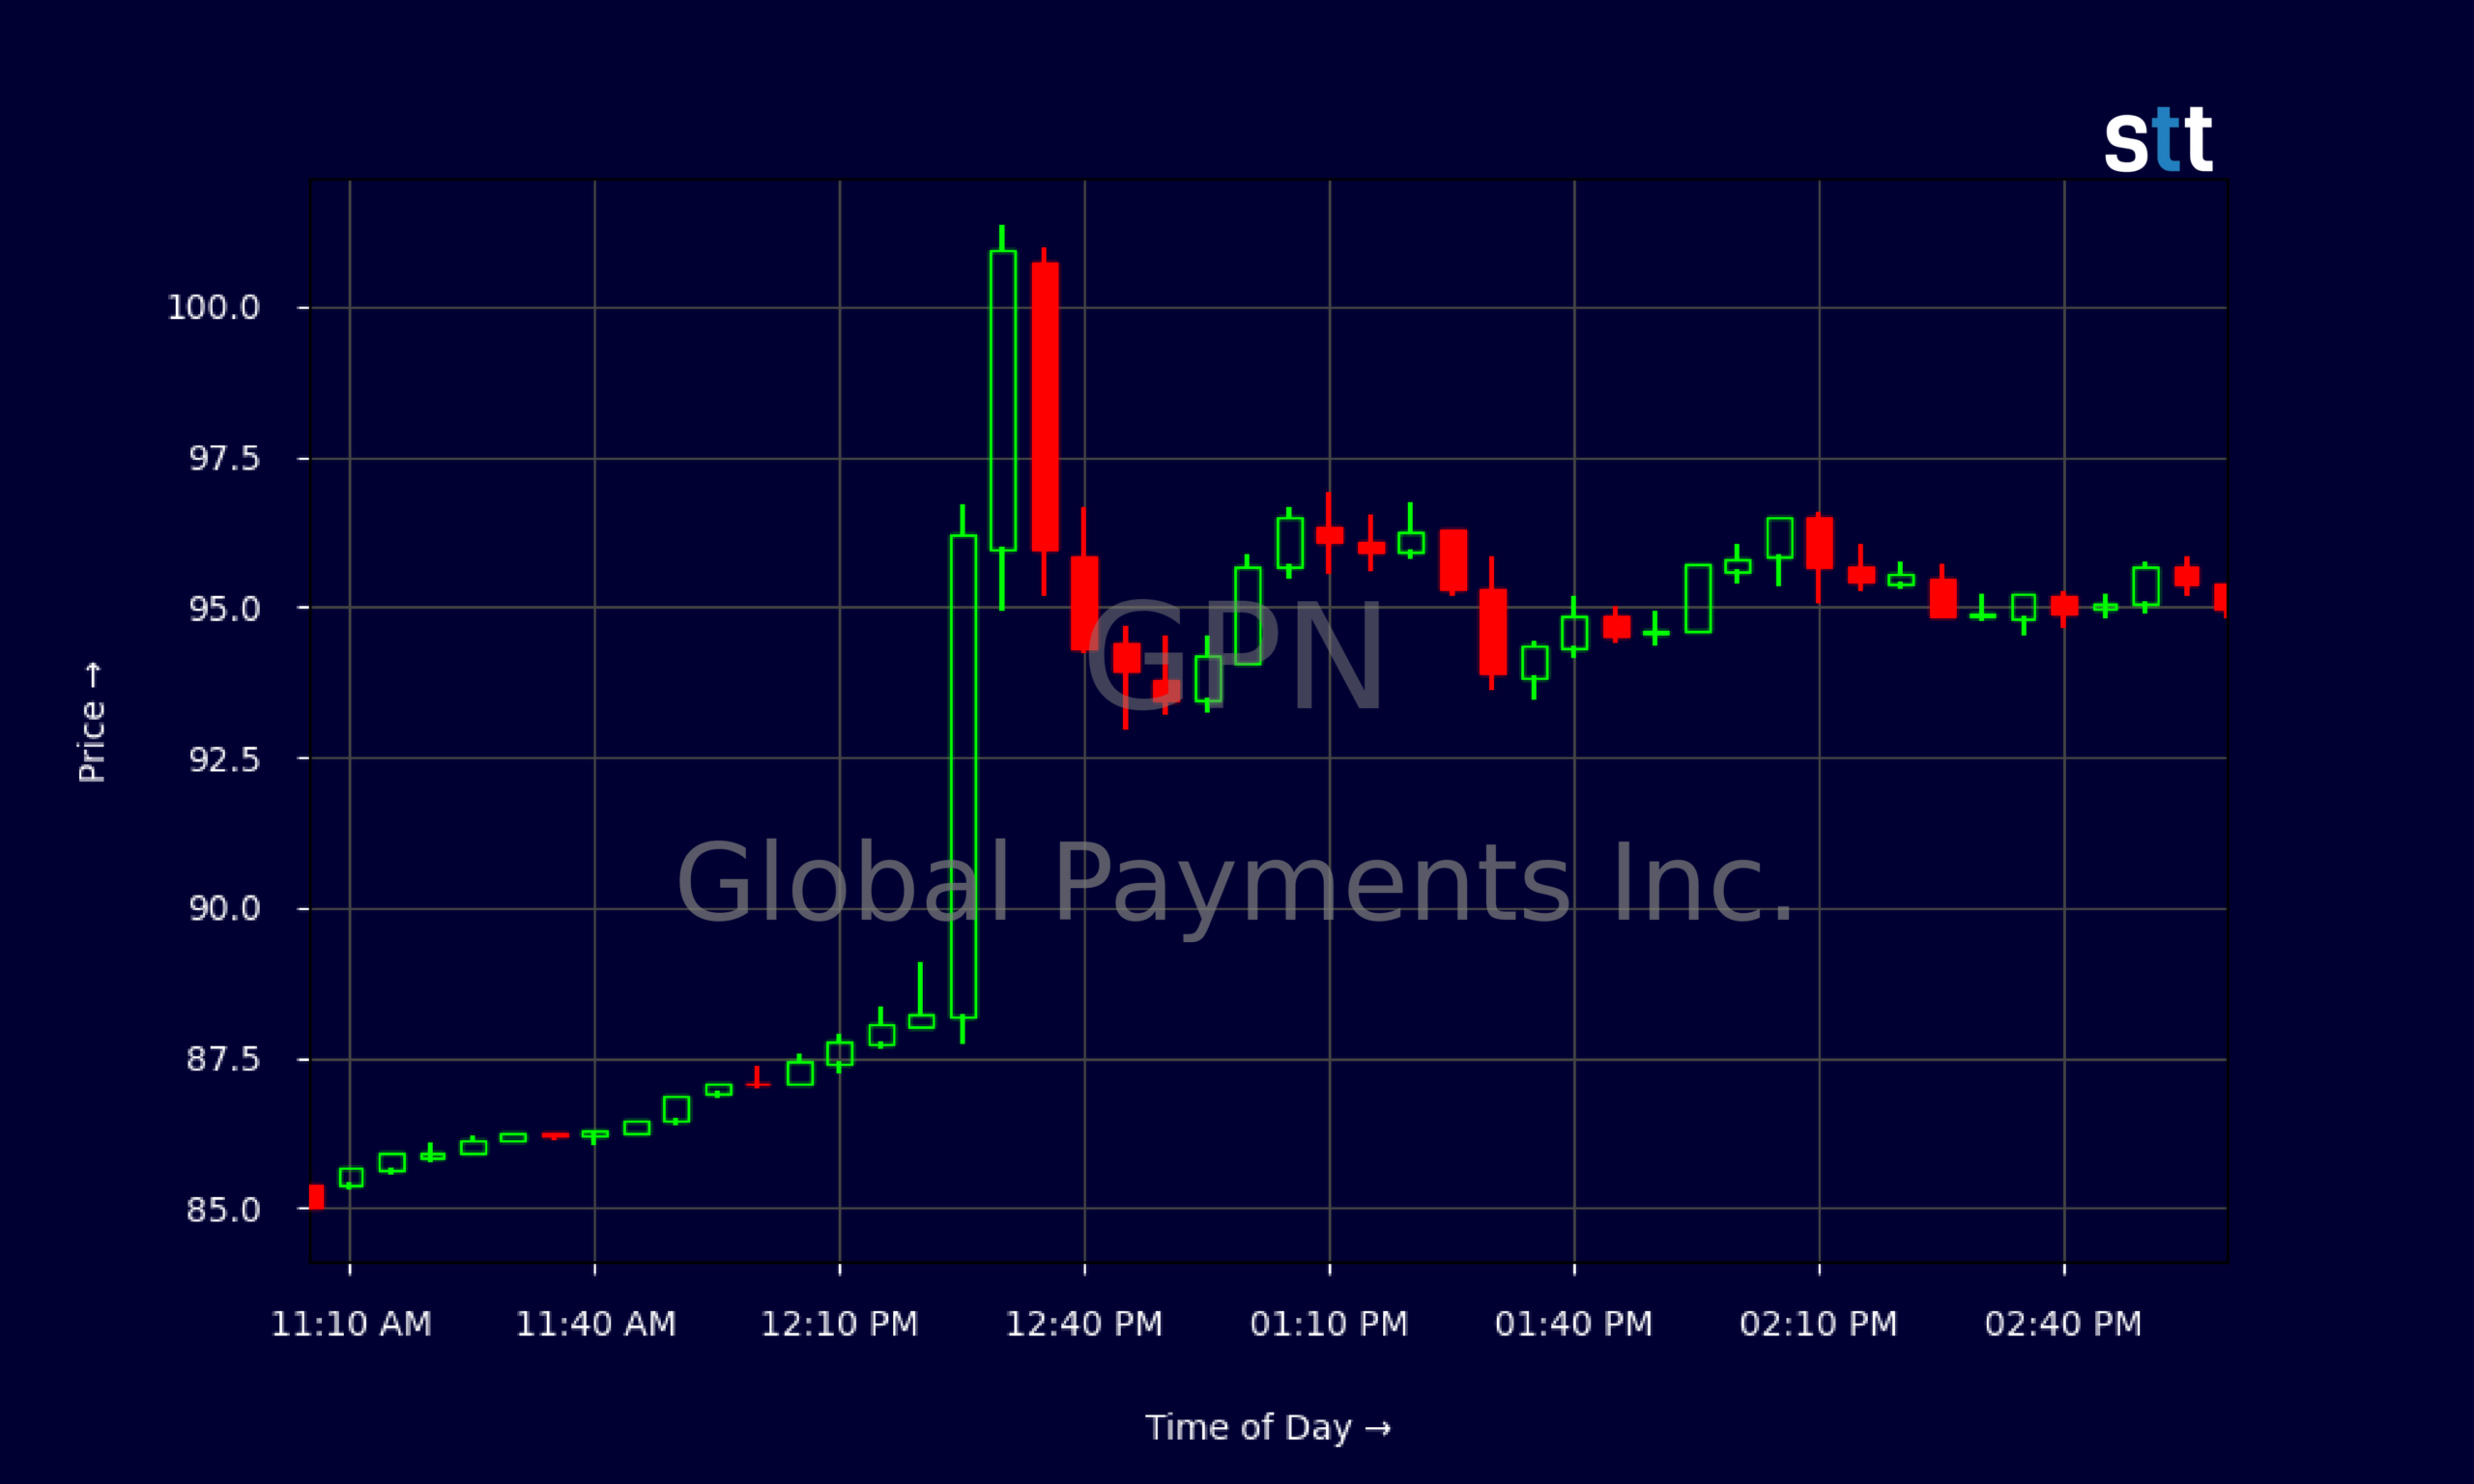
Live Update At 15:03:24 EDT: On Friday, October 30, 2026 Global Payments Inc. stock [NYSE: GPN] is trending up by 10.75%! Discover the key drivers behind this movement as well as our expert analysis in the detailed breakdown below.
Quick Financial Overview
GPN has been grinding higher on the chart, and the numbers back up why traders are paying attention. Over the last few weeks, Global Payments has run from the high $70s to a recent close near $94.98, a strong breakout from the prior $80–$85 range. That’s momentum you cannot ignore in active trading.
Intraday, GPN showed classic trend-day action. The stock opened around $86, dipped briefly, then exploded midday, topping out above $101 before settling just under $95. That kind of $15 intraday range screams day-trader playground. Late in the session, the 5‑minute candles held higher lows, showing dip buyers stepping in aggressively.
Fundamentally, Global Payments is a cash machine despite messy GAAP earnings from discontinued operations. Revenue sits around $7.7B annually with a fat 93% gross margin and EBITDA margin above 30%. Operating cash flow of about $662.6M and free cash flow near $426.9M for the latest quarter show why analysts lean on a price-to-free-cash multiple near 12.7x.
More Breaking News
- GoDaddy Stock Jumps As Q3 Beat And AI Airo Fuel Bullish Outlook
- AAL Stock Slides As Fuel Shock Slams 2026 Outlook
- Micron Stock Slides As China’s CXMT DRAM Threat Rattles Traders
- NVDA Stock Rebounds As Traders Weigh Trump Sale News
Debt is real — long-term borrowings are roughly $21.5B — but interest coverage near 22x suggests GPN is handling it. Book value per share around $87.34 versus a share price in the mid‑$90s puts the price-to-book just under 1x, signaling the market still prices this like a value story, not a high-flyer.
Why Traders Are Watching GPN Into Q3 Earnings
This whole Global Payments story right now is about rerating potential versus macro fear. On one side, you have a wall of bullish analyst calls. On the other, you have Europe and rates hanging over the tape. Traders in GPN are basically betting on which story dominates into and after the 2026/11/05 Q3 earnings print.
Oppenheimer fired the starting gun by upgrading GPN to Outperform with a $115 target. The thesis is clear: 2026 earnings look derisked, 2027 free cash flow should accelerate as one-time costs fade and operating leverage kicks in, and Worldpay synergies plus capital returns add upside optionality. For momentum traders, that’s a clean multi‑year narrative — earnings visibility plus FCF ramp.
Bank of America reinforced the bull case by restarting coverage at Buy with a $114 target on Global Payments, leaning into the Worldpay acquisition. They’re modeling roughly $600M in cost and revenue synergies, which is real money in a payments processor. If management delivers even close to that, current pricing looks too cheap relative to those targets.
KeyBanc joined in with an upgrade to Overweight and a $105 target, calling the risk/reward attractive and seeing organic growth improvement into FY27. That matters because it says GPN is not just a synergy story; the core engine is expected to slowly rev higher too.
Even more telling, consensus data from Autonomous Research and FactSet show Global Payments holding an overweight bias with a mean target around $104–$104.28 when the shares were near $82. Goldman Sachs nudged its target up to $98, and the broad Street still clusters above $100. That’s a sizable implied upside gap if the Q3 call and 2027 outlook confirm the narrative.
Balancing all of this is Truist, which trimmed its target to $86 and stuck with Hold, warning about European consumer softness and higher rates. For short-biased or cautious traders, that note is the reminder not to blindly chase.
Conclusion
For active traders, GPN is lining up as a classic “catalyst plus rerating” setup. The stock has already broken out from the low‑$80s to the mid‑$90s, powered by a wave of upgrades on Global Payments and higher price targets clustered between $98 and $115. Under the hood, strong gross margins, solid free cash flow, and leverage that looks manageable give the bull camp plenty to work with.
But the real test comes on 2026/11/05, when Global Payments releases Q3 2026 numbers and hosts its webcast. That event will tell traders whether Worldpay synergies are tracking toward the roughly $600M banks are modeling, whether free cash flow is moving toward that 2027 acceleration story, and how much macro drag Europe and higher rates are actually creating. If the call backs up the Oppenheimer, Bank of America, KeyBanc, and Goldman narratives, GPN has room to keep grinding toward consensus targets.
If the numbers disappoint or guidance underwhelms, that gap between the current Global Payments price and Street targets can close the other way — fast. That’s why risk management matters here. As Tim Sykes likes to remind traders, “The market doesn’t care about your opinions, only your preparation. Study the catalysts, plan your trades, and always respect your stops.” And in the same spirit of disciplined trading, it’s worth remembering another key principle: as Tim Bohen, lead trainer with StocksToTrade says, “If you’re still guessing at the end of your analysis, it’s probably not a trade worth taking.”.
This is stock news, not investment advice. StocksToTrade News delivers real-time stock market updates tailored to highlight the key catalysts driving short-term price movements. Our coverage is designed for active traders and investors who thrive in fast-moving markets, with a focus on volatile sectors like penny stocks, AI stocks, Robinhood stocks and other momentum plays. From earnings reports and FDA approvals to mergers, new contracts, and unusual trading volume, we break down the events that can spark significant price action.
Looking to level up your trading game? Explore StocksToTrade, the ultimate platform for traders. With powerful tools designed for swing and day trading, integrated news scanning, and even social media monitoring, StocksToTrade keeps you one step ahead.
Check out our quick startup guide for new traders!
- How to Read Stock Charts: A Guide for Beginners
- Trading Plan: 6 Steps to Create One
- How To Create a Stock Watchlist
Ready to build your watchlists? Check out these curated lists:
Once your watchlist is set, take the next step and trade with confidence using StocksToTrade’s robust platform. Don’t miss out — grab your 14-day trial for just $7 and experience the edge you need to thrive in today’s fast-paced markets.