
Genuine Parts Company stocks have been trading up by 11.7 percent following upbeat earnings that exceeded market expectations.
What Traders Need To Know
- DA Davidson initiated coverage on Genuine Parts Company with a Buy rating and a $145 price target, above the current analyst mean target of $134 and aligned with an overall Overweight consensus rating.
- Shares of GPC popped about 7% after a Bloomberg report of a cash bid from O’Reilly Automotive for the auto parts unit, signaling strong sensitivity to deal headlines.
- The company is reviewing options for its auto parts arm, including a $10B+ sale to O’Reilly or a spinoff, with a possible rival bidder and a decision expected by the end of the summer.
- DA Davidson argues Genuine Parts stock is materially undervalued, pointing to value from a planned motion business spin-off, NAPA cost cuts, and leverage to a better industrial cycle.
- Mizuho questions the odds of an O’Reilly deal, citing NAPA’s lower margins, reminding traders that headline bids do not always become completed transactions.
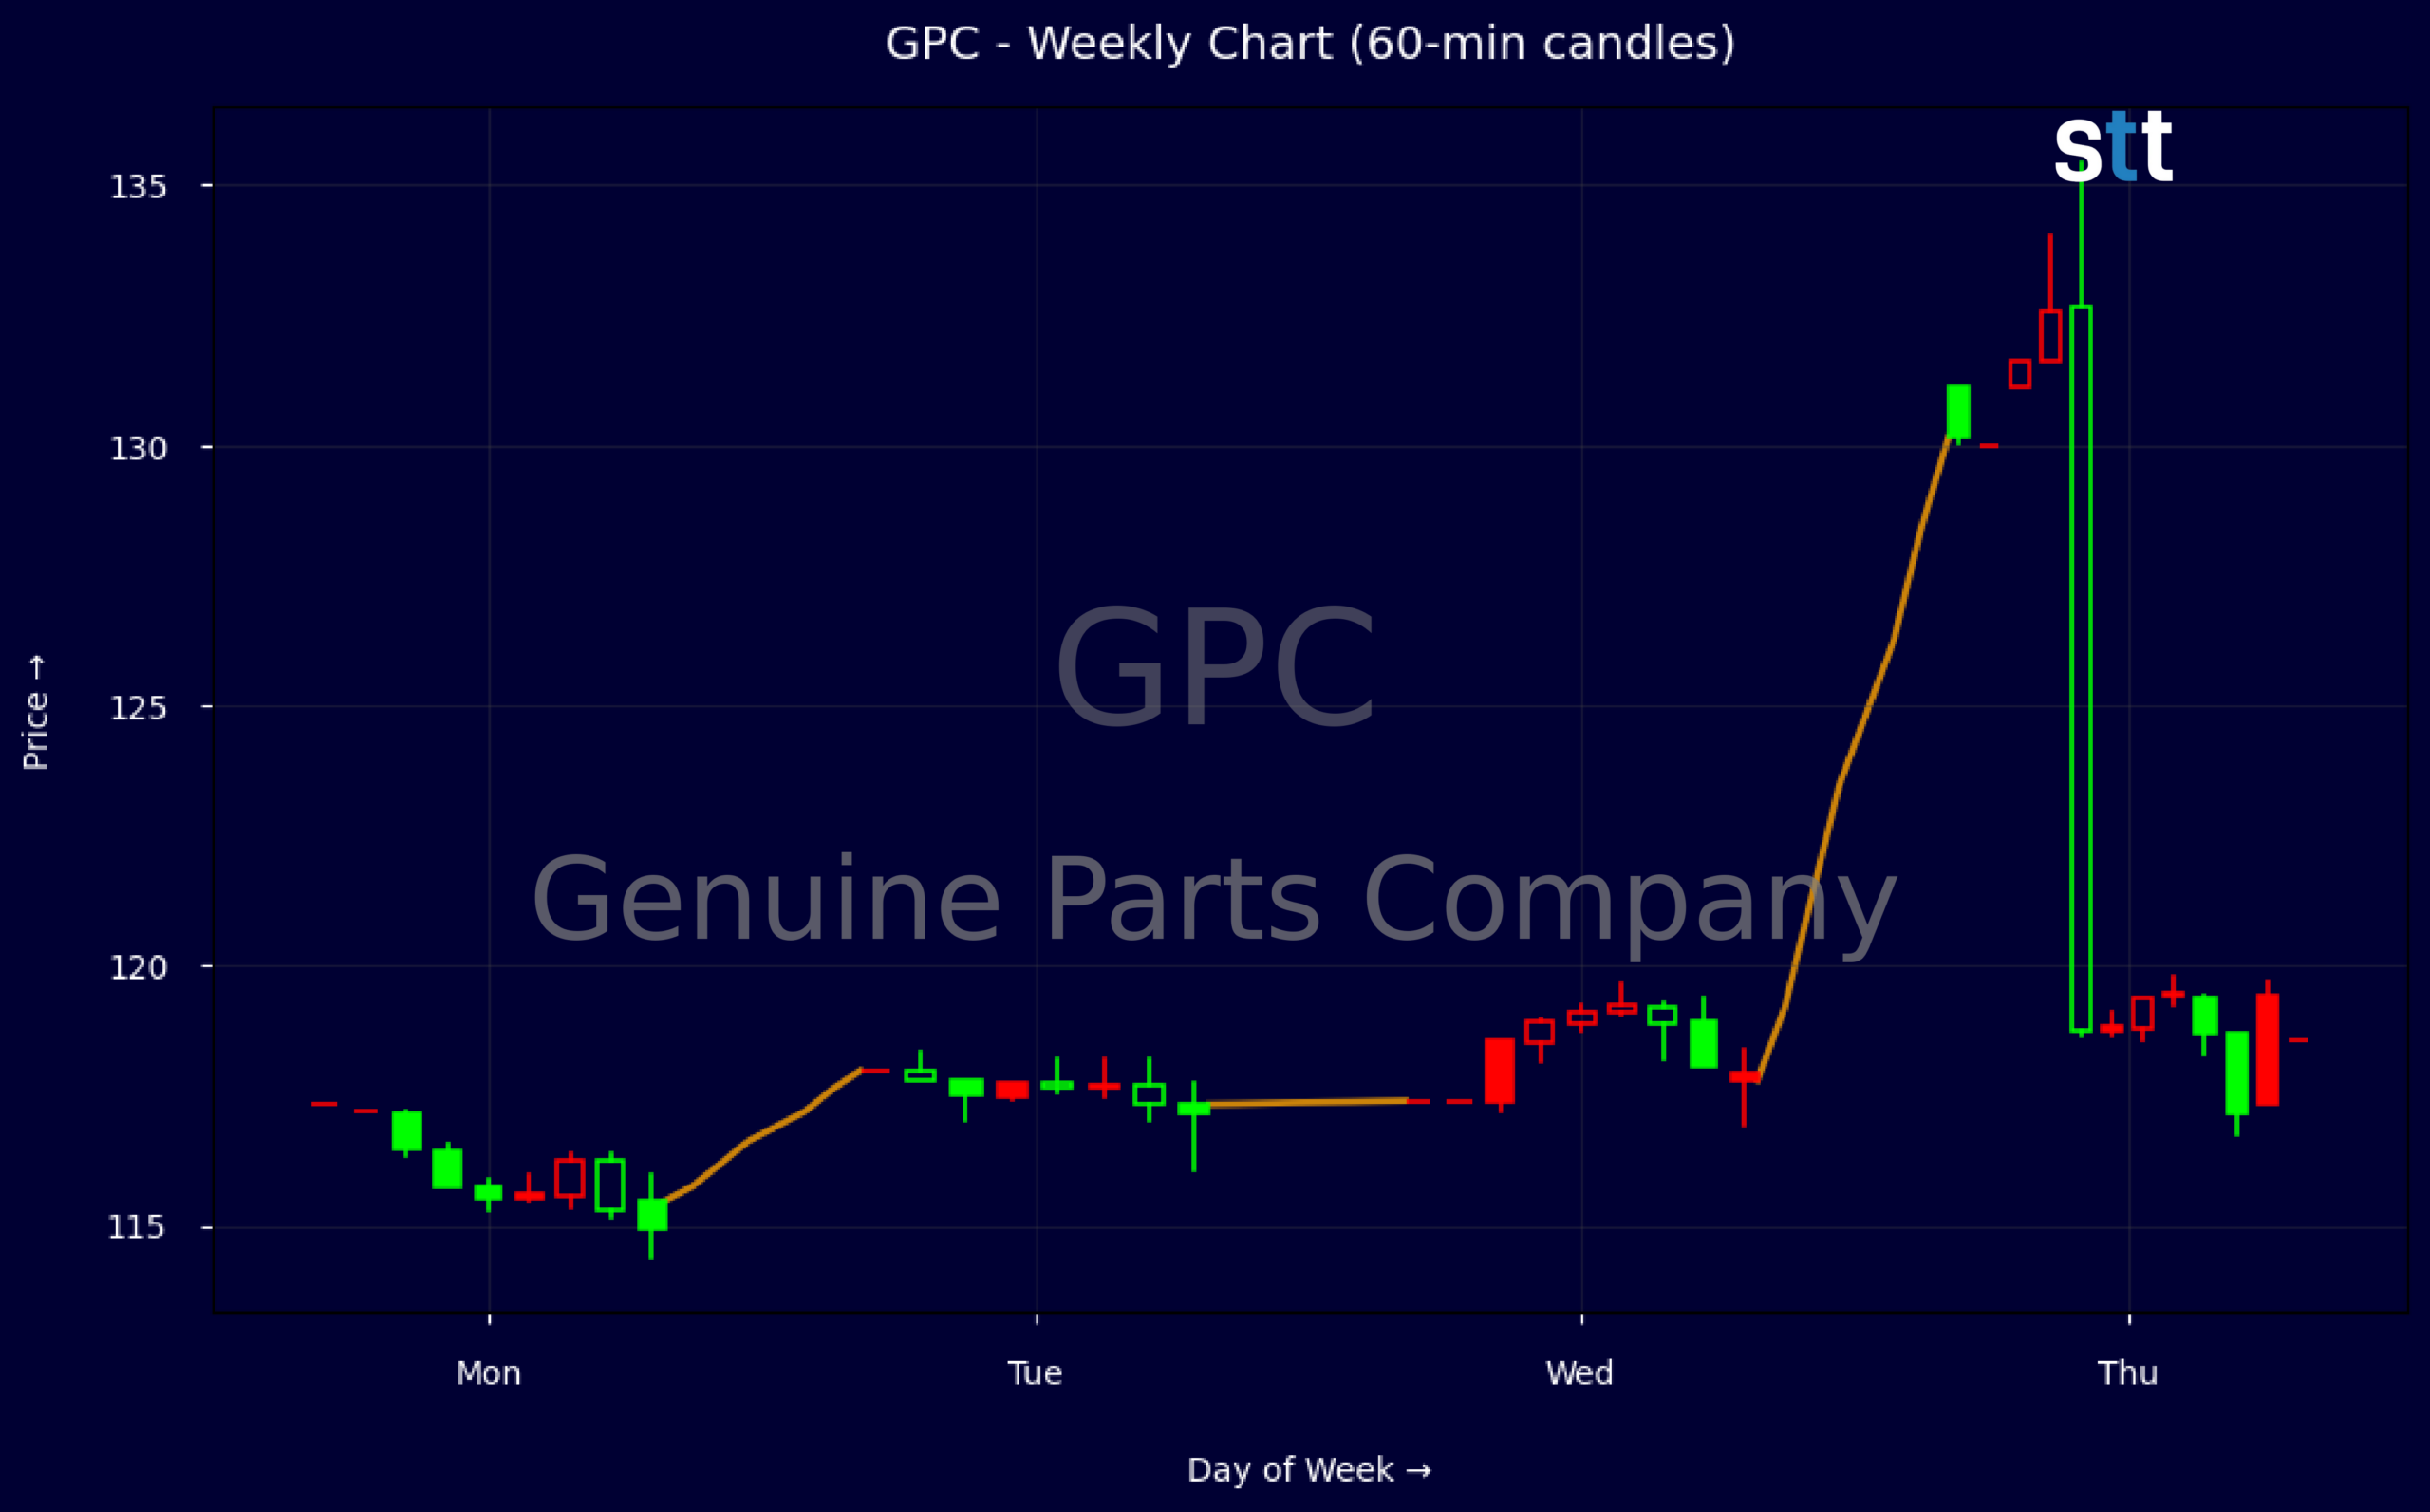
Weekly Update Jun 29 – Jul 03, 2026: On Saturday, July 04, 2026 Genuine Parts Company stock [NYSE: GPC] is trending up by 11.7%! Discover the key drivers behind this movement as well as our expert analysis in the detailed breakdown below.
Consumer Discretionary industry expert:
Analyst sentiment – positive
Genuine Parts occupies a solid but currently inefficient position in auto and industrial parts distribution, with $24.3B in revenue and attractive 36.9% gross margin offset by very thin EBIT (0.9%) and EBITDA (3.1%) margins, implying heavy SG&A and under-earning assets. ROE of 20.8% and ROA of 4.7% look acceptable, but leverage is elevated (total debt/equity 1.5x, interest coverage 4.5x). Cash conversion is weak: negative Q1 free cash flow of $33.6M and working-capital drag underscore execution risk.
Technically, GPC has transitioned from a low-liquidity equilibrium around $117–118 to a clear upside break, with the 7/2 weekly bar opening $132.57 and closing near the highs at $131.13, confirming a new short-term uptrend. Five‑minute candles show strong buying into strength, with pullbacks being shallow and quickly absorbed. The key actionable level is $130: above it, long bias is warranted; a decisive break below, especially on rising volume, would signal a failed breakout.
More Breaking News
- BMNR Stock Pulls Back As Traders Gauge Risk
- NVDA Stock Rebounds As Traders Weigh Trump Sale News
- FDXF Stock Climbs As Momentum Traders Target Freight Play
- CMCSA Stock Grinds Higher As Restructuring Meets Earnings Beat
Current news flow is strongly constructive: DA Davidson’s Buy and $145 target, plus a potential $10B+ monetization of NAPA or a spin, create a credible path to value unlock versus Consumer Discretionary and vehicle-parts peers. Even if an O’Reilly deal fails, strategic alternatives and industrial-cycle leverage support multiple expansion from an optically distorted 243x P/E. I see asymmetric upside to $140–145 over 12 months, with support at $125 and resistance at $140, favoring accumulation on dips.
Quick Financial Overview
Genuine Parts Company (GPC) just gave traders a clean example of how fast re‑rating can happen when a credible M&A headline hits. Weekly data show the stock grinding around $117 into early 2026/07/01, then gapping sharply on 2026/07/02 with a high near $134 and a close around $131.13. Intraday, that move ran from roughly $119.41 at the open to a spike above $135, before settling back near $132.57, which is classic news-driven expansion in both range and volume. For short‑term traders, that creates a new reference zone between roughly $130 support and $135 resistance.
Under the hood, GPC is a large, established business with about $24.3B in trailing revenue and a healthy 36.9% gross margin. Net income in the latest quarter was about $188.5M on $6.26B of revenue, but reported earnings quality is noisy, with special items and a very high stated P/E ratio of 243.7. The market is not paying that kind of multiple for the core business alone; much of the setup is about sum‑of‑the‑parts value and corporate actions.
Balance sheet metrics are mixed. Debt is meaningful, with total debt to equity near 1.5 and a leverage ratio of 4.7, but interest coverage around 4.5 shows the company can still service that load. Operating cash flow of about $63.9M last quarter and negative free cash flow reflect heavy capital spending and working capital drag, not a broken model, but they do limit flexibility if credit conditions tighten. A roughly 3.2% dividend yield and a long record of growth in payouts add a floor for some longer‑term capital, which can help stabilize pullbacks after big news spikes.
Conclusion
This is stock news, not investment advice. StocksToTrade News delivers real-time stock market updates tailored to highlight the key catalysts driving short-term price movements. Our coverage is designed for active traders and investors who thrive in fast-moving markets, with a focus on volatile sectors like penny stocks, AI stocks, Robinhood stocks and other momentum plays. From earnings reports and FDA approvals to mergers, new contracts, and unusual trading volume, we break down the events that can spark significant price action.
Looking to level up your trading game? Explore StocksToTrade, the ultimate platform for traders. With powerful tools designed for swing and day trading, integrated news scanning, and even social media monitoring, StocksToTrade keeps you one step ahead.
Check out our quick startup guide for new traders!
- How to Read Stock Charts: A Guide for Beginners
- Trading Plan: 6 Steps to Create One
- How To Create a Stock Watchlist
Ready to build your watchlists? Check out these curated lists:
Once your watchlist is set, take the next step and trade with confidence using StocksToTrade’s robust platform. Don’t miss out — grab your 14-day trial for just $7 and experience the edge you need to thrive in today’s fast-paced markets.