
Duolingo Inc. stocks have been trading up by 32.43 percent amid optimism over stronger user growth and monetization prospects.
Key Takeaways
- Duolingo reported a strong Q3 with daily active user (DAU) growth accelerating to 29% year over year and all key financial metrics beating expectations, driven by broad-based user growth across regions and subjects.
- The company posted Q3 2026 revenue of $309M, beating expectations of about $303M, while Q3 EPS of $0.54 came in slightly below the $0.57 consensus.
- Duolingo guided Q4 revenue to $322M, above the Wall Street consensus estimate of $314.55M, and issued FY26 revenue guidance of $1.22B, slightly ahead of the $1.21B consensus.
- User engagement remains strong with 54.9M daily active users, and management emphasized better teaching quality, user growth, and a gradual shift toward higher bookings without harming the free user experience.
- Morgan Stanley and Goldman Sachs both raised their price targets on Duolingo while maintaining neutral/Equal Weight ratings, stressing that future upside depends on improved monetization, even as a securities class action questions whether monetization and AI-driven content may be degrading product quality.
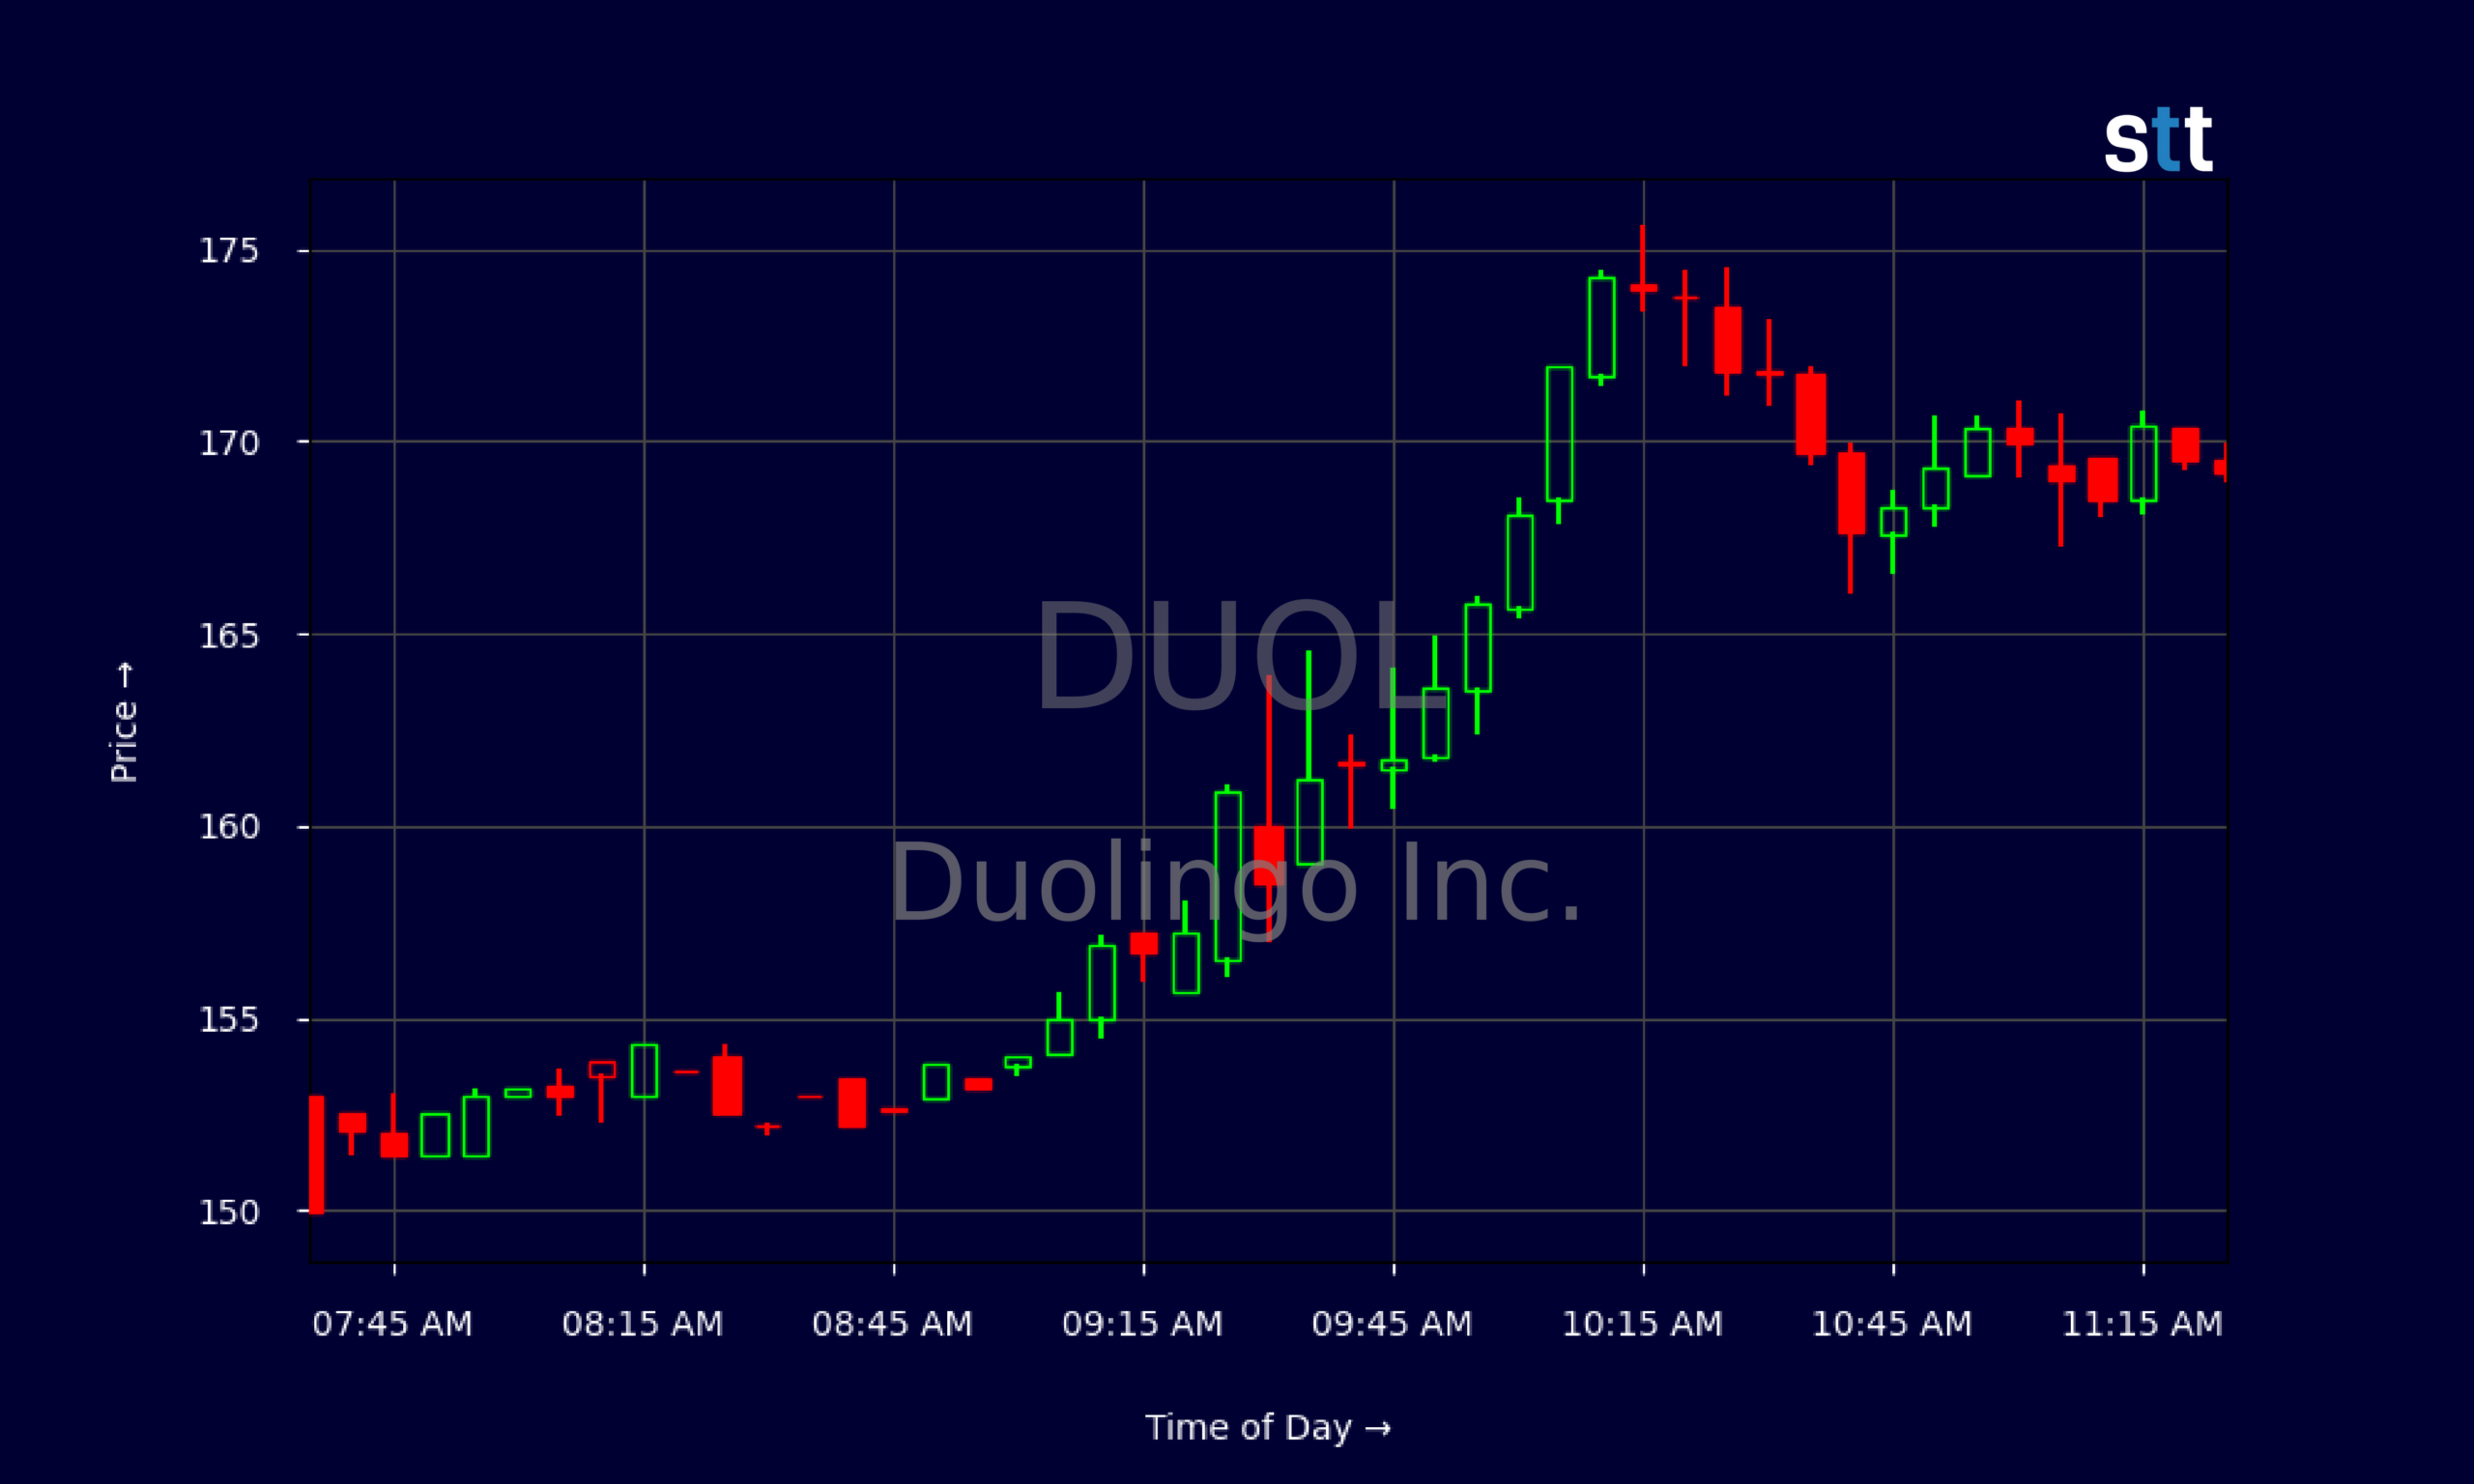
Live Update At 11:32:10 EST: On Wednesday, November 04, 2026 Duolingo Inc. stock [NASDAQ: DUOL] is trending up by 32.43%! Discover the key drivers behind this movement as well as our expert analysis in the detailed breakdown below.
Quick Financial Overview
DUOL has turned its latest earnings release into a strong momentum catalyst. After closing at $128.00 on 2026/11/03, Duolingo ripped to a 2026/11/04 close of $169.07, with an intraday high of $175.56. That is a massive post-earnings gap and trend day, the kind of move momentum traders hunt.
Fundamentally, Duolingo delivered Q3 2026 revenue of $309M versus roughly $303M expected, while EPS landed at $0.54 versus a $0.57 consensus. So the story is clear: the market is rewarding top-line growth and user traction more than a minor profit miss. The daily chart shows DUOL breaking out from the mid-$130s area after several weeks of consolidation between roughly $135 and $145.
More Breaking News
- SK Hynix Slips 0% As NVIDIA Earnings Boost Fades
- ARQ Stock Pops As Earnings Beat Fuels Guidance Hike
- BBD Stock Jumps As Analyst Upgrades And Buyback Fuel Momentum
- NOK Stock Slides As Traders Question Rally After Earnings
Under the hood, DUOL looks like a real business, not a story stock. Revenue over the last year is about $1.04B, with a hefty 72.7% gross margin and an EBIT margin of 16.1%. Returns on equity and capital are strong, and the balance sheet is clean with low debt and a current ratio of 2.7. For traders, that means pullbacks on DUOL have real fundamental support beneath the price action.
Why Traders Are Watching DUOL Now
DUOL is getting attention because the growth engine is not just humming — it is accelerating. Duolingo reported 29% year-over-year DAU growth and now sits at 54.9M daily active users. For an app-based platform, that is a massive audience. When those users climb at a faster pace while the company beats revenue expectations, momentum traders pay attention.
The Q3 report checks several boxes. Revenue of $309M beat the $303M area consensus. Management then doubled down with Q4 revenue guidance of $322M, well ahead of the roughly $314.55M Wall Street view. On top of that, Duolingo issued FY26 revenue guidance of $1.22B versus $1.21B expected. The beats are not gigantic, but they consistently lean to the upside. That pattern often keeps trend traders on the long side until something breaks.
DUOL is also telling a clear product story. Management highlighted better teaching quality, broad-based user growth across regions and subjects, and a gradual push toward higher bookings — all while trying not to wreck the free user experience with aggressive paywalls. That balance matters. Traders know you can juice numbers short term with heavy ads and upsells, but if churn spikes, the chart eventually tells the truth.
Wall Street is taking notice too. Morgan Stanley nudged its DUOL price target from $125 to $140, and Goldman Sachs moved from $114 to $135, both while staying neutral on rating. The message is: strong DAUs and execution are real, but the next leg of upside depends on monetization. For active traders, that means the key watch items ahead are ARPU trends, subscription conversions, and how far Duolingo can push pricing before users push back.
Conclusion
For now, the tape is siding with the bulls on DUOL. The stock exploded from the low $130s to the high $160s and beyond after Q3 2026 results, confirming that traders were waiting for proof of durable growth. Accelerating DAUs, a $309M revenue beat, and above-consensus Q4 and FY26 guidance gave them exactly that. With strong margins and more than $1.18B in cash on the latest balance sheet, Duolingo has room to keep investing in product and marketing.
But this is not a one-way story. DUOL is facing a securities class action and shareholder investigation focused on its monetization strategy and heavy use of rapidly generated AI content. The complaint argues that ads and upsells may be adding friction and that AI-driven content could hurt quality and long-term growth. Legal and reputational overhangs like this can cap valuation and create sharp headline-driven dips, even in a strong uptrend.
That is why traders studying DUOL need to stay nimble. The growth is real, the chart is strong, and analyst targets are drifting higher — yet the market’s focus is already shifting from raw user numbers to monetization quality and sustainability. In the words of Tim Sykes, “The market doesn’t care about your opinion, only price action and risk management.” As Tim Bohen, lead trainer with StocksToTrade says, “For me, trading is more about managing risk than finding the next big mover.” With DUOL, the price action is saying “uptrend,” but the risk side still demands tight plans, clear stop levels, and constant review of new data.
This is stock news, not investment advice. StocksToTrade News delivers real-time stock market updates tailored to highlight the key catalysts driving short-term price movements. Our coverage is designed for active traders and investors who thrive in fast-moving markets, with a focus on volatile sectors like penny stocks, AI stocks, Robinhood stocks and other momentum plays. From earnings reports and FDA approvals to mergers, new contracts, and unusual trading volume, we break down the events that can spark significant price action.
Looking to level up your trading game? Explore StocksToTrade, the ultimate platform for traders. With powerful tools designed for swing and day trading, integrated news scanning, and even social media monitoring, StocksToTrade keeps you one step ahead.
Check out our quick startup guide for new traders!
- How to Read Stock Charts: A Guide for Beginners
- Trading Plan: 6 Steps to Create One
- How To Create a Stock Watchlist
Ready to build your watchlists? Check out these curated lists:
Once your watchlist is set, take the next step and trade with confidence using StocksToTrade’s robust platform. Don’t miss out — grab your 14-day trial for just $7 and experience the edge you need to thrive in today’s fast-paced markets.