
Brinker International Inc. stocks have been trading up by 14.75 percent after strong earnings and upbeat restaurant traffic trends.
Key Takeaways
- Multiple Wall Street firms have shifted to more bullish stances on Brinker International (EAT), with Jefferies and Raymond James both upgrading the stock and highlighting durable growth.
- Analyst price targets for EAT now cluster around the mid‑$250s to mid‑$260s, implying notable upside from recent trading levels despite some modest target trims.
- UBS expects Chili’s same‑store sales at EAT to come in above consensus for fiscal Q1 2027, supported by menu and marketing moves and what it views as an attractive valuation.
- TD Cowen and Citi see macro pressure from higher gasoline prices and early‑Q2 moderation in sales but still rate EAT a Buy, pointing to modest upside in same‑store sales and earnings.
- Brinker International, parent of Chili’s and Maggiano’s, will report fiscal Q1 2027 results on 2026/10/28, setting up a key catalyst for EAT traders.
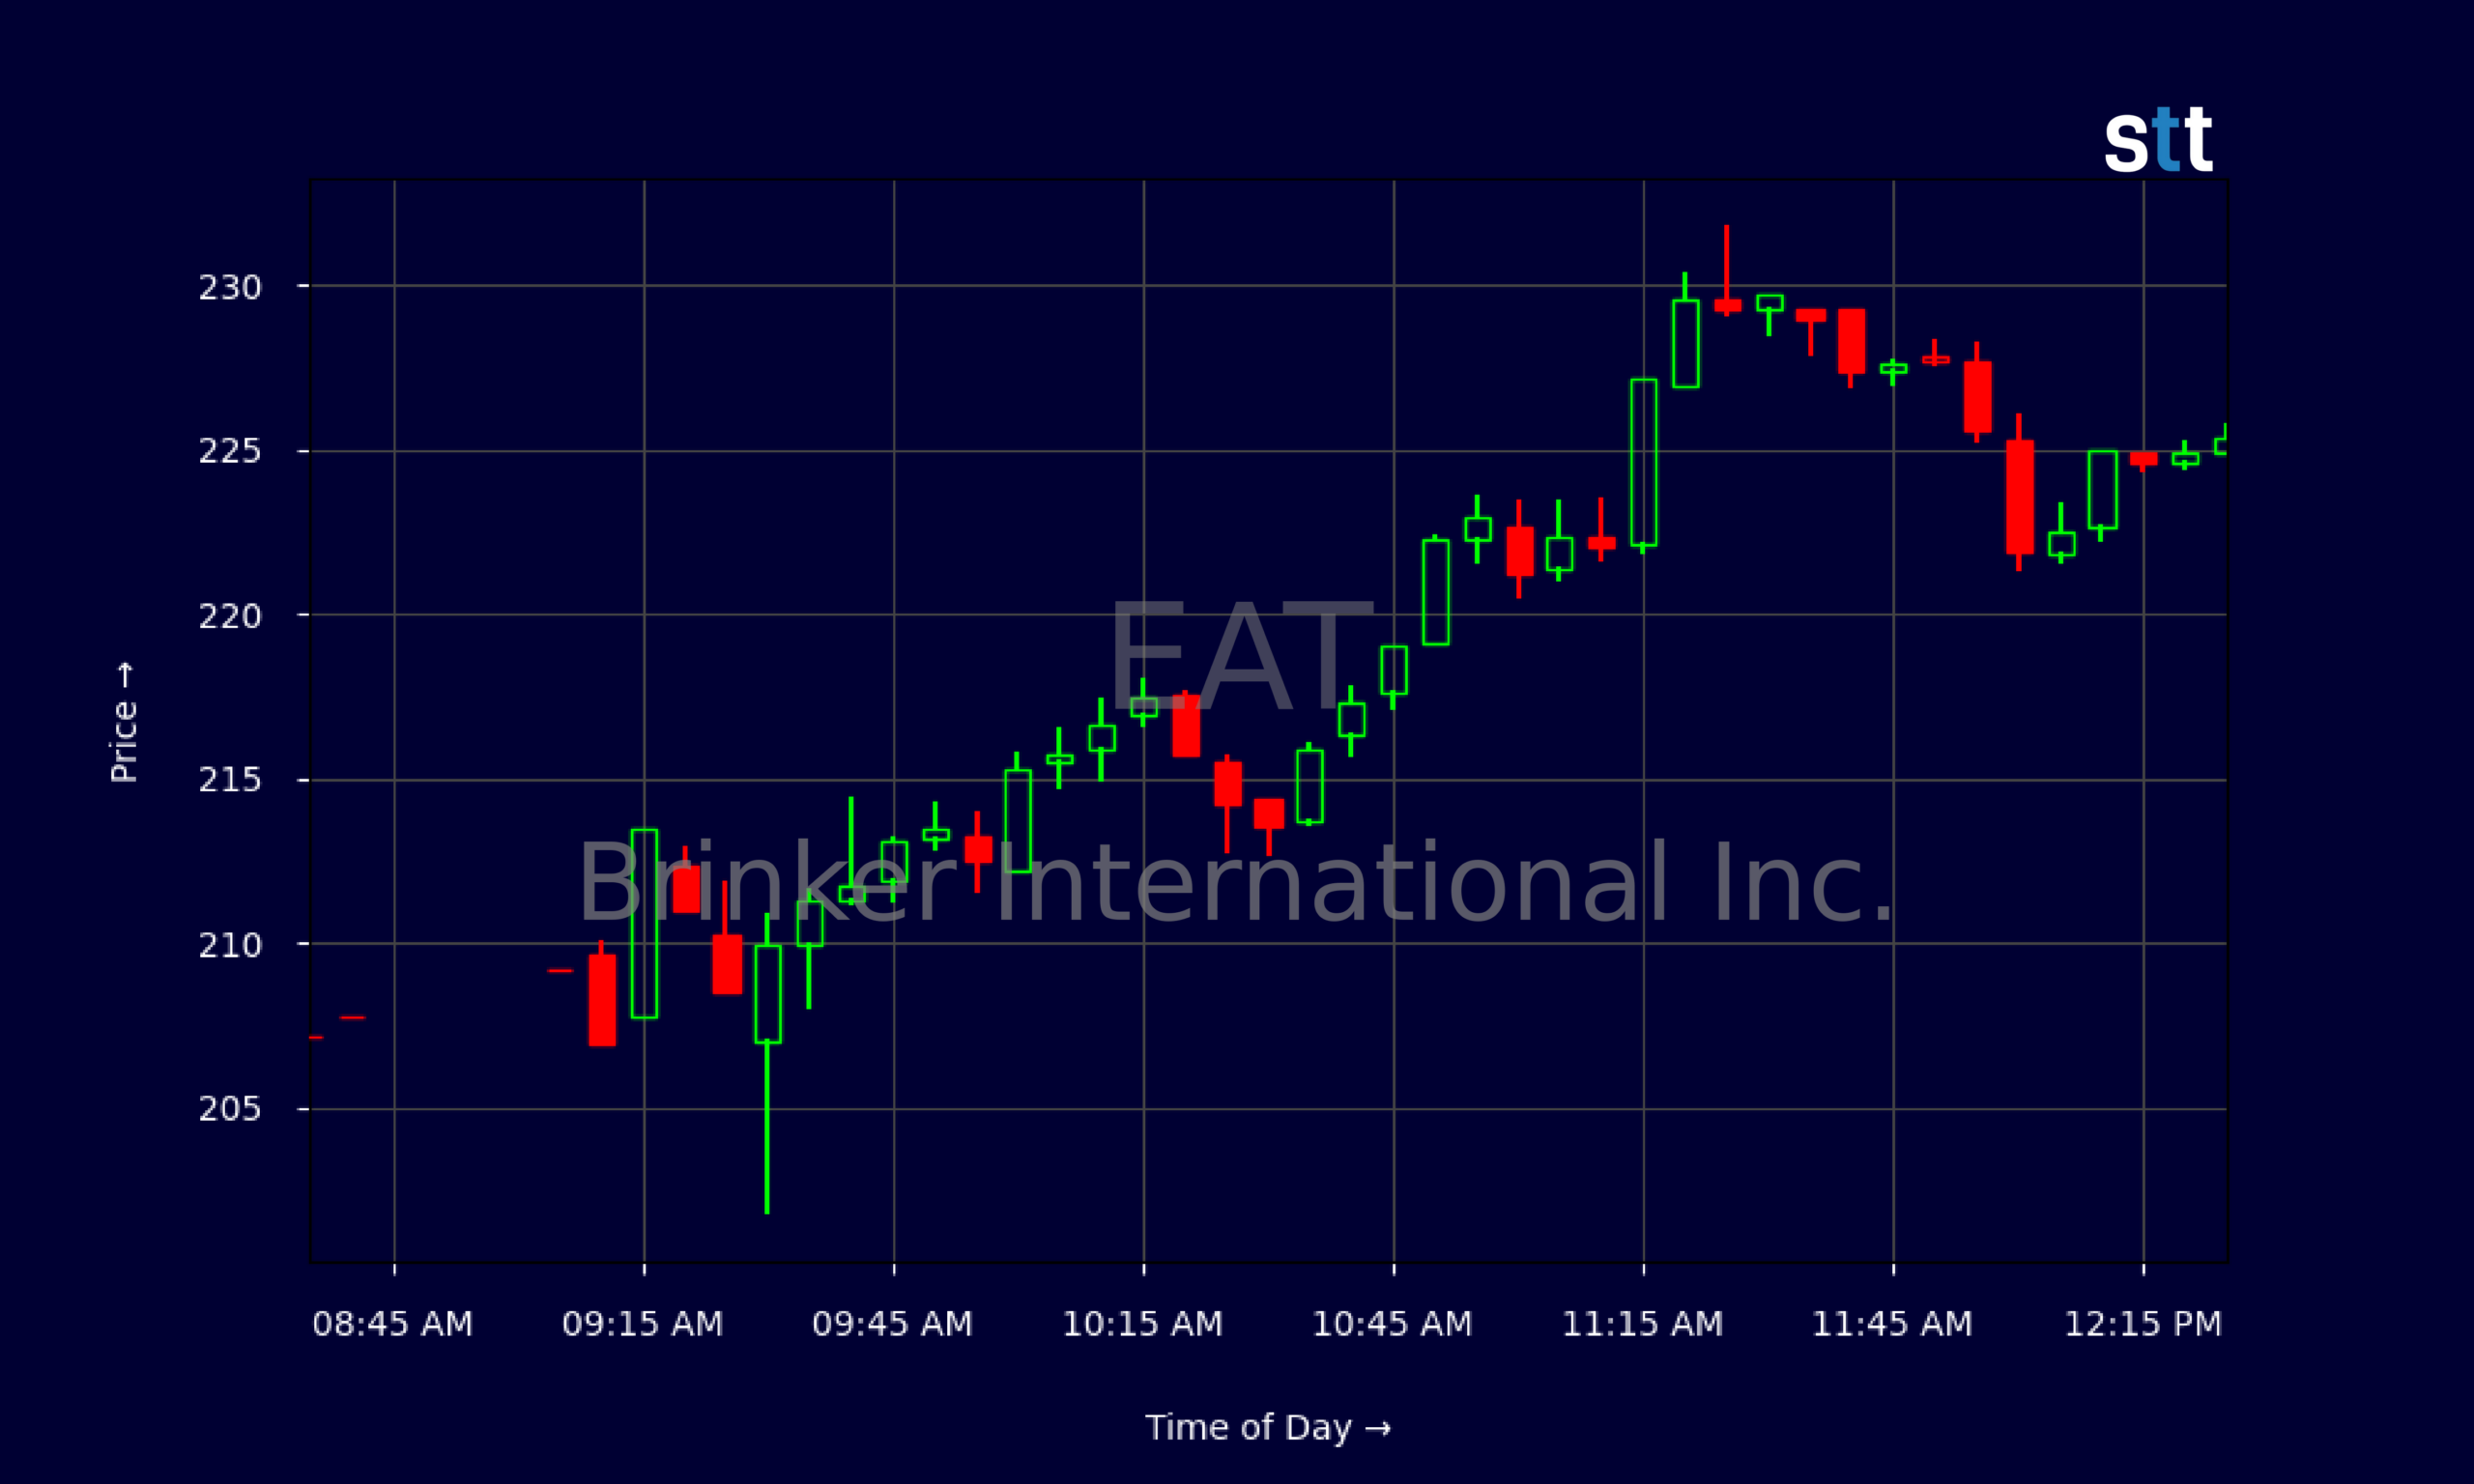
Live Update At 12:32:10 EDT: On Wednesday, October 28, 2026 Brinker International Inc. stock [NYSE: EAT] is trending up by 14.75%! Discover the key drivers behind this movement as well as our expert analysis in the detailed breakdown below.
Quick Financial Overview
Brinker International’s recent tape tells you why traders are glued to EAT. Over the past couple of weeks, the stock has ripped from the mid‑$180s to a close near $225.73, printing a fresh high at $231.74. That is a strong breakout from a choppy base around $190–$200, showing money rotating back into the name ahead of earnings.
Intraday action on the latest session shows aggressive dip buying. EAT opened at $207, briefly flushed to $201.83, then reclaimed $210 within minutes and trended higher the rest of the morning. By midday, EAT was stair‑stepping through the $220s and held those gains into the close. This kind of wide‑range expansion with strong closes usually signals active funds building positions rather than just day‑traders flipping.
More Breaking News
- F5 Inc. Falls 20% on Slower Sales Outlook
- GCTK Stock Jumps As Qare Data Platform Launch Fuels Momentum
- RenaissanceRe Falls 2% After Mixed Third-Quarter Results
- BRAI Stock Rockets As Force AI Deal Ignites Trading
Under the hood, EAT is not trading like a broken chain. Revenue is about $5.81B with roughly 12% three‑year growth, and profitability metrics like a 10.7% EBIT margin and 17.7% recent return on assets show real operating leverage. The P/E around 17.8 and price‑to‑sales near 1.4 keep valuation in a middle zone — not cheap, but not bubble territory for a brand‑driven consumer name. High leverage and a low current ratio mean EAT needs those cash flows to keep humming, so any earnings miss will matter. For now, the chart says momentum is on the bulls’ side.
Why Traders Are Watching EAT So Closely
The core shift around Brinker International is coming from the analyst community, and traders are taking notice. Jefferies has moved EAT from a simple turnaround story to what it calls a “durable, compounding growth” play. It upgraded the stock to Buy and pushed its target to $255 from $230, citing higher traffic volumes, better margins, and a reinvestment flywheel that can feed future growth. That is the kind of language that often anchors a multi‑quarter trend if the numbers back it up.
Raymond James followed with its own upgrade, bumping Brinker International to Strong Buy while slightly trimming its target to $260 from $270. The cut in the target sounds cautious, but the real message for EAT traders is expectations for a strong earnings beat and raise, plus steady mid‑single‑digit‑plus comparable sales growth. In trader language, that screams “upside catalyst risk” into the 2026/10/28 call.
UBS adds another layer. It cut its target on EAT to $265 from $285, but kept a Buy rating and expects a strong start to FY27. The firm specifically calls for Chili’s same‑store sales to beat consensus in fiscal Q1 2027, driven by menu tweaks and effective marketing. UBS also points to valuation support, which matters with EAT having pulled back 2.3% recently to around $199 before this latest breakout.
TD Cowen and Citi provide needed balance. Both trimmed targets — Cowen to $250, Citi to $270 — blaming a category‑wide slowdown in casual dining tied to higher gas prices and early‑Q2 sales moderation. Yet both still tag Brinker International as a Buy and see at least modest upside to comps and earnings. Put all of this together, and you have EAT trading below an approximate $265 Street mean target, with multiple firms upgrading the rating even as they fine‑tune targets lower. That gap between price and targets is exactly what momentum‑focused traders hunt.
Conclusion
For active traders, EAT is a classic setup where fundamentals, sentiment, and technicals all line up ahead of a defined catalyst. Brinker International just printed strong free cash flow of about $159.2M in the latest quarter, paid down some debt, and still found room to repurchase roughly $100.5M of stock. Return on equity is sky‑high, even if leverage amplifies that figure. The balance sheet is far from pristine, but cash generation and interest coverage north of 20x give Brinker room to execute.
On the tape, Brinker International has shifted from grinding sideways to trending, with EAT pushing into new high territory on expanding volume. The analyst backdrop is broadly bullish: Jefferies and Raymond James upgrades, UBS backing above‑consensus Chili’s comps, and a consensus overweight stance with average targets well above recent prices. The main risk hanging over EAT is macro — higher gasoline costs and a slowing casual‑dining category — plus the simple fact that expectations into the 2026/10/28 call are now elevated.
Traders in the Tim Sykes community focus on exactly this kind of situation: defined catalyst, clear trend, and a crowd leaning bullish. As Tim Sykes likes to say, “The market doesn’t care about your opinion, only your preparation — study the pattern, know the catalysts, and be ready to react.” At the same time, it helps to remember the broader mindset that keeps traders grounded during hot runs like this; as Tim Bohen, lead trainer with StocksToTrade says, “Time and experience have taught me that missed opportunities are part of the game. There’s always another setup around the corner.”. For EAT, that preparation means digging into the upcoming earnings, tracking same‑store sales commentary, and watching how price responds at key levels rather than blindly chasing the hype. This content is for educational and research purposes only and is not investment advice.
This is stock news, not investment advice. StocksToTrade News delivers real-time stock market updates tailored to highlight the key catalysts driving short-term price movements. Our coverage is designed for active traders and investors who thrive in fast-moving markets, with a focus on volatile sectors like penny stocks, AI stocks, Robinhood stocks and other momentum plays. From earnings reports and FDA approvals to mergers, new contracts, and unusual trading volume, we break down the events that can spark significant price action.
Looking to level up your trading game? Explore StocksToTrade, the ultimate platform for traders. With powerful tools designed for swing and day trading, integrated news scanning, and even social media monitoring, StocksToTrade keeps you one step ahead.
Check out our quick startup guide for new traders!
- How to Read Stock Charts: A Guide for Beginners
- Trading Plan: 6 Steps to Create One
- How To Create a Stock Watchlist
Ready to build your watchlists? Check out these curated lists:
Once your watchlist is set, take the next step and trade with confidence using StocksToTrade’s robust platform. Don’t miss out — grab your 14-day trial for just $7 and experience the edge you need to thrive in today’s fast-paced markets.