
Borr Drilling Limited stocks have been trading up by 9.87 percent following upbeat offshore drilling contract and utilization news.
What Traders Need To Know
- Q2 2026 revenue of $232.3M missed the $247.6M consensus, with adjusted EBITDA sliding to $43.8M on fewer active rigs, contract shifts, and one-off operational and regional cost hits.
- A $287M purchase of five Mexican jack-up rigs via 50:50 JV BC Ventures lifts the combined Borr Drilling Limited fleet to 34 units, using mostly non-recourse seller’s credit.
- Director Jeffrey Currie bought 125,000 shares for about $502,000, increasing his direct holdings to 479,423 shares per an SEC Form 4 filing.
- Director Tor Olav Troim added 1,500,000 shares for roughly $6.0M, taking his controlled stake to about 28.8M shares, signaling strong insider conviction.
- The company filed its unaudited Q2 and first-half 2026 report on Form 6-K, giving traders access to full interim financial details.
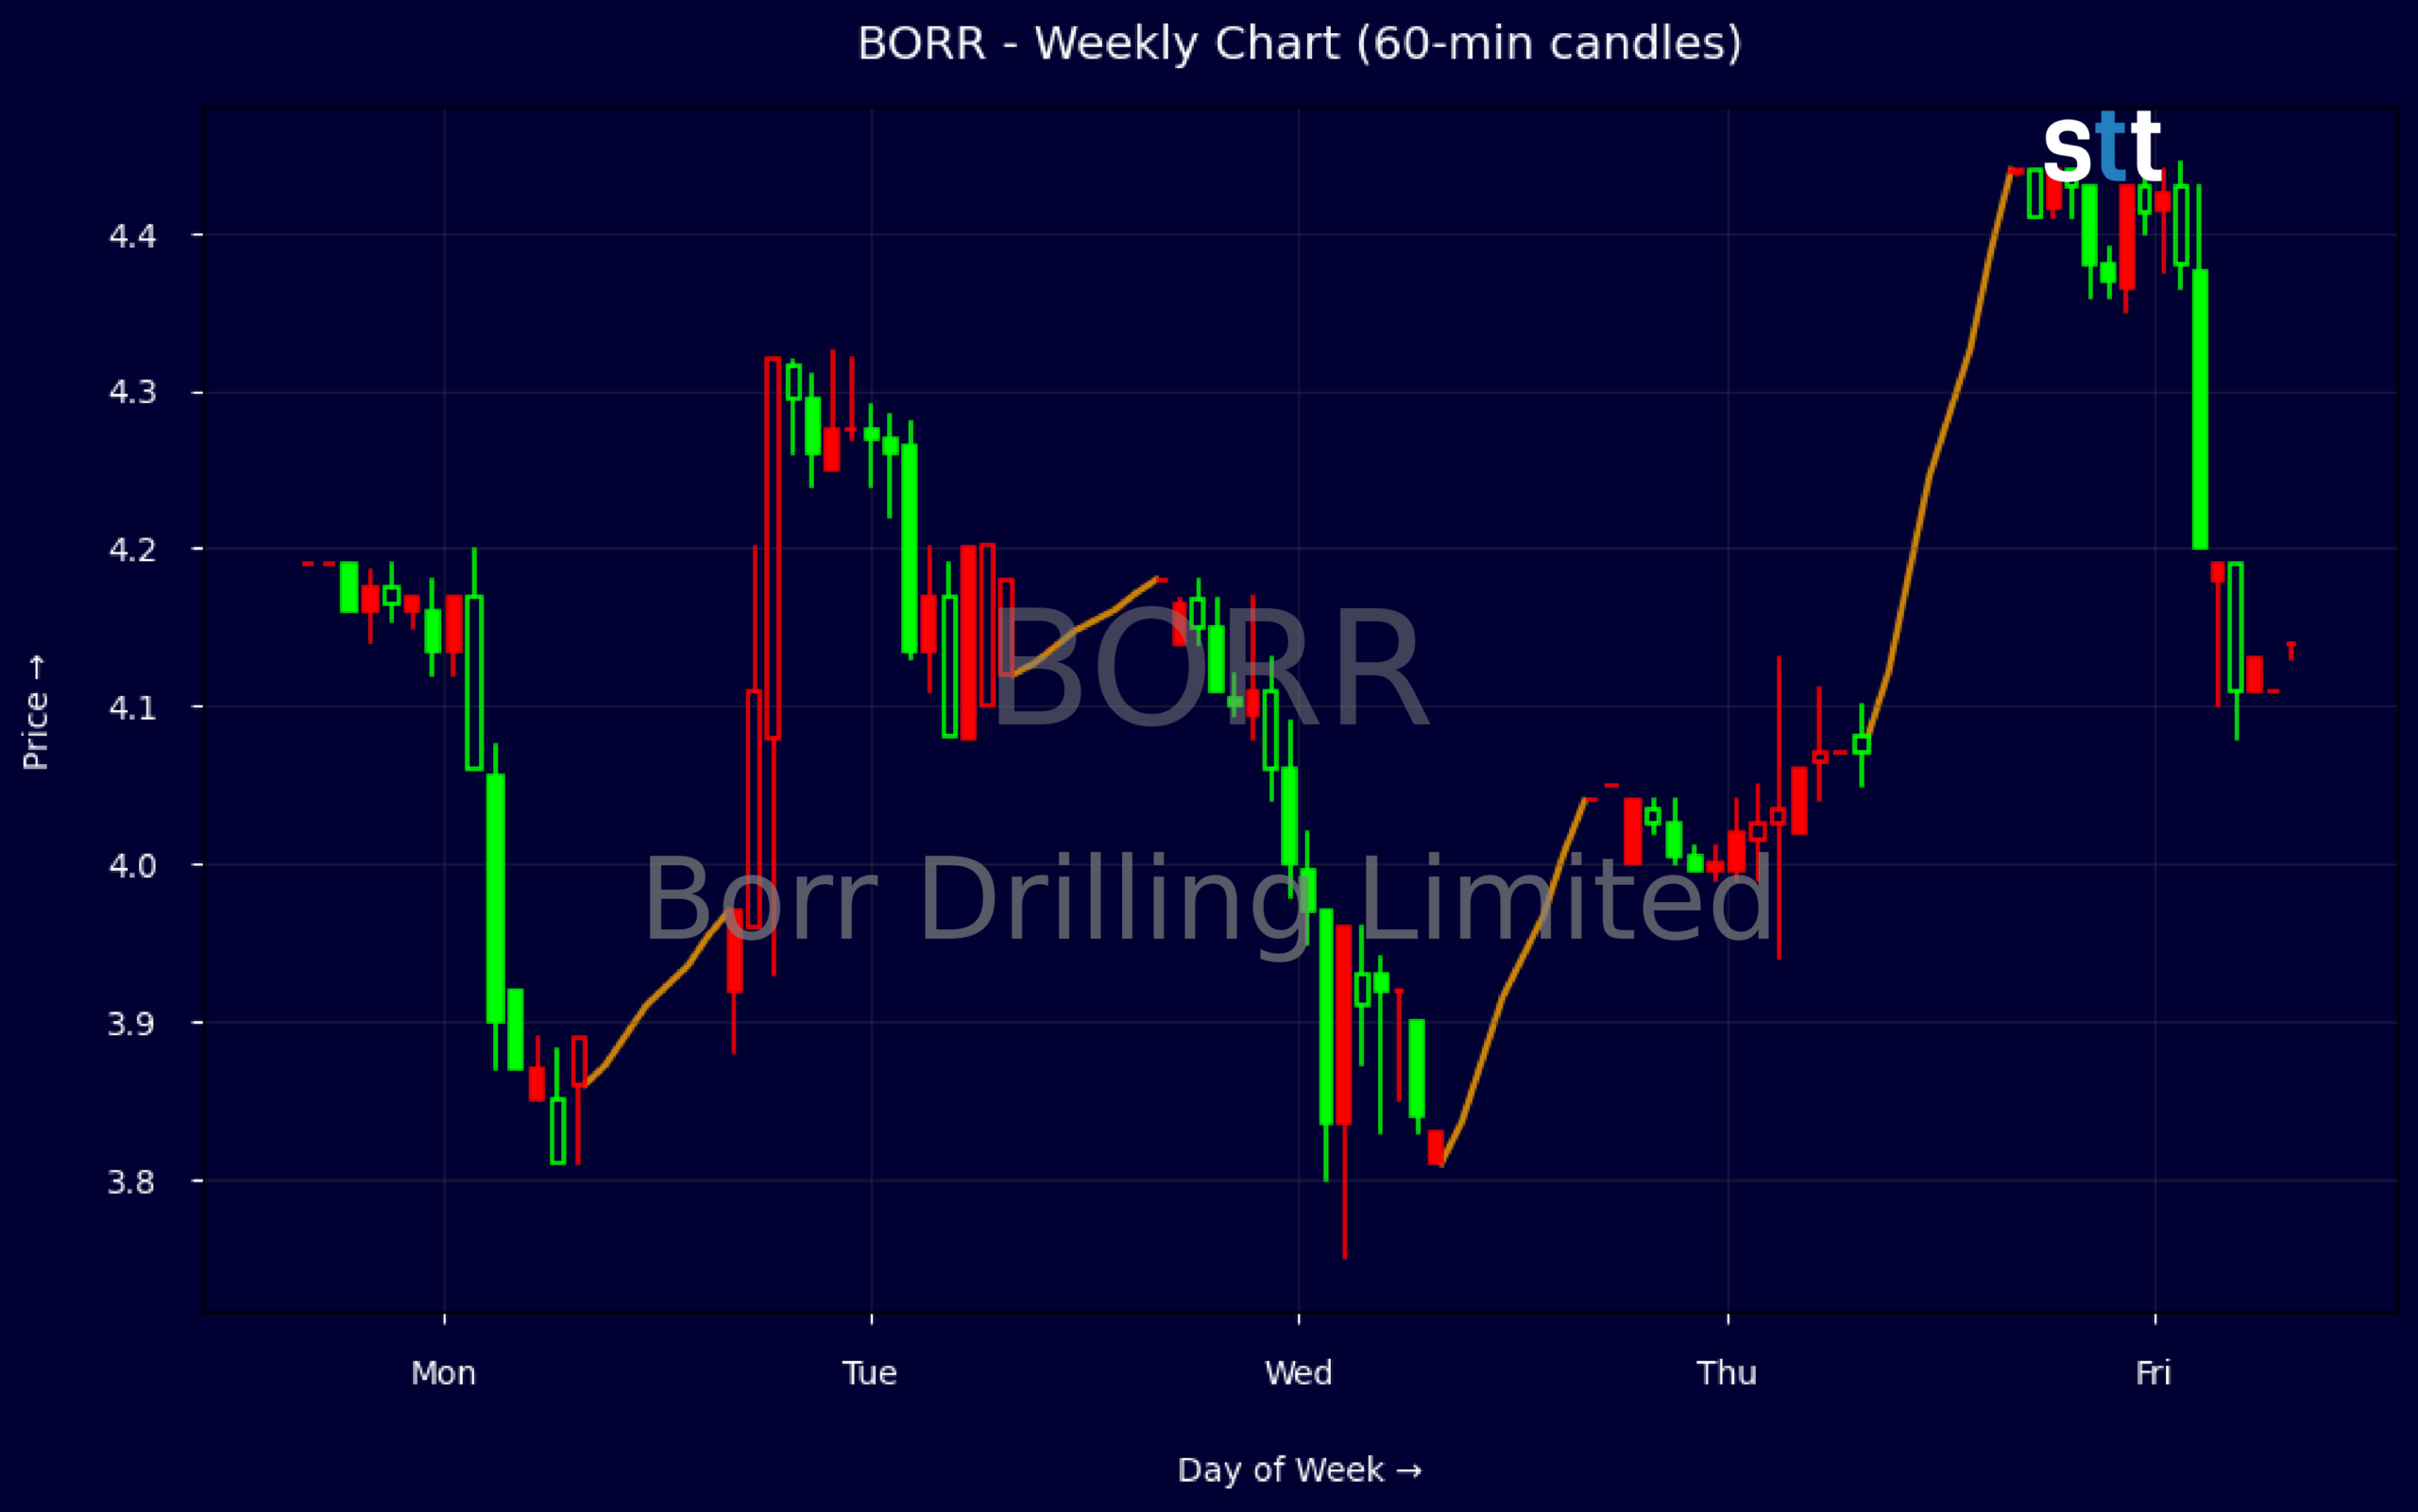
Weekly Update Aug 10 – Aug 14, 2026: On Sunday, August 16, 2026 Borr Drilling Limited stock [NYSE: BORR] is trending up by 9.87%! Discover the key drivers behind this movement as well as our expert analysis in the detailed breakdown below.
Energy industry expert:
Analyst sentiment – positive
Borr Drilling (BORR) is a leveraged, asset-heavy jack-up pure play with improving but fragile fundamentals. 2025 revenue of ~$1.02bn and price-to-sales of 1.34 and price-to-book of 1.11 signal the market is valuing the fleet near replacement, not on earnings, consistent with still-negative pre-tax margins (-63.7%) and ROE (-9.7%). The balance sheet is stretched: leverage ratio 3x, long-term debt ~$2.0bn versus equity ~$1.22bn, but working capital of ~$418m and $380m cash provide near-term liquidity.
Technically, BORR is attempting to base after a sharp selloff, with weekly closes clustering around the $4 handle. Recent prints show high intraday volatility (e.g., 4.32 high to 3.88 low) and a quick recovery to 4.44, suggesting aggressive dip-buying near $3.90–4.00. Five‑minute candles indicate heavy volume absorption around $4.00, turning it into a clear pivot. Dominant near-term trend is sideways-to-slightly-up; a tactical long entry at $4.00 with a stop below $3.80 and initial target $4.70 is justified.
More Breaking News
- NCPL Plunges As SEC Fraud Charges Ignite Class Actions
- REGN Jumps As Libtayo Data And Analyst Upgrades Fuel Bullish Outlook
- REGN Stock Climbs As Libtayo Data And Targets Rise
- GPN Stock Jumps As Wall Street Ups Price Targets
Fundamentally, Q2 2026 was weak (revenue miss, EBITDA compression to $43.8m) as rigs transitioned and one-off Odin prep, conflict-driven costs, and a credit loss hit results, but these are largely timing and mix issues, not structural demand erosion. The Mexico JV’s five-rig acquisition, financed mostly via non-recourse seller credit, expands earnings capacity without proportionate balance-sheet strain. Heavy insider buying by Currie and Trøim confirms high internal conviction. Relative to Energy/Fossil Fuel benchmarks, BORR offers higher beta and torque to jack-up dayrate strength. Base case: re-rating to $5.25–5.75 over 12 months if utilization stabilizes and costs normalize; key support $3.80, resistance $4.70 then $5.50.
Quick Financial Overview
Borr Drilling Limited sits in a classic tug-of-war between weak near-term earnings and aggressive fleet expansion. Revenue for Q2 2026 came in at $232.3M versus $247.6M expected, and adjusted EBITDA dropped to $43.8M as rigs rolled between contracts and the Odin rig incurred prep costs. Extra insurance and fuel tied to Middle East tensions plus a credit loss in West Africa pressured margins further, reminding traders that this is still a volatile offshore cycle play.
On the balance sheet, BORR shows about $3.63B in total assets and $2.40B in total liabilities, including roughly $2.02B in long-term debt as of 2025/12/31. Book value per share is about $3.97, with price-to-book near 1.11 and price-to-sales around 1.34, which puts the stock just slightly above its accounting value and modestly valued versus its revenue base. Returns remain mixed, with a recent positive 5.23% return on invested capital but negative longer-term return on equity and a pretax margin near -63.7%, highlighting that profitability is still inconsistent.
Recent price action in BORR reflects that cross-current. On the weekly tape, the stock swung from above $4.30 down to the high $3s before snapping back near the $4.40 area, suggesting active two-way trade around a perceived value zone slightly above book. Intraday, a 5-minute candle showed a move from about $4.30 to $4.43 with a dip to $4.26, hinting at intraday dip-buying and responsive demand below $4.30. For short-term traders, that $4.20–$4.30 band now looks like a key liquidity pocket, while the $4.40–$4.45 area marks immediate overhead supply.
Conclusion
Borr Drilling Limited is giving traders a mixed but tradeable story. On one side, the Q2 2026 miss, weaker adjusted EBITDA, and negative pretax margin highlight real earnings pressure and sensitivity to contract timing and regional shocks. On the other, BORR is expanding its fleet through the BC Ventures joint venture in Mexico, adding five premium jack-up rigs with mostly non-recourse seller’s credit and pushing total owned and jointly owned rigs to 34, which can enhance future revenue if utilization and dayrates cooperate.
Insider behavior is the clear supportive factor. Large open-market buys from directors Jeffrey Currie and Tor Olav Troim, plus additional beneficial ownership changes, show that key insiders are willing to commit millions at roughly current price levels. Technically, price clustering just above book value near $4.20–$4.40, along with intraday support buying around $4.26, gives traders a visible risk zone to lean against in the short term. The filed Form 6-K offers deeper numbers for those who want to drill into segment details and cash flows.
For active traders, BORR now trades like a battleground between short-term earnings weakness and a medium-term capacity build. Watching how price reacts around that $4.20–$4.30 area after news flows, and how quickly the new Mexican rigs contribute, will be key. That’s why many short-term traders will lean more on the current price action than on long-dated projections. As Tim Bohen, lead trainer with StocksToTrade says, “I focus on momentum that’s visible right now. Speculation on future moves is outside my playbook.”. As I tell my students, “The edge isn’t in predicting the story, it’s in knowing exactly where you’re wrong on the chart when the story shifts.”
This is stock news, not investment advice. StocksToTrade News delivers real-time stock market updates tailored to highlight the key catalysts driving short-term price movements. Our coverage is designed for active traders and investors who thrive in fast-moving markets, with a focus on volatile sectors like penny stocks, AI stocks, Robinhood stocks and other momentum plays. From earnings reports and FDA approvals to mergers, new contracts, and unusual trading volume, we break down the events that can spark significant price action.
Looking to level up your trading game? Explore StocksToTrade, the ultimate platform for traders. With powerful tools designed for swing and day trading, integrated news scanning, and even social media monitoring, StocksToTrade keeps you one step ahead.
Check out our quick startup guide for new traders!
- How to Read Stock Charts: A Guide for Beginners
- Trading Plan: 6 Steps to Create One
- How To Create a Stock Watchlist
Ready to build your watchlists? Check out these curated lists:
Once your watchlist is set, take the next step and trade with confidence using StocksToTrade’s robust platform. Don’t miss out — grab your 14-day trial for just $7 and experience the edge you need to thrive in today’s fast-paced markets.