
Boot Barn Holdings Inc. stocks have been trading up by 15.1 percent amid upbeat retail outlook and robust earnings momentum.
Key Takeaways
- Fiscal Q2 EPS landed at $1.73 versus roughly $1.63–$1.64 expected, on $581.8M in revenue that nudged past forecasts.
- Same‑store sales rose 1.4%, with e‑commerce up 5.2% and merchandise margins climbing 190 basis points on lower freight, tariff refunds, and better mix.
- For fiscal 2027, management guided to $2.565B–$2.593B revenue and EPS of $8.72–$9.00, slightly below Street models but implying 14–15% sales growth.
- A fresh $400M share repurchase plan boosts buyback capacity and signals confidence from Boot Barn’s leadership.
- Needham launched coverage at Buy with a $150 target, while UBS and TD Cowen trimmed targets but kept Buy ratings; the average Street target still sits near $215.
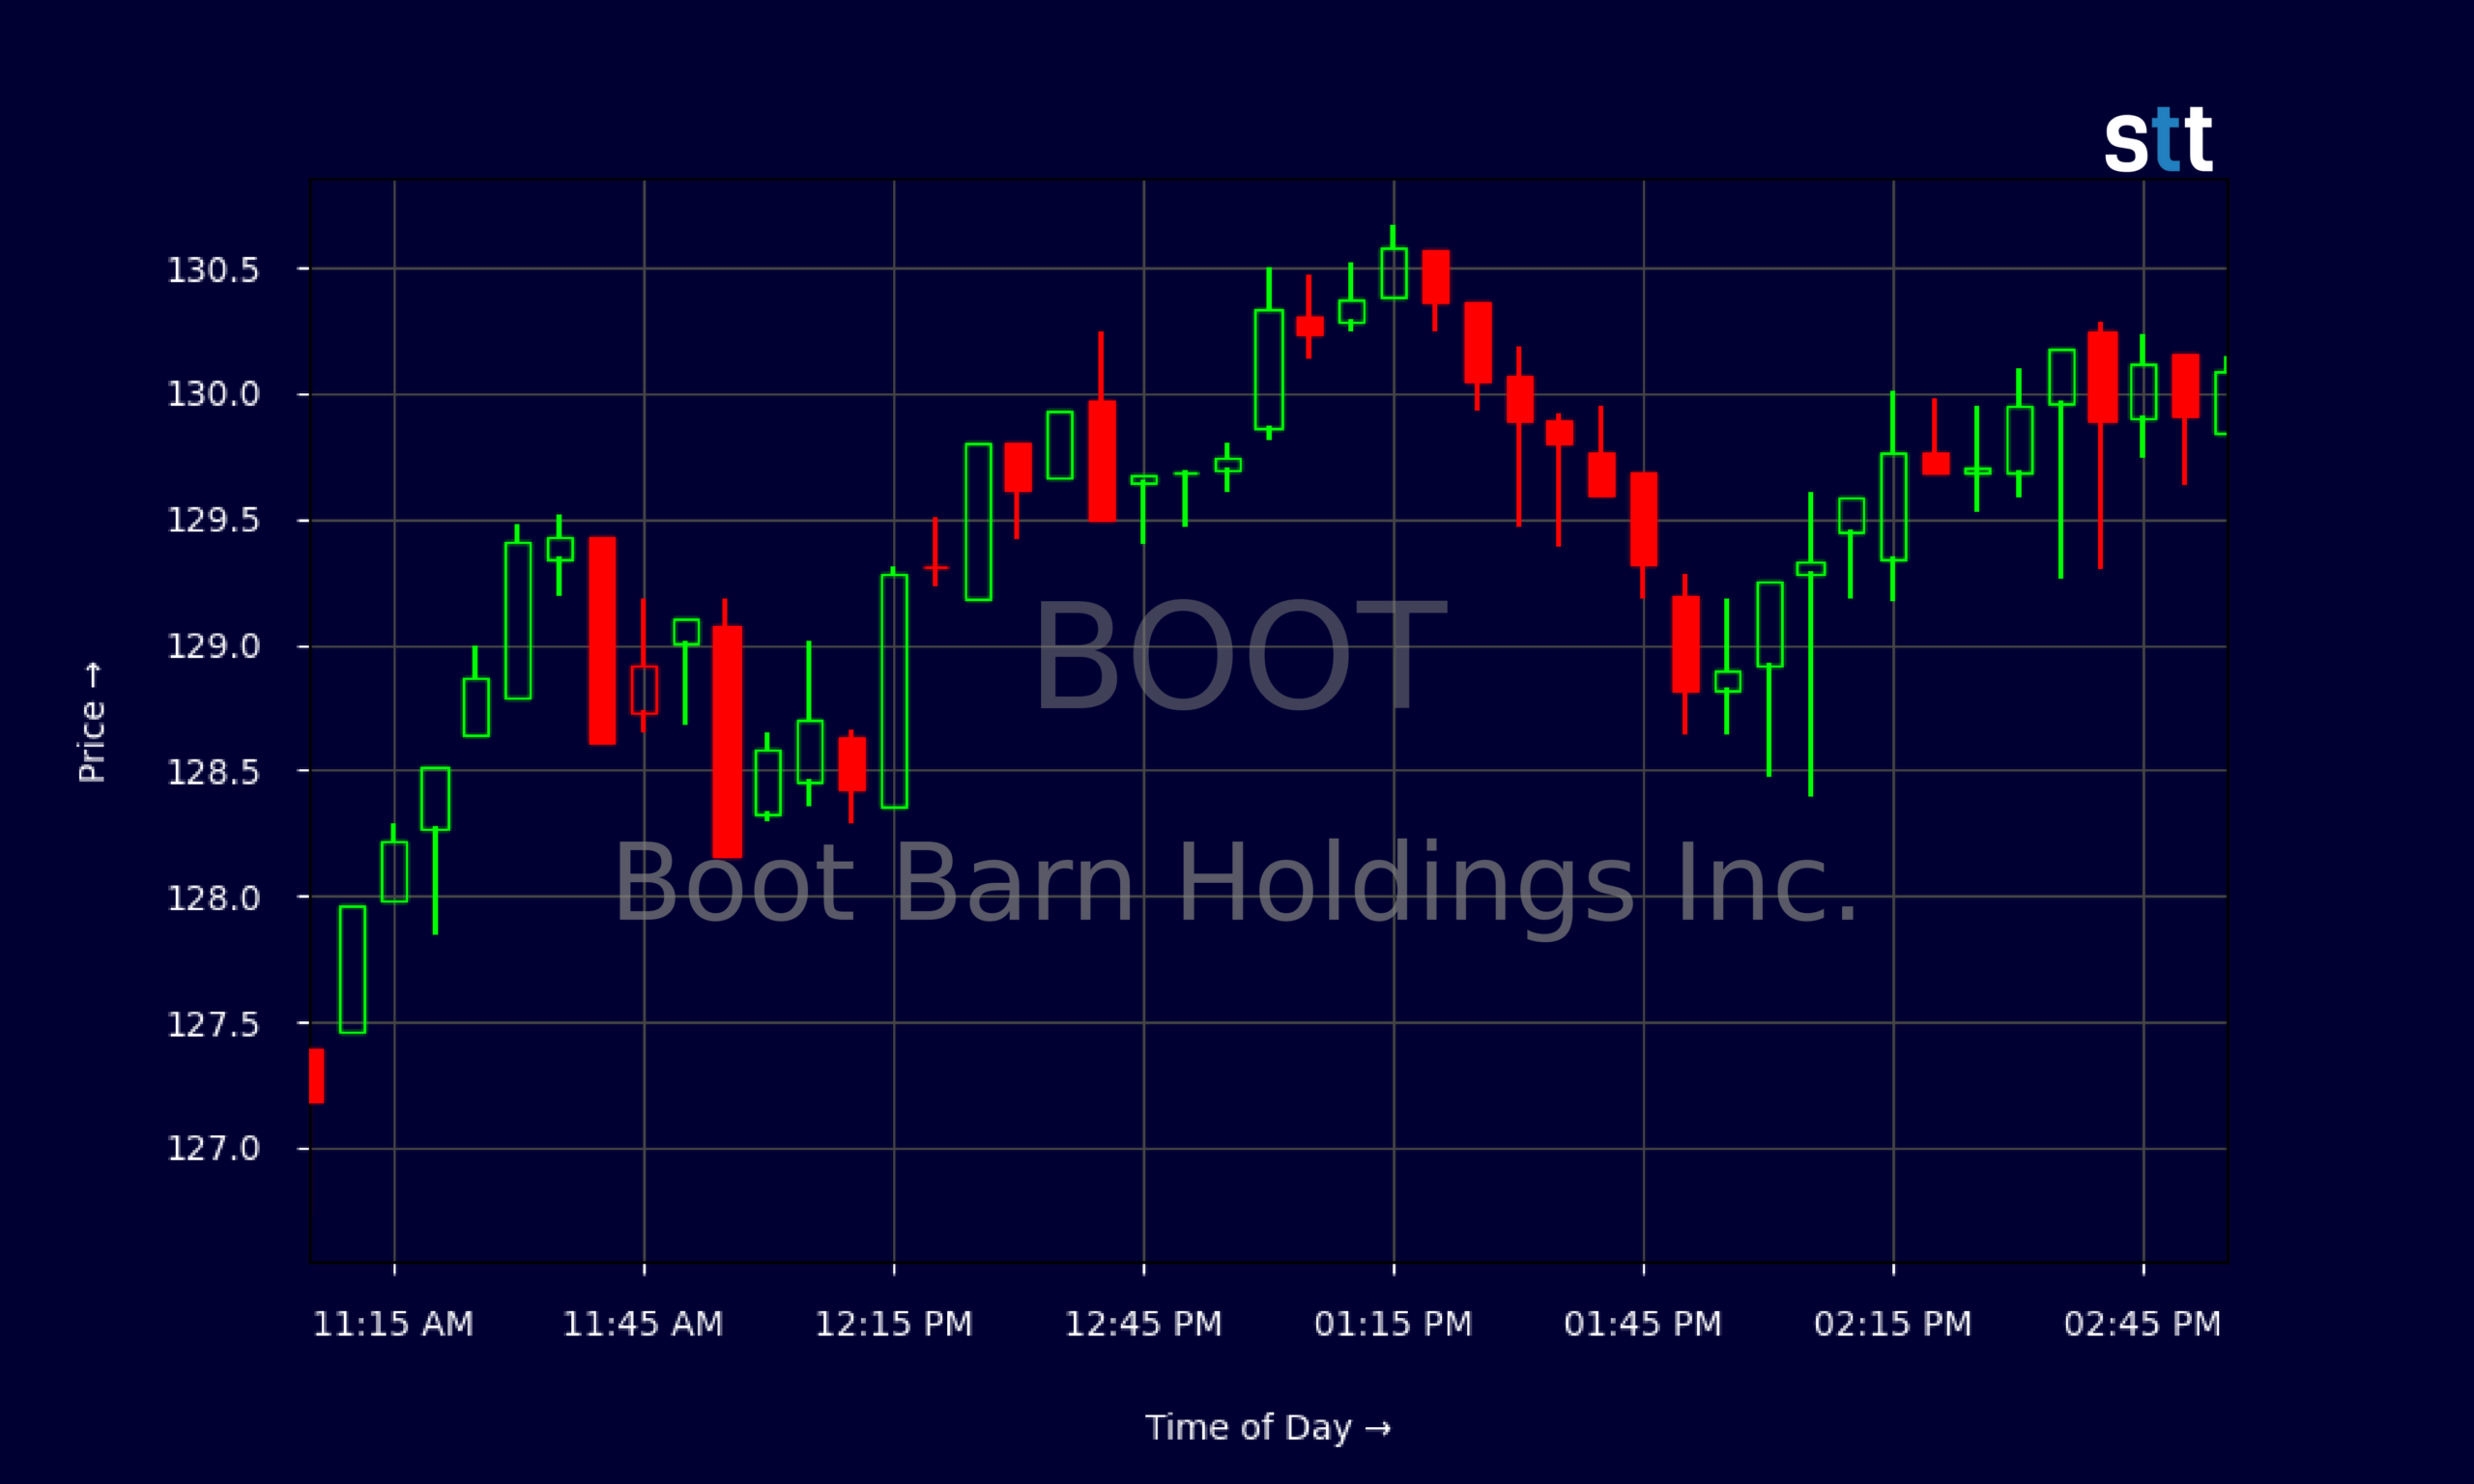
Live Update At 15:02:56 EDT: On Thursday, October 29, 2026 Boot Barn Holdings Inc. stock [NYSE: BOOT] is trending up by 15.1%! Discover the key drivers behind this movement as well as our expert analysis in the detailed breakdown below.
Quick Financial Overview
BOOT has ripped higher after earnings, closing at $130.41 on 2026/10/29 after opening the day near $118. That is a sharp rebound from lows around $110–$113 earlier in the week and marks a clear upside break from the recent $115–$122 trading band shown on the daily chart.
Intraday, BOOT spent the afternoon grinding between roughly $128 and $130, with tight five‑minute candles and higher lows. That kind of controlled push, rather than a wild spike and fade, often tells traders that real buying — not just short covering — is stepping in after the earnings release.
Fundamentally, Boot Barn Holdings Inc. is backing that tape action with solid numbers. Revenue over the last year is about $2.25B, and profitability is strong, with an EBIT margin near 13.8% and net margins just above 10%. Returns on equity around 19% and on assets around 10% show BOOT is turning its capital into real profits, not just sales growth.
More Breaking News
- CROX Stock Jumps As Barclays Sees Multi-Year Growth
- IOVA Stock Grinds Higher As Biotech Traders Watch Key Levels
- NUAI Stock Rattled As Fraud Lawsuit Targets AI Pivot Claims
- GOOG Stock Slides As Earnings Miss And Legal Risks Hit
On valuation, BOOT trades at roughly 15x earnings and 1.6x sales, well below its five‑year peak multiple. For traders, that combination — double‑digit growth, improving margins, and a mid‑teens P/E — creates a setup where positive surprises like this Q2 beat can trigger powerful re‑rating moves on the chart.
Why Traders Are Watching BOOT After This Earnings Beat
The latest earnings and guidance run from Boot Barn Holdings Inc. give traders a clean story: the core business is still growing, margins are expanding, and Wall Street is generally on board, even while some targets come down.
BOOT’s fiscal Q2 print checked key boxes. EPS at $1.73 topped expectations around $1.63–$1.64, and revenue of $581.8M edged past consensus. Same‑store sales were positive at 1.4%, not blazing hot but crucially still growing in a tough retail backdrop. The real kicker was margin: merchandise margins expanded by 190 basis points, helped by lower freight costs, tariff refunds, and a stronger product mix. That tells traders BOOT is not just selling more cowboy boots — it is selling them smarter.
Management also leaned into growth. BOOT talked up strong new‑store performance, rising national brand presence, and a push into the holidays with refreshed assortments, better in‑store presentation, higher marketing spend, and the relaunch of Boot Barn Workforce. Add the plan to open 75–80 new stores into fiscal 2027, and BOOT is clearly still in expansion mode, not defense.
On the flip side, guidance keeps expectations grounded. For fiscal 2027, BOOT is targeting revenue of $2.565B–$2.593B and EPS of $8.72–$9.00. That’s slightly below consensus models but still implies 14–15% sales growth and 140 basis points of margin expansion. UBS and TD Cowen cut their price targets, to $232 and $160 respectively, yet both kept Buy ratings, mirroring Needham’s new Buy at $150. With the stock around $130 and the average target near $215, traders are staring at a wide gap between the tape and the Street.
Layer on the fresh $400M share repurchase authorization, and BOOT has a potential buyer of size on every serious dip — the company itself. For active traders, that combination of growth, buybacks, and constructive analyst coverage is exactly why BOOT is now a high‑priority ticker on the screen.
Conclusion
For short‑term traders, BOOT’s post‑earnings surge is a classic momentum case study. You have a clean catalyst in the Q2 beat, confirmation from the chart as the stock breaks out of its recent range, and a stack of bullish — if slightly tempered — Wall Street calls backing the move. The 5‑minute chart shows controlled accumulation throughout the session, not a one‑and‑done gap, which often matters more than the headline number itself.
For swing traders digging deeper, the fundamentals behind Boot Barn Holdings Inc. still look like a strong retail growth story. Double‑digit historical revenue growth, high‑teens returns on capital, and a manageable balance sheet with a current ratio of 2.5 and modest leverage all support the idea that BOOT has room to keep scaling. The new $400M buyback plan and long‑term EPS guidance in the high single digits underscore management’s confidence in the path forward, even as they guide a touch below prior Street hopes.
At the same time, slower comps and trimmed price targets from UBS and TD Cowen are a reminder that no trend is straight up. Expectations have reset a bit, which can actually help future beats hit harder. As Tim Sykes likes to say, “Traders who show up prepared have an edge over those chasing every alert.” As Tim Bohen, lead trainer with StocksToTrade says, “Success in trading is more about cutting losses quickly than finding winners.” With BOOT, that preparation means watching how the stock behaves around this new higher range, tracking comps into Q3, and staying disciplined on entries and exits. This article is for educational and research purposes only and is not investment advice.
This is stock news, not investment advice. StocksToTrade News delivers real-time stock market updates tailored to highlight the key catalysts driving short-term price movements. Our coverage is designed for active traders and investors who thrive in fast-moving markets, with a focus on volatile sectors like penny stocks, AI stocks, Robinhood stocks and other momentum plays. From earnings reports and FDA approvals to mergers, new contracts, and unusual trading volume, we break down the events that can spark significant price action.
Looking to level up your trading game? Explore StocksToTrade, the ultimate platform for traders. With powerful tools designed for swing and day trading, integrated news scanning, and even social media monitoring, StocksToTrade keeps you one step ahead.
Check out our quick startup guide for new traders!
- How to Read Stock Charts: A Guide for Beginners
- Trading Plan: 6 Steps to Create One
- How To Create a Stock Watchlist
Ready to build your watchlists? Check out these curated lists:
Once your watchlist is set, take the next step and trade with confidence using StocksToTrade’s robust platform. Don’t miss out — grab your 14-day trial for just $7 and experience the edge you need to thrive in today’s fast-paced markets.