
Apple Inc. stocks have been trading down by -3.81 percent amid mounting concerns over slowing iPhone demand and regulatory pressures.
Key Takeaways For AAPL Traders
- UBS pegs AAPL’s September‑quarter revenue near $112.8B, with about $56B from iPhones, as higher selling prices offset a 5% drop in units and slower 14% growth.
- Shorter wait times for new iPhone Pro models, despite price hikes, hint at softer demand and downside risk to AAPL’s current iPhone estimates.
- Reports of at least a 15% cut to October iPhone 18 Pro and Pro Max component orders, tied to weaker demand and higher memory costs, hit AAPL shares.
- Oppenheimer warns on AAPL’s fiscal 2027 earnings as iPhone and Services growth cool, costs rise, and regulation bites, with the stock near the high end of its valuation range.
- A potential European Commission levy on large corporates would mean extra annual taxes for AAPL on EU revenue above EUR 100M, adding to margin pressure.
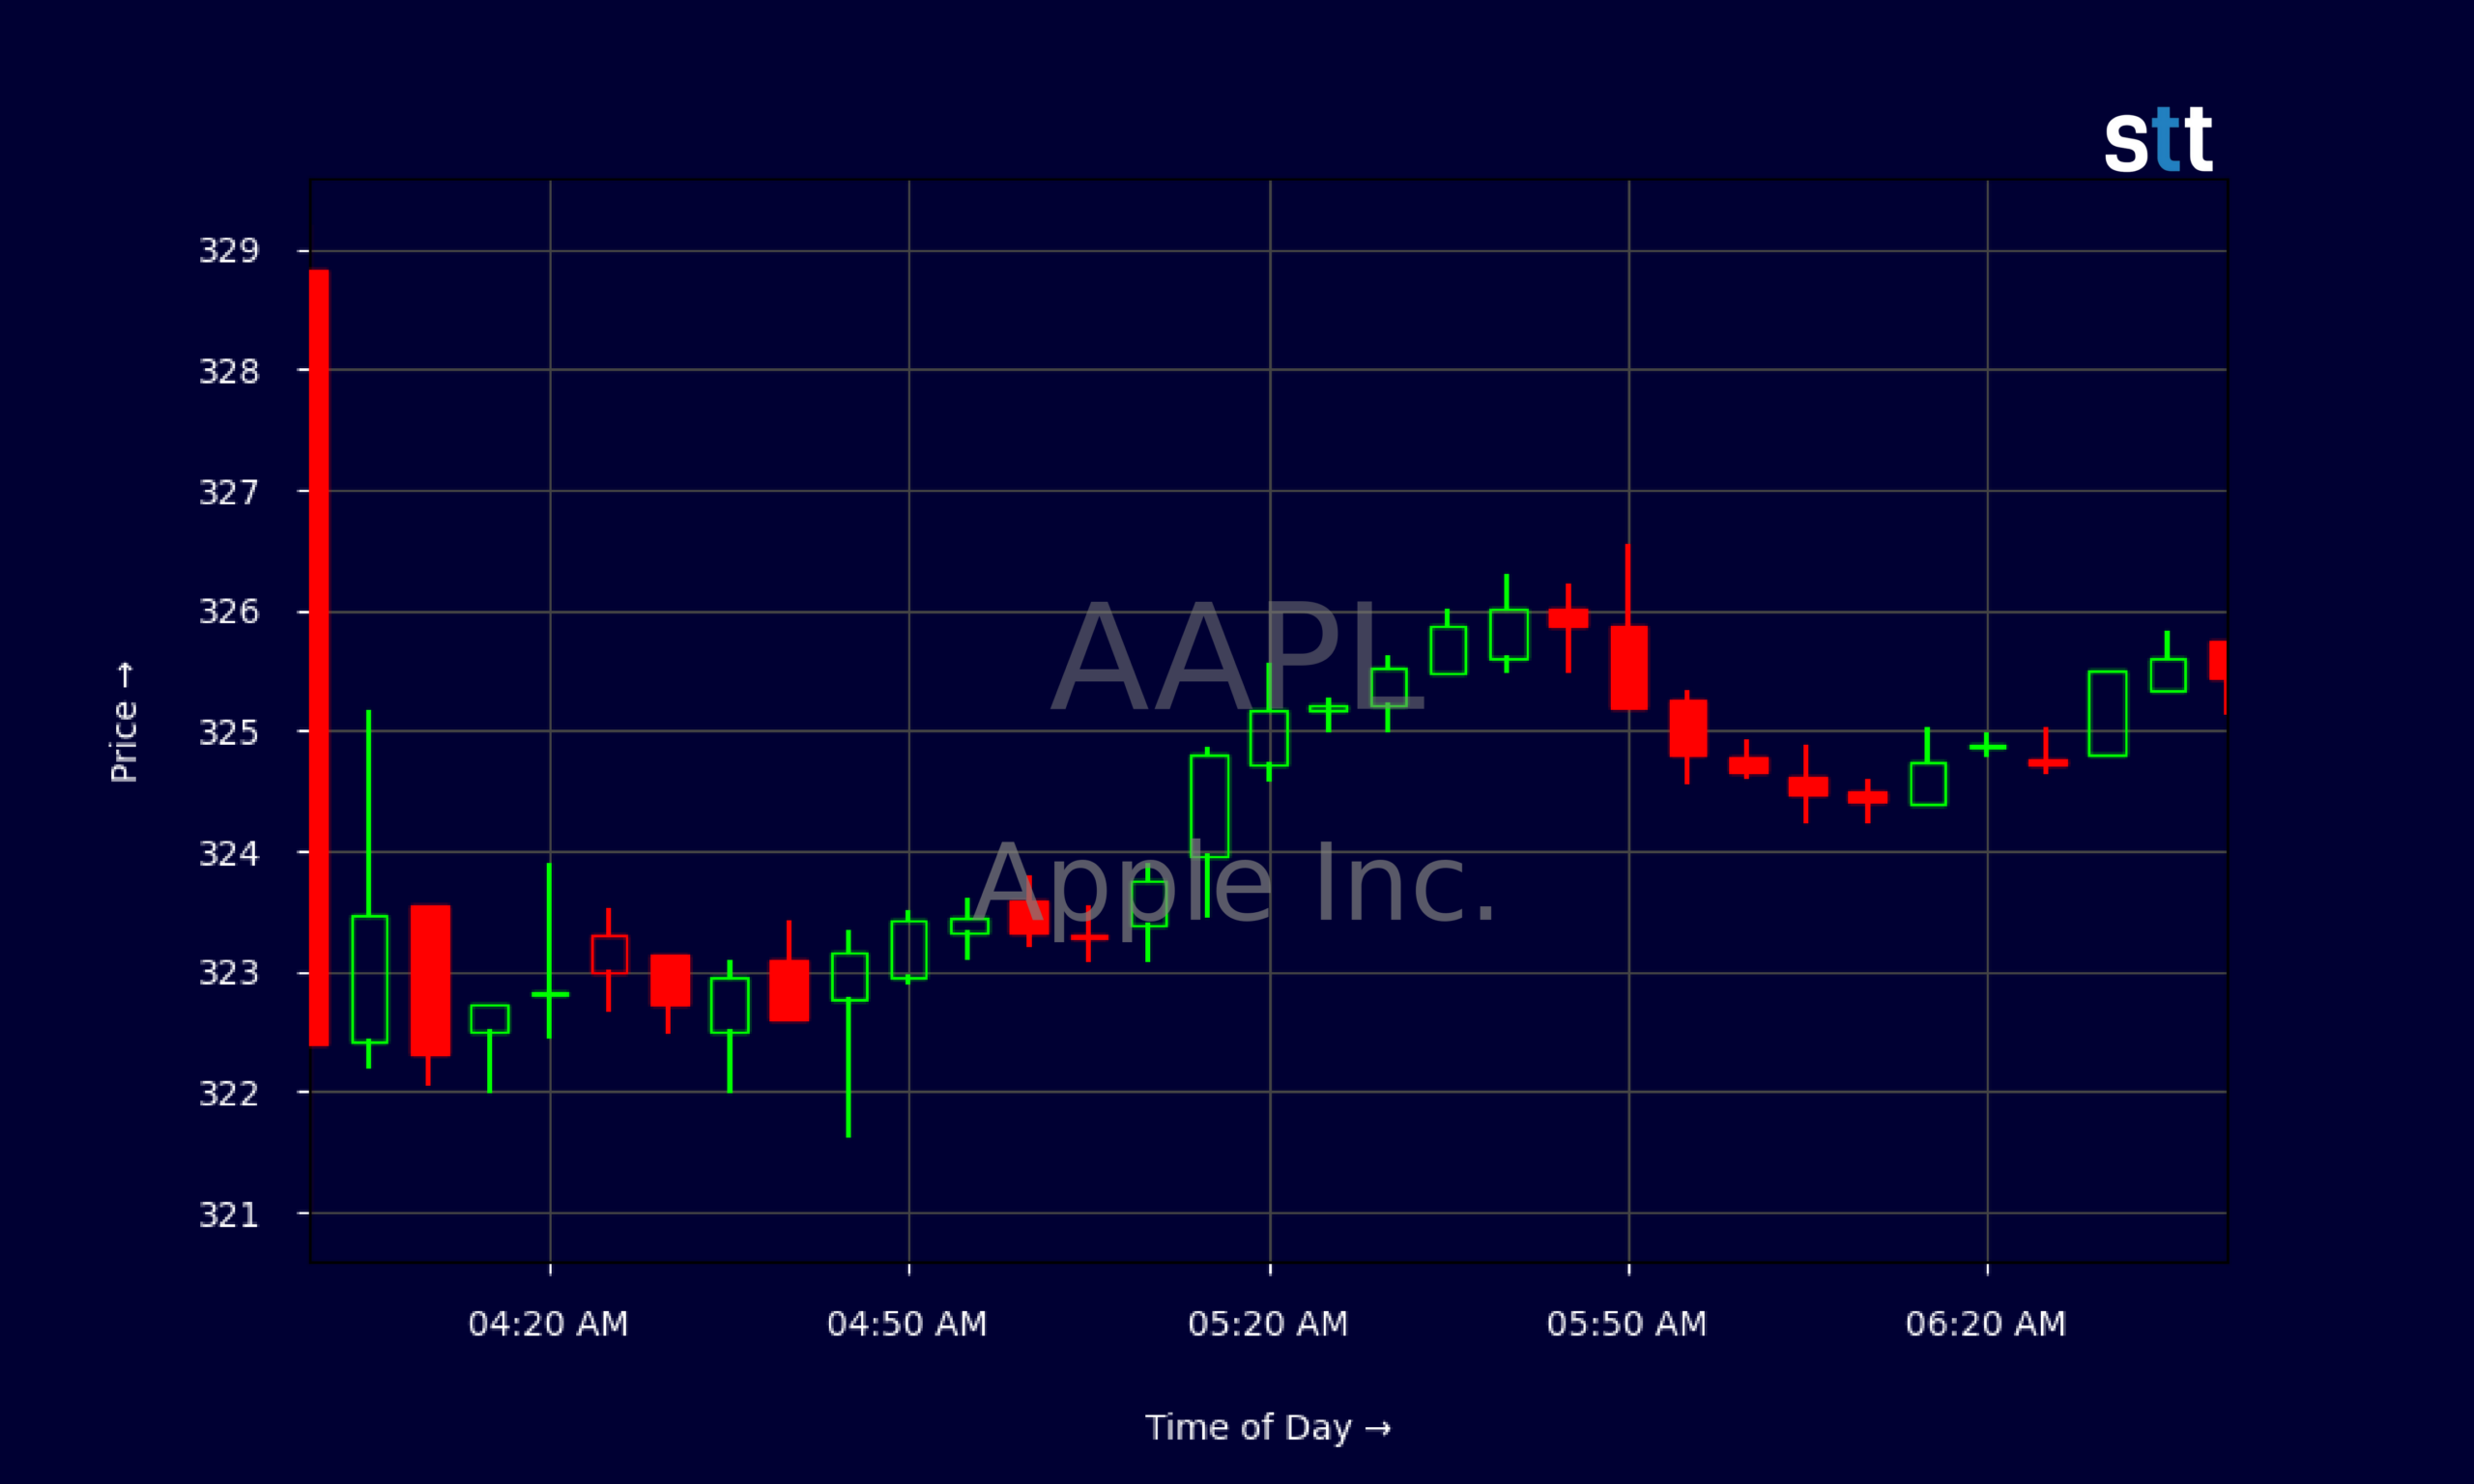
Live Update At 06:47:00 EST: On Tuesday, November 03, 2026 Apple Inc. stock [NASDAQ: AAPL] is trending down by -3.81%! Discover the key drivers behind this movement as well as our expert analysis in the detailed breakdown below.
Quick Financial Overview
AAPL is still a cash‑printing machine, but the tape shows a market starting to question the price tag. On the daily chart, Apple Inc. has been grinding in the mid‑$340s, with recent closes bouncing between about $337 and $349. That’s a tight range near all‑time‑rich levels, not a beaten‑down value play.
Intraday, the 5‑minute data around $322–$326 shows controlled selling and dip‑buying rather than panic. AAPL keeps finding buyers on pullbacks, which tells traders that big money still defends the name. But that support sits well above UBS’s $296 price target, a gap short sellers are watching.
More Breaking News
- AEHL Stock Pulls Back As Volatility Grips Low-Float Name
- EOSE Stock Slides As Legal Probes Raise Governance Fears
- Grab Holdings Falls 1% Today
- SNAP Stock Slips As User Miss, Regulation Weigh On Outlook
Fundamentals back up why AAPL commands a premium. Revenue over the last year sits around $416.2B, with gross margin near 48.7% and profit margin above 27%. Return on equity north of 140% is elite. At the same time, a P/E near 38.7 and price‑to‑sales around 10.5 scream “expensive.” Debt levels are manageable, current ratio roughly 1, and operating cash flow last quarter near $34.4B helped fund roughly $25.1B in buybacks and $4.0B in cash dividends. For traders, that mix means AAPL remains fundamentally strong, but already priced like it can’t stumble.
Why Traders Are Watching AAPL’s iPhone And Margin Story
Right now, AAPL’s story is all about how long the iPhone engine can run this hot at this price. UBS expects September‑quarter revenue of about $112.8B, roughly in line, with around $56B from iPhones. That’s solid on the surface. Higher average selling prices are doing the heavy lifting, masking a 5% decline in iPhone unit volumes and slowing revenue growth to 14% year over year from the low‑20% range. For momentum traders, that’s the first yellow flag: growth is leaning on pricing, not volume.
The second flag is demand quality. UBS notes that wait times for Apple Inc.’s new iPhone Pro models are actually getting shorter versus last year and even week over week, despite price increases. In a classic AAPL super‑cycle, you’d expect stretched wait times and supply struggling to catch up. Instead, the data hints at softer demand and downside risk to current iPhone estimates while AAPL trades around $345 against that $296 UBS target.
Then come the production cuts. Multiple reports say Apple Inc. asked suppliers to reduce October component orders for the iPhone 18 Pro and Pro Max by at least 15% versus earlier plans, blaming weaker demand and higher memory chip costs. That’s not just a headline; that’s management adjusting the physical build plan. The market reacted fast, with AAPL dropping up to 2.7% premarket on the news. For short‑term trading, that confirms one thing: any signal of iPhone weakness can move this stock in a hurry.
Layer on Oppenheimer’s view that fiscal 2027 earnings face pressure from slower iPhone and Services growth, memory cost inflation, margin compression, and regulatory headwinds, and traders are suddenly staring at a rich name with more ways to disappoint than surprise. Add the European Commission’s push for a new levy on large companies like Apple Inc., which would tack on an annual lump‑sum tax for EU revenue above EUR 100M, and margins get another potential squeeze. Meanwhile, AAPL is barely mentioned in the current AI infrastructure hype wave, leaving the stock looking a bit sidelined versus AI leaders stealing the trading spotlight.
Conclusion
For active traders, AAPL is no longer the simple “buy every dip and forget it” mega‑cap it used to feel like. Apple Inc. still pumps out over $30B in quarterly operating cash flow and throws off hefty free cash flow, but the market already rewards that with a P/E near 39 and a five‑year‑high‑type valuation. When a stock is this crowded and this expensive, the risk isn’t that things blow up overnight. It’s that even mild disappointment — like 15% iPhone 18 Pro production cuts or softening wait‑time data — gets punished.
Oppenheimer’s longer‑term warnings on 2027 earnings and the European Commission’s possible levy add slow‑burn overhangs. They won’t break AAPL’s business, but they can chip away at margins and compress that premium multiple. And with UBS sticking to a Neutral rating and a $296 target while Apple Inc. trades meaningfully above that mark, swing traders have a clear reference for where big‑bank models think fair value sits.
This is exactly the kind of setup Tim Sykes and Tim Bohen hammer on with students: “Trade the price action, not the story.” As Tim Bohen, lead trainer with StocksToTrade says, “Time and experience have taught me that missed opportunities are part of the game. There’s always another setup around the corner.” AAPL’s story is legendary, but the tape is what pays. For now, that tape says respect the uptrend, watch iPhone headlines like a hawk, and be ready to cut losses fast if this crowded trade finally runs out of buyers.
This is stock news, not investment advice. StocksToTrade News delivers real-time stock market updates tailored to highlight the key catalysts driving short-term price movements. Our coverage is designed for active traders and investors who thrive in fast-moving markets, with a focus on volatile sectors like penny stocks, AI stocks, Robinhood stocks and other momentum plays. From earnings reports and FDA approvals to mergers, new contracts, and unusual trading volume, we break down the events that can spark significant price action.
Looking to level up your trading game? Explore StocksToTrade, the ultimate platform for traders. With powerful tools designed for swing and day trading, integrated news scanning, and even social media monitoring, StocksToTrade keeps you one step ahead.
Check out our quick startup guide for new traders!
- How to Read Stock Charts: A Guide for Beginners
- Trading Plan: 6 Steps to Create One
- How To Create a Stock Watchlist
Ready to build your watchlists? Check out these curated lists:
Once your watchlist is set, take the next step and trade with confidence using StocksToTrade’s robust platform. Don’t miss out — grab your 14-day trial for just $7 and experience the edge you need to thrive in today’s fast-paced markets.