
Apple Inc. stocks have been trading down by -4.29 percent amid reports of weakening iPhone demand and softer services growth.
Key Takeaways For AAPL Traders
- UBS expects September-quarter revenue near $112.8B with roughly $56B from iPhones, but sees iPhone growth slowing to 14% and keeps a Neutral rating with a $296 AAPL price target.
- UBS also reports shrinking wait times for new iPhone Pro models, hinting at softer demand and downside risk to iPhone estimates with AAPL trading around $345.
- Multiple reports say Apple has cut October iPhone 18 Pro and Pro Max component orders by at least 15% amid weaker demand and higher memory chip costs, knocking AAPL 1.2% and 2.7% premarket.
- Oppenheimer warns of downside risk to fiscal 2027 earnings from slower iPhone and Services growth, rising memory costs, margin pressure, and regulation, even as AAPL trades near the top of its long‑term valuation range.
- The European Commission is weighing a new levy on big companies that would force Apple to pay an annual lump‑sum tax on EU revenue above EUR 100M, adding another margin headwind.
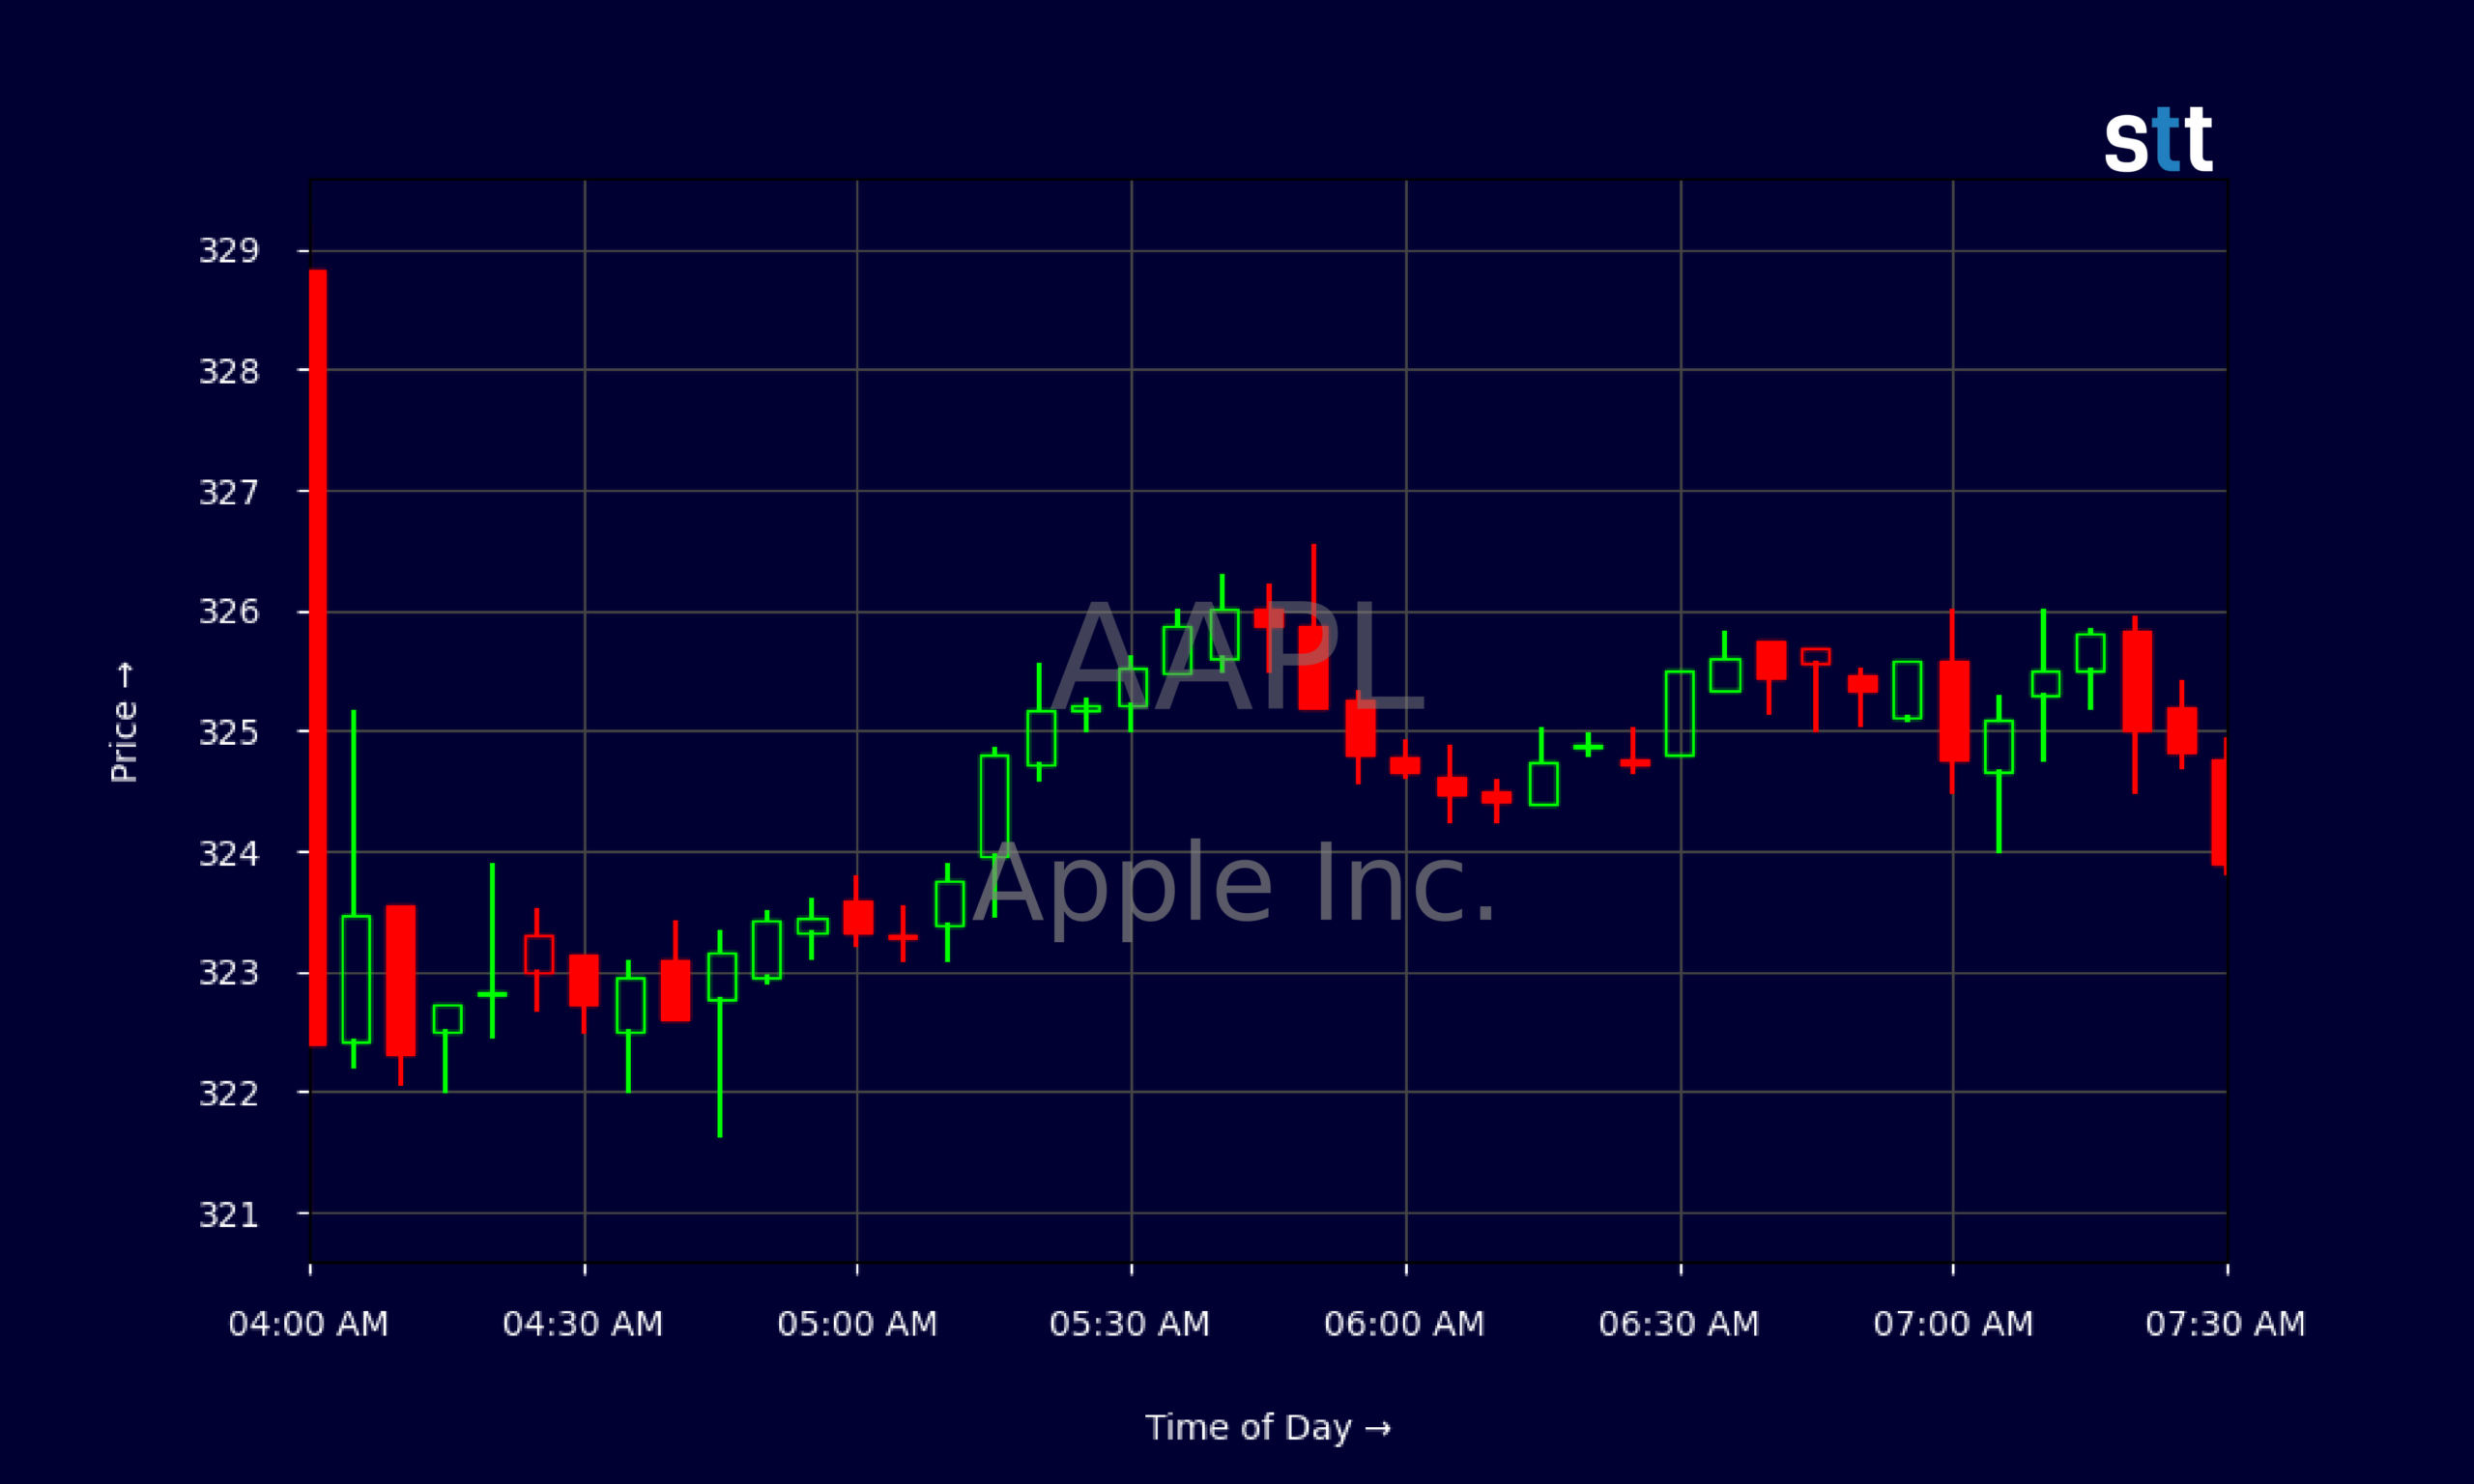
Live Update At 07:33:03 EST: On Tuesday, November 03, 2026 Apple Inc. stock [NASDAQ: AAPL] is trending down by -4.29%! Discover the key drivers behind this movement as well as our expert analysis in the detailed breakdown below.
Quick Financial Overview
AAPL is still a cash‑printing machine, but the chart and the ratios say the bar is high. On the multi‑day chart, AAPL has been grinding in the mid‑$330s to mid‑$340s, recently closing near $338 after failing to hold moves above $349. That action tells traders the stock is struggling to break out as sellers show up on strength.
Intraday, the 5‑minute tape around $322–$326 shows a tight range with repeated fades from $326. For short‑term AAPL traders, that’s classic “supply overhead” behavior. The stock isn’t collapsing, but buyers are cautious at the top of the range.
More Breaking News
- SNAP Stock Slips As User Miss, Regulation Weigh On Outlook
- OPEN Adds Crypto Entrepreneur To Board As Earnings Catalyst Nears
- CIFR Stock Slumps As Texas Policy Risk Rattles Cipher Mining
- Snap Stock Slips As User Miss, Regulation And Insider Sale Weigh
Fundamentally, Apple booked about $109.4B in quarterly revenue and nearly $29.8B in net income, with fat profit margins near 28% and gross margin near 49%. AAPL’s return on equity above 140% is off the charts. But the market already knows this. The key issue is valuation: a P/E around 38.7 and price‑to‑sales over 10 put AAPL near a five‑year high multiple. For traders, that means any hint of slowing growth or weaker iPhone demand can flip the script fast.
Why Traders Are Watching AAPL Right Now
The real story for AAPL is not where it is today, but how little room for error the stock has at these levels. UBS expects Apple’s September‑quarter revenue around $112.8B, roughly in line, with about $56B coming from iPhones. That’s huge. But iPhone revenue growth is expected to slow to 14% year over year from the low‑20% range. When AAPL trades near a five‑year‑high valuation and growth decelerates, the risk/reward shifts for active trading.
UBS also notes that wait times for the latest iPhone Pro models are shortening compared with last year, even after price hikes. On the surface, faster delivery sounds good. For AAPL traders, though, it is a warning sign. If demand were red‑hot, wait times would stretch out, not shrink. That’s why UBS keeps a Neutral rating and a $296 target while AAPL changes hands closer to $345. The stock price assumes stronger iPhone strength than the checks suggest.
Then come the production cuts. Several reports say Apple asked suppliers to slash October component orders for iPhone 18 Pro and Pro Max by at least 15%, citing weaker demand and higher memory chip costs. AAPL dropped about 1.2% on the news and nearly 2.7% premarket in another headline. Production cuts are hard data. They say Apple is lowering its own expectations for this iPhone cycle, just as memory costs squeeze margins.
Oppenheimer pushes this out to the longer term, flagging downside risk to fiscal 2027 earnings. The firm sees slower iPhone and Services growth, cost inflation, and margin compression, all while AAPL trades near the top of its long‑term range. Add in a potential EU levy on big corporations—forcing companies like Apple to pay an annual lump‑sum tax on EU revenue over EUR 100M—and the margin picture darkens again. Finally, AAPL is not front‑and‑center in current AI infrastructure buzz; it is mentioned mainly as an upcoming earnings name, while other tech players ride the AI hype. For traders, that means catalysts are more about iPhone cycles and regulation than AI upside.
Conclusion
For AAPL, the setup heading into the next few quarters is simple but unforgiving. The company remains a giant with over $100B in quarterly revenue, massive free cash flow around $31.9B, and a fortress balance sheet. Yet UBS and Oppenheimer both point to the same pressure points: slowing iPhone momentum, rising memory costs, margin compression, and a stretched valuation. Layer on possible new EU taxes and a lack of headline AI excitement, and AAPL looks priced for near‑perfection while the narrative turns more cautious.
This is exactly the type of environment where active traders need to think like risk managers, not fanboys. As Tim Bohen, lead trainer with StocksToTrade says, “For me, trading is more about managing risk than finding the next big mover.” AAPL’s daily chart shows heavy supply in the mid‑$340s, and the news flow just gave short‑biased traders clearer levels to lean on. Breakdowns through recent lows can accelerate as funds reassess long‑term growth assumptions, while any surprise upside on margins or Services could trigger sharp squeezes.
As Tim Sykes likes to remind traders, “The market doesn’t care about your opinion, only the price action and the catalyst.” For AAPL, the catalysts right now skew negative, and the price action is starting to reflect that. This article is for educational and research purposes only, but for traders who study the chart, respect the range, and cut losses fast, AAPL’s current tension between rich valuation and softening iPhone demand offers a textbook case study in managing risk around a crowded mega‑cap name.
This is stock news, not investment advice. StocksToTrade News delivers real-time stock market updates tailored to highlight the key catalysts driving short-term price movements. Our coverage is designed for active traders and investors who thrive in fast-moving markets, with a focus on volatile sectors like penny stocks, AI stocks, Robinhood stocks and other momentum plays. From earnings reports and FDA approvals to mergers, new contracts, and unusual trading volume, we break down the events that can spark significant price action.
Looking to level up your trading game? Explore StocksToTrade, the ultimate platform for traders. With powerful tools designed for swing and day trading, integrated news scanning, and even social media monitoring, StocksToTrade keeps you one step ahead.
Check out our quick startup guide for new traders!
- How to Read Stock Charts: A Guide for Beginners
- Trading Plan: 6 Steps to Create One
- How To Create a Stock Watchlist
Ready to build your watchlists? Check out these curated lists:
Once your watchlist is set, take the next step and trade with confidence using StocksToTrade’s robust platform. Don’t miss out — grab your 14-day trial for just $7 and experience the edge you need to thrive in today’s fast-paced markets.