
Amazon.com Inc. stocks have been trading up by 2.25 percent amid strong AWS growth and accelerating AI-driven cloud demand.
Key Takeaways For AMZN Traders
- Q3 2026 delivered record 13.9% operating margin on $201.9B in sales, with AMZN leaning hard into AI capex even as free cash flow turns negative.
- AWS net sales jumped to $45.98B and operating income to $17.77B, reinforcing Amazon.com Inc.’s cloud and AI engines as core profit drivers.
- CEO Andy Jassy is targeting AWS growth above 40% in 2027–2028, backed by a $578B backlog and ambitions for two trillion‑dollar‑revenue businesses.
- Bedrock and Amazon silicon (Graviton, Trainium) are scaling fast, with Fortune 500 AI spend up nearly 7x and more than $2B in customer savings in Q3.
- UBS and Freedom Broker raised AMZN price targets, leaning into a multi‑year AWS acceleration story despite heavy 2026 capex and Q4 cash burn.
Live Update At 08:18:22 EST: On Thursday, November 05, 2026 Amazon.com Inc. stock [NASDAQ: AMZN] is trending up by 2.25%! Discover the key drivers behind this movement as well as our expert analysis in the detailed breakdown below.
Quick Financial Overview
AMZN’s chart tells you why traders are glued to this name right now. After a post‑earnings dip, the stock has ripped from a recent low near $232.54 (2026/10/30) to a close of $266.03 on 2026/11/04. That is a sharp, momentum‑style bounce of roughly 14%, powered by one thing: the AWS and AI story catching fire.
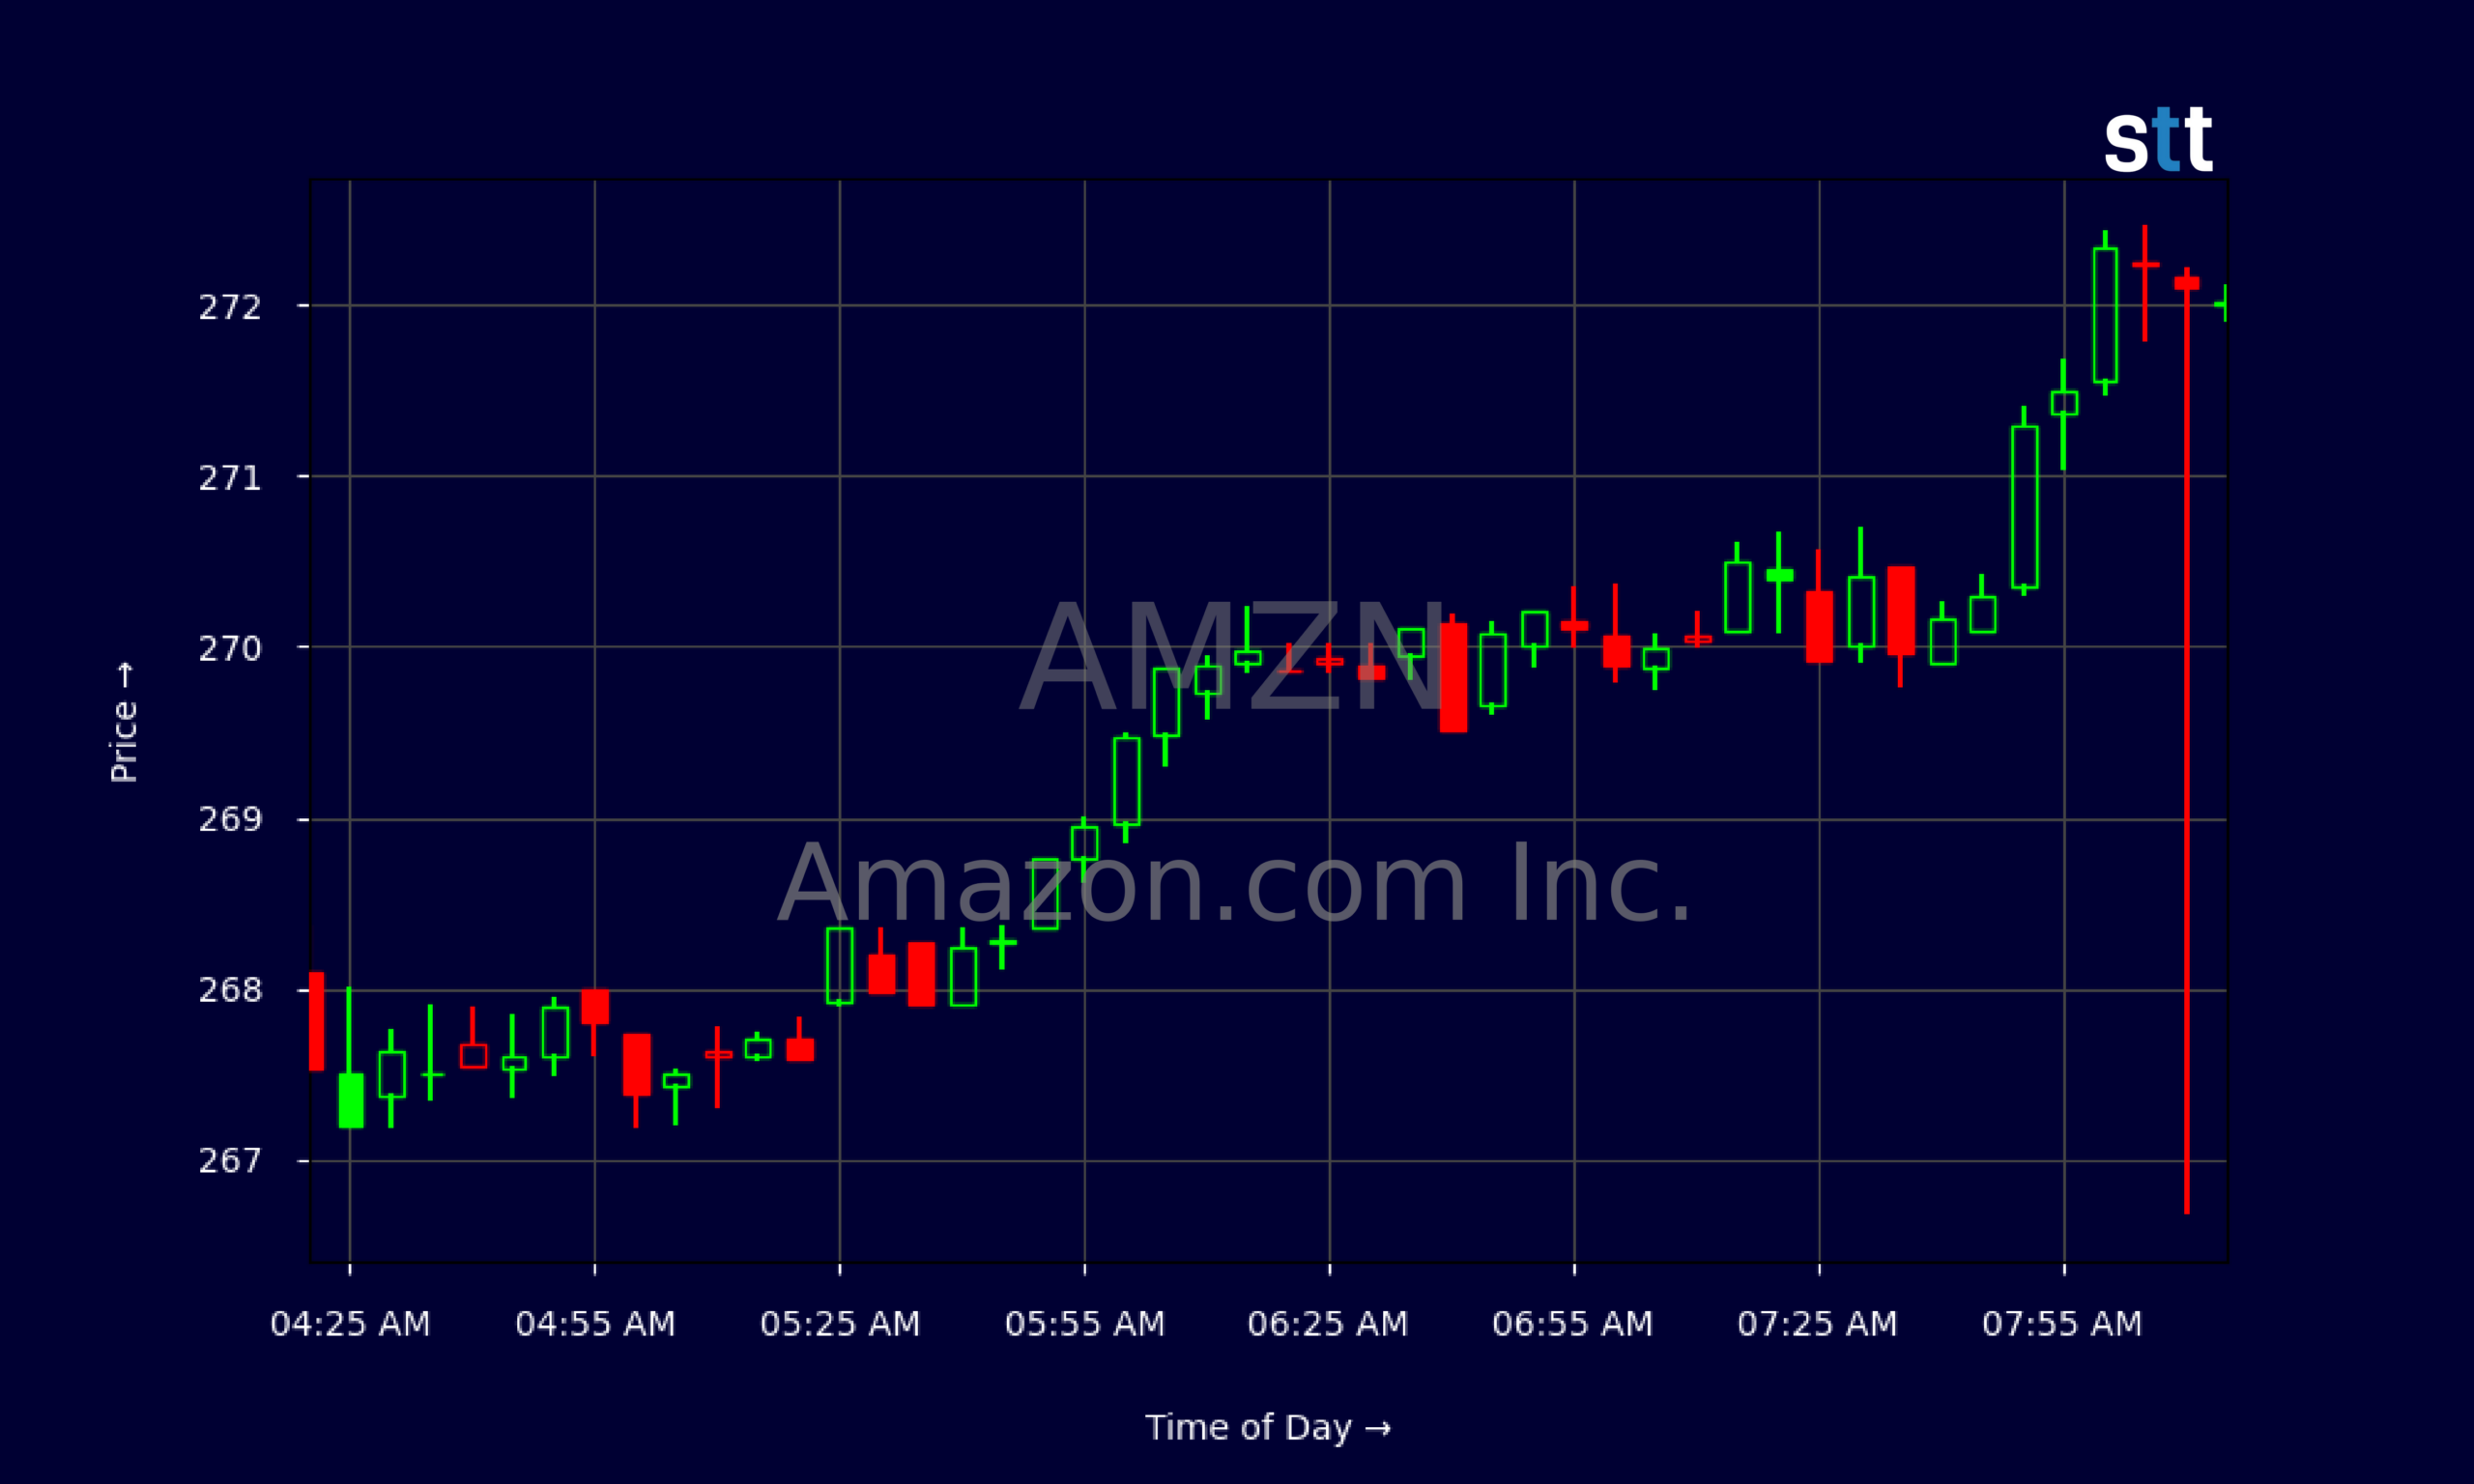
Intraday, the 5‑minute tape shows AMZN grinding higher in pre‑market, holding the $268–$272 band with shallow pullbacks. That kind of tight range after a big multi‑day move usually signals strong hands in control rather than panicky profit‑taking.
Fundamentals back the price action. Amazon.com Inc. just printed $201.9B in Q3 revenue with a record 13.9% operating margin and $49.51B in EBITDA. Key profitability ratios are stout: EBIT margin around 23% and gross margin above 50%. Return on equity north of 30% and a debt‑to‑equity ratio of 0.23 show AMZN is not stretching its balance sheet to chase AI.
More Breaking News
- MRVL Stock Slides As $115B Lumentum Deal Rattles Traders
- EOSE Stock Rises As Q3 Revenue Jumps And U.S. Capacity Ramps
- SK Hynix Rises 6% After Recent Pullback
- CDW Stock Climbs As Analysts Hike Targets And Board Strengthens
Yes, free cash flow was deeply negative at about -$34.84B this quarter, mainly from $77.26B in capital expenditure. But operating cash flow of $42.42B shows the core machine is spitting off cash. For active trading, that mix — strong margins, heavy reinvestment, and a rising stock — often translates into buy‑the‑dip setups, not “broken story” warnings.
Why Traders Are Watching AMZN’s AWS And AI Machine
The core catalyst for AMZN right now is simple: AWS is re‑accelerating at scale. Q3 AWS net sales jumped to $45.98B from $33.0B a year earlier, while operating income climbed to $17.77B from $11.43B. That is not just growth — that is margin expansion in the high‑margin piece of Amazon.com Inc.’s empire.
Management says AWS revenue is growing 39.3% year over year, with a roughly $184B run‑rate and around 39% margin. On top of that sits a $578B backlog of contracted work. For traders, backlog matters. It is future revenue that is already spoken for, which can help smooth earnings as AMZN plows money into AI infrastructure.
CEO Andy Jassy is leaning into that demand with an aggressive plan: about $220B in 2026 capex, mostly for data centers, servers, and networking to support AWS and Amazon Bedrock. That spend has flipped free cash flow negative, and the market initially flinched. But the message from the numbers is that 2026 AWS capacity is sold out, 2027 is largely booked, and 2028 is already filling up. Capex today is tied to pre‑sold demand tomorrow.
The AI stack is turning into its own growth engine inside AMZN. Bedrock has become AWS’s fastest‑growing multi‑billion‑dollar service, with Fortune 500 spending nearly 7x higher and token volume roughly 17x higher year over year. Custom silicon — Graviton CPUs and Trainium accelerators — is growing triple‑digits, with revenue commitments up more than 20x and over $2B in customer savings in Q3 alone.
That matters for trading because it deepens customer lock‑in and opens new profit pools. Amazon.com Inc. is not just selling cloud space; it is becoming an integrated AI infrastructure provider. Management even plans to sell Trainium chips outside AWS by late 2027, hinting at a potential semi‑style revenue leg many models still underweight.
Wall Street is taking the hint. UBS raised its AMZN price target to $352, while Freedom Broker bumped its target from $255 to $330. Both keep Buy‑side ratings and frame this as the start of a multi‑year AWS acceleration, not the end. For momentum traders, that analyst backdrop often supports sustained dips‑get‑bought action.
Conclusion
AMZN now trades like a pure AI and cloud compounder wrapped inside a global retail and logistics platform. Q3 2026 numbers — $201.9B in revenue, 13.9% operating margin, and 39% AWS growth — show the core business is not limping into this capex wave; it is charging into it with record profitability.
The tension for traders is clear. On one side, Amazon.com Inc. is burning cash in the near term, with about -$34.84B in free cash flow and a massive ~$220B 2026 capex plan. On the other side, AWS capacity is effectively pre‑sold into 2028, the backlog stands at $578B, and AI platforms like Bedrock and Trainium are scaling faster than anything in AWS history. That is the kind of setup where the market often tolerates short‑term pain for long‑term upside — until execution stumbles.
Short‑term, AMZN’s push from the low $230s to the mid‑$260s has created a clear battleground. Breakouts above recent highs near $271–$272 on rising volume would confirm that the AWS/AI narrative still has fuel. Failure there, with heavy selling, would tell traders the stock needs more time to digest the capex shock.
Tim Sykes loves to remind traders, “Patterns repeat because human nature doesn’t change — study the past so you’re ready for the next move.” As Tim Bohen, lead trainer with StocksToTrade says, “If you’re still guessing at the end of your analysis, it’s probably not a trade worth taking.”. With AMZN, that means tracking how prior high‑growth, high‑capex cycles traded, watching the chart as closely as the AWS backlog, and always staying nimble. This analysis is for educational and research purposes only, not investment advice.
This is stock news, not investment advice. StocksToTrade News delivers real-time stock market updates tailored to highlight the key catalysts driving short-term price movements. Our coverage is designed for active traders and investors who thrive in fast-moving markets, with a focus on volatile sectors like penny stocks, AI stocks, Robinhood stocks and other momentum plays. From earnings reports and FDA approvals to mergers, new contracts, and unusual trading volume, we break down the events that can spark significant price action.
Looking to level up your trading game? Explore StocksToTrade, the ultimate platform for traders. With powerful tools designed for swing and day trading, integrated news scanning, and even social media monitoring, StocksToTrade keeps you one step ahead.
Check out our quick startup guide for new traders!
- How to Read Stock Charts: A Guide for Beginners
- Trading Plan: 6 Steps to Create One
- How To Create a Stock Watchlist
Ready to build your watchlists? Check out these curated lists:
Once your watchlist is set, take the next step and trade with confidence using StocksToTrade’s robust platform. Don’t miss out — grab your 14-day trial for just $7 and experience the edge you need to thrive in today’s fast-paced markets.